
SUMMARY: December global PMIs are strong so far; the global goods economy continues to be resilient, evidence of sustained strong consumer demand. That’s even as COVID-sensitive (services) personal consumption has caught up to insensitive (goods) consumption. The breadth of global PMIs expanding (while COVID sentiment is improving) is a tailwind to 10yr yields and deep Cyclicals.
As we discussed last week, a near-term risk to the 10yr, yield curve, and China-levered names is that supply chain news sentiment is worsening again and China’s zero COVID policy COULD be a major headwind. However, stocks with the worst supply chain sentiment have outperformed recently despite worsening news sentiment. Investors are getting more comfortable with the supply chain outlook, likely aided by better Omicron severity sentiment.
China related risks remain front and center. Evergrande halted trading following a local media report it has been ordered to tear down apartment blocks in Hainan province. We are waiting for updated credit data to assess perceived contagion risk.
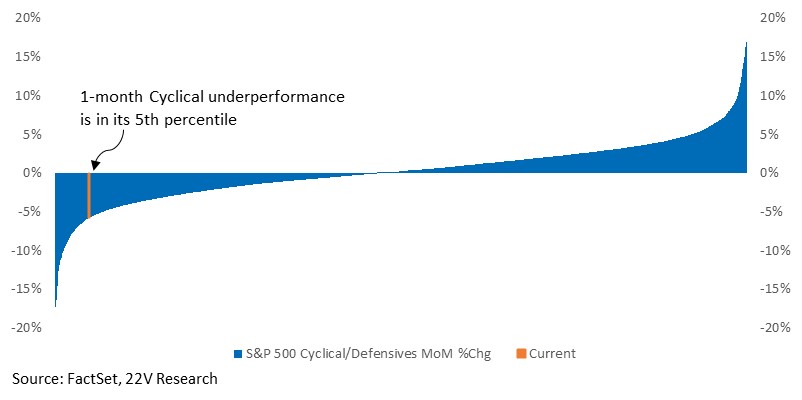
Uncertainty about the growth outlook, inflation, and fed policy pushed Cyclicals lower in 4Q, but gains earlier in the year left Cyclicals up nearly 6% versus Defensives in 2021. Worries about omicron and the fed crushing growth helped support Defensives late last year. While the Fed’s intent is to slow inflation and growth gradually, the firming inflation and funds rate are ultimately a bigger tailwind for Cyclical sectors, which should rebound in 2022.
Investors bid up high quality, low volatility names in 4Q leaving the NTM PE spread between Value and Growth is in the bottom 10th percentile of its historical range. High Value Industrial stocks’ fell even further. The improving backdrop for Industrials and Value makes this group interesting. Some of these names, like Airlines, are also levered to Reopening. That trade continued to struggle, held back by travel disruptions related to Omicron
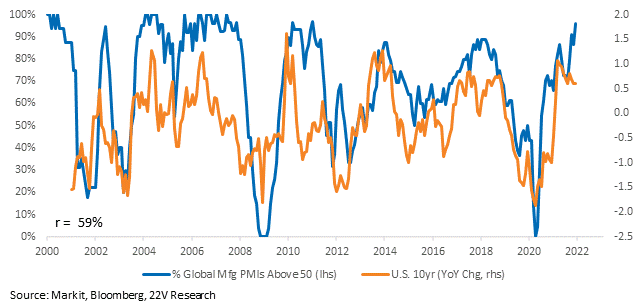
MARKET VIEWS: Global PMI data are rolling out; 25 of the 44 Markit manufacturing PMIs we track have been released. Of those 25, 24 are above 50 (the only exception is Myanmar, which is suffering a military coup). The global goods economy remains resilient, evidenced by sustained strong consumer demand. That’s even as COVID-sensitive (services) personal consumption has caught up to insensitive (goods) consumption. The breadth of global PMIs expanding (while COVID sentiment is improving) is a tailwind to 10yr yields and deep Cyclicals.
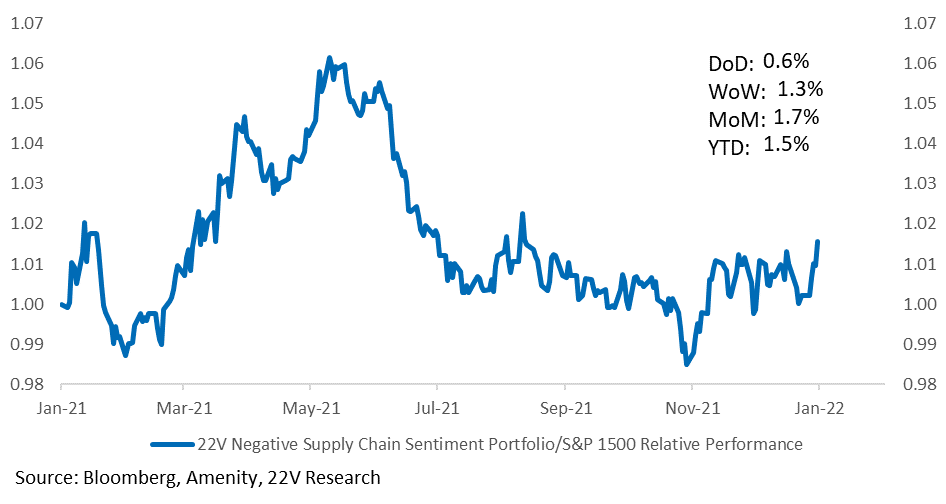
Looking forward, supply chain constraints are a concern into a possible Omicron wave in Asia. As we discussed last week, a near-term risk to the 10yr, yield curve, and China-levered names is that supply chain news sentiment is worsening again and China’s zero COVID policy COULD be a major headwind. However, stocks with the worst supply chain sentiment have outperformed recently despite worsening news sentiment. Investors are getting more comfortable with the supply chain outlook, likely aided by better Omicron severity sentiment. Worst-case scenarios are off the table, which should imply less stringent lockdowns. FYI our friend Noah Smith held an insightful interview with Ryan Petersen, founder and CEO of Flexport, a supply chain software company, on bottlenecks. Check it out HERE.
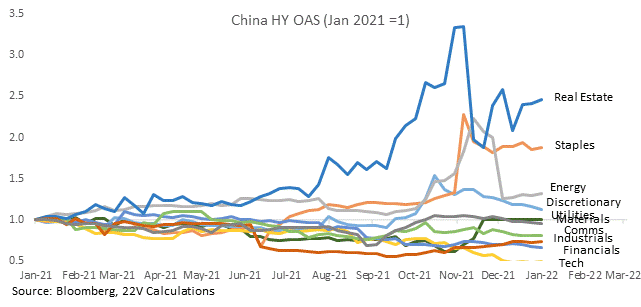
Evergrande halted trading following a local media report it has been ordered to tear down apartment blocks in Hainan province. We are waiting for updated credit data to assess perceived contagion risk. The below chart does not reflect the overnight news. As of Friday, perceived contagion risk was still low.
Industrials Support: Market internals have shifted multiple times over the past few months. Uncertainty about the growth outlook, inflation and fed policy pushed Cyclicals lower in 4Q, but gains from earlier in the year left Cyclicals up nearly 6% versus Defensives in 2021.
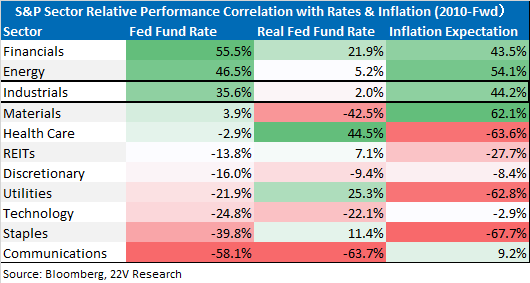
Inflation remains high and will trend higher over the next few months, putting upward pressure on rate hike expectations. As long as the Fed’s intent is to slow inflation and growth gradually, the firming inflation and funds rate are a support for Cyclical sectors more than Defensives. Industrials, which trailed the market over the past month, are well correlated to the funds rate and inflation expectations.
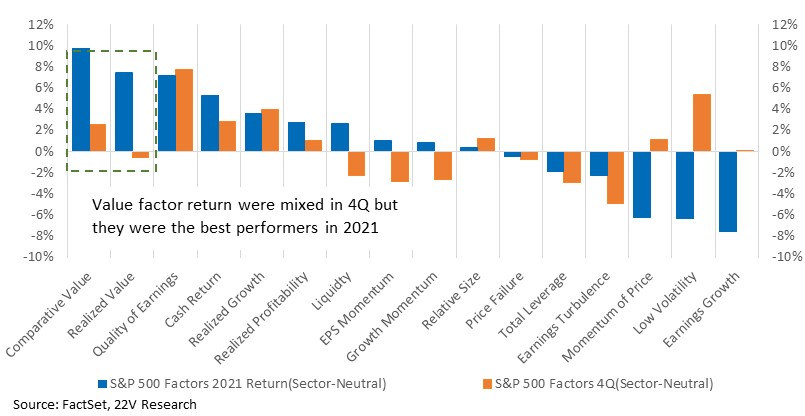
At the factor level, investors bid up high quality low volatility names in 4Q, but Comparative Value added to its gains as well, leaving it the best performing factor in 2021. Relative Value was the second best style factor last year, but all those gains were during the 1Q21 risk-on rally.
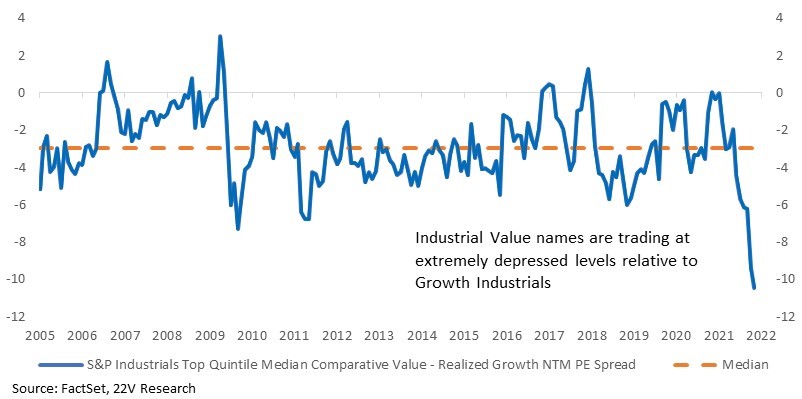
Even after leading factor returns last year, the NTM PE spread between Value and Growth is in the bottom 10th percentile of its historical range. Even if we assume a new distribution of Value vs. Growth PEs and narrow our period of comparison to the past five years, Comparative Value’s PE is in the bottom 20th percentile of is range relative to Growth.
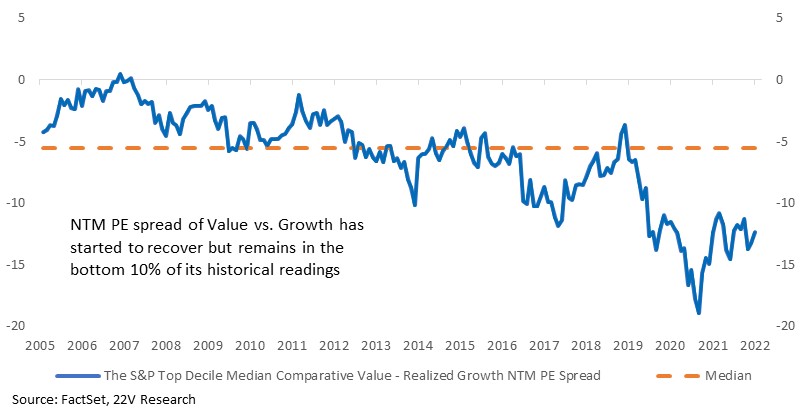
With Omicron uncertain clearing and negative sentiment toward supply chain issues easing, the headwinds holding back Industrials and Cyclical sectors are dissipating. High Value Industrial stocks’ NTM PEs have collapsed recently, particularly relative to higher Growth names. The improving backdrop for Industrials and Value makes this group particularly interesting. Some of these names, like Airlines, are also levered to Reopening. That trade continued to struggle, held back by travel disruptions related to Omicron.


