
Our entire repository of COVID charts is HERE.
The CDC cut the quarantine recommendation down to 5 days, if asymptomatic. That’s a good sign for labor disruptions. Healthcare too, since the CDC reduced separate isolation time for healthcare workers. Interpreting COVID data early this week will be difficult because of Christmas data disruptions. We have been focused on monitoring the UK. The official UK data website is still issuing warnings about incomplete holiday data. So, no use in highlighting the charts today. In the US, yesterday’s recorded case growth was over 500k, 200k+ higher than the previous worst day. That serves to illustrate we could use some clarity on the data before drawing conclusions. Vaccine, hospitalization, and mobility data are being affected as well.
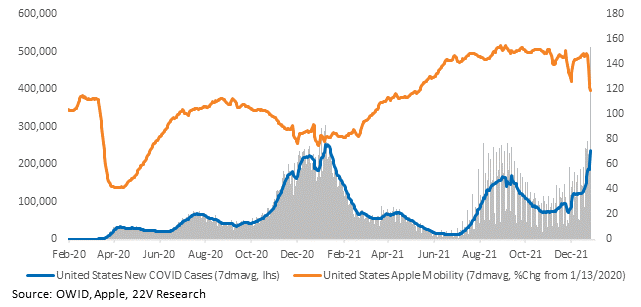
COVID news sentiment, measured with the Amenity natural language processing tool, rebounded last week. Sentiment about hospitalizations and deaths is particularly strong relative to sentiment about case growth. That is a reflection of a breadth of studies concluding Omicron is significantly less severe. As we have been writing, the worst case hospitalization scenarios are off the table.

That should lead to an improvement in investor sentiment, which, as we mentioned this morning, is lagging the breadth of economic data. Better sentiment would support Cyclicals (especially following a period of unusually severe Defensive outperformance). Better COVID sentiment is a tailwind for our Recovery portfolio and removes a significant headwind to 10yr yields.
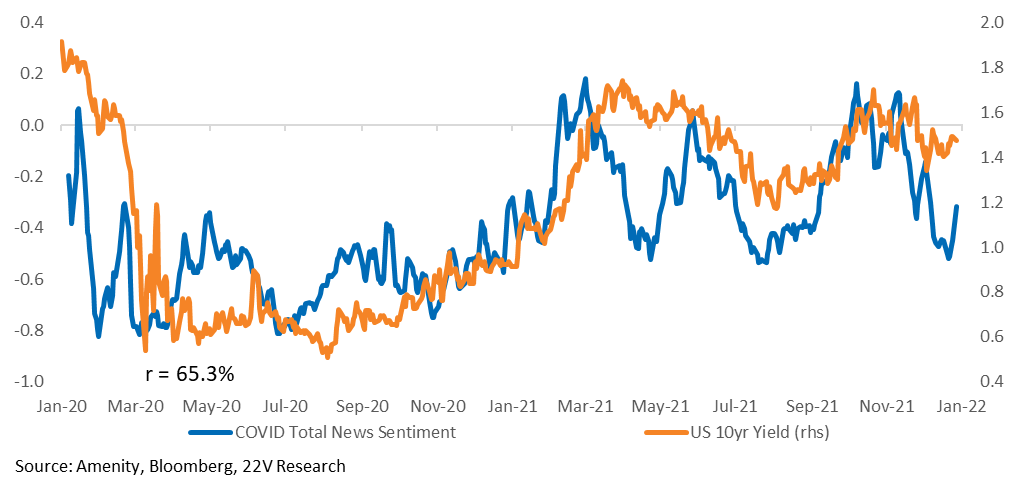
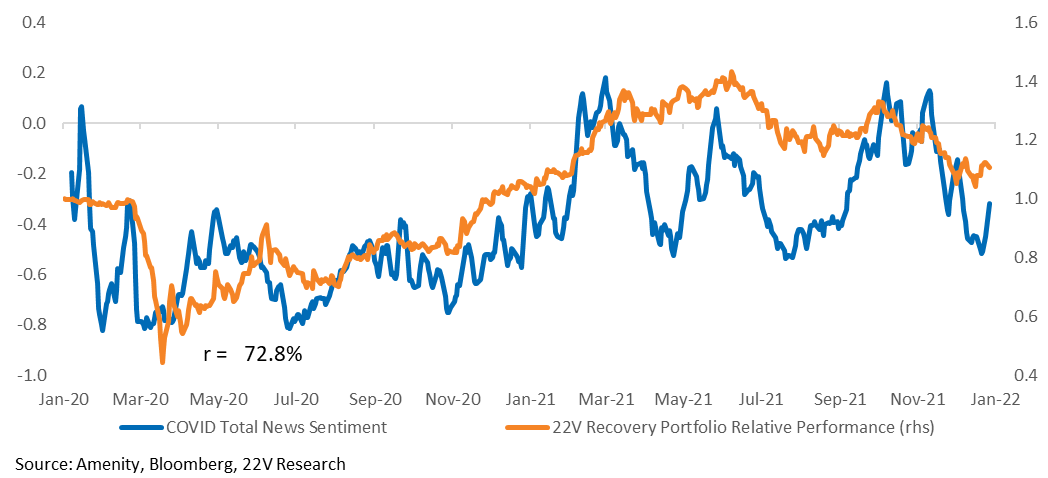
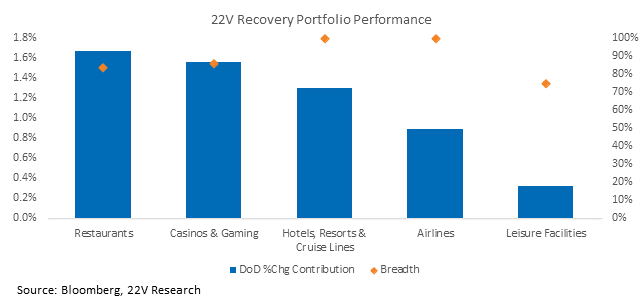
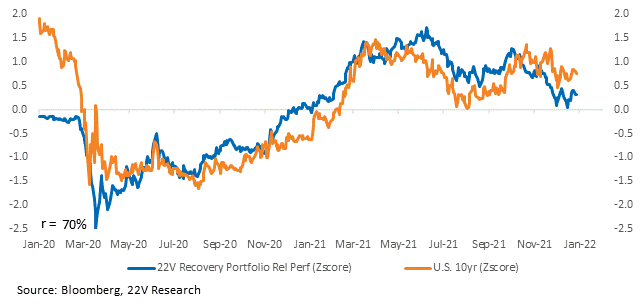
Our Recovery Portfolio has underperformed much of the past two months but has recovered some over the last two weeks. Restaurants and Casinos & Gaming have led the group higher. The breadth of constituents increasing is particularly strong. The portfolio’s performance has been moving lockstep with 10yr yields recently.
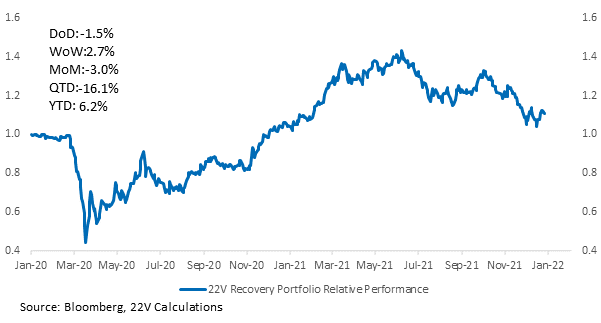
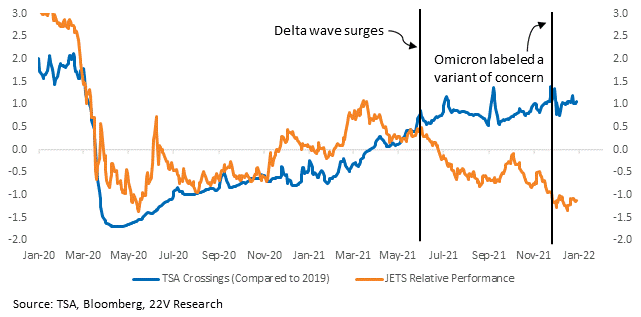
100% of airlines in our Recovery Portfolio have increased the last two weeks. JETS relative performance is still poor. TSA crossings are near a post-pandemic high, around -10% lower than in 2019. Airline demand is outpacing airline equity performance. International travel is still a headwind. Investors need to get more comfortable with travel restrictions and travel demand amid new variants, but as we highlighted above, COVID sentiment is improving.
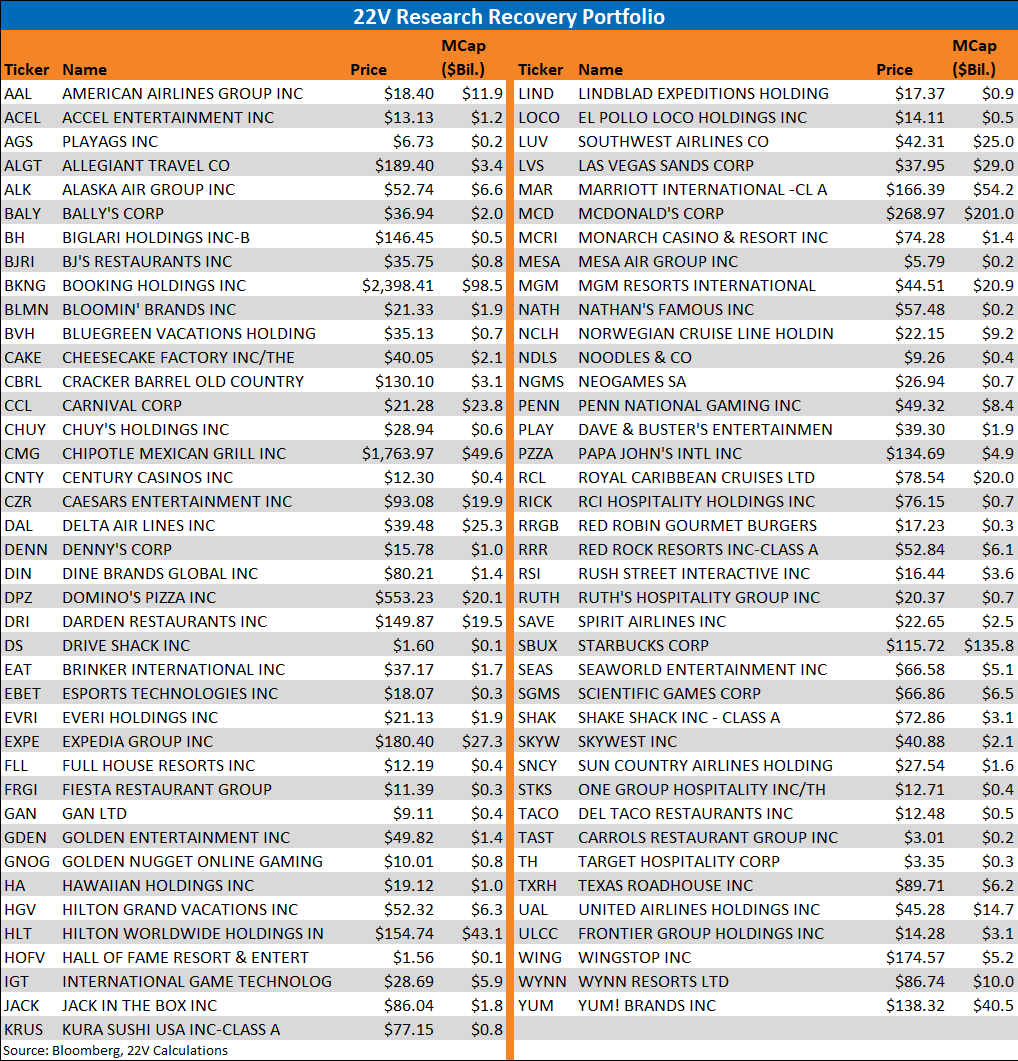
Constituents of our Recovery Portfolio are here.
Charts for every state and country we have data for are HERE.

