Today’s report is too short for a summary…. please take a look and have a happy New Year. Dennis, Brian, Kevin, and Sophia.
MARKET VIEWS: 2yr yields have climbed rapidly over the past month, posting 11 90th %tile or stronger gains in December. Despite the rapid climb in shorter-dated yields, the 10s-2s and 5s-2s curves have been flat. As we noted a few weeks ago, the worst of the yield curve flattening is likely over. As Omicron concerns fade, downward pressure on longer date yields will ease, paving the way for steeper curves in 1H22. An improvement in China’s economic outlook would likely support some short term upward pressure on yield curves as well. China’s service and manufacturing PMI came in better than expected overnight and Chinese media outlets and interviews with policymakers continue to indicate more stimulus is coming. China levered stocks (Industrials which have lagged come to mind) would benefit from an improved China outlook.

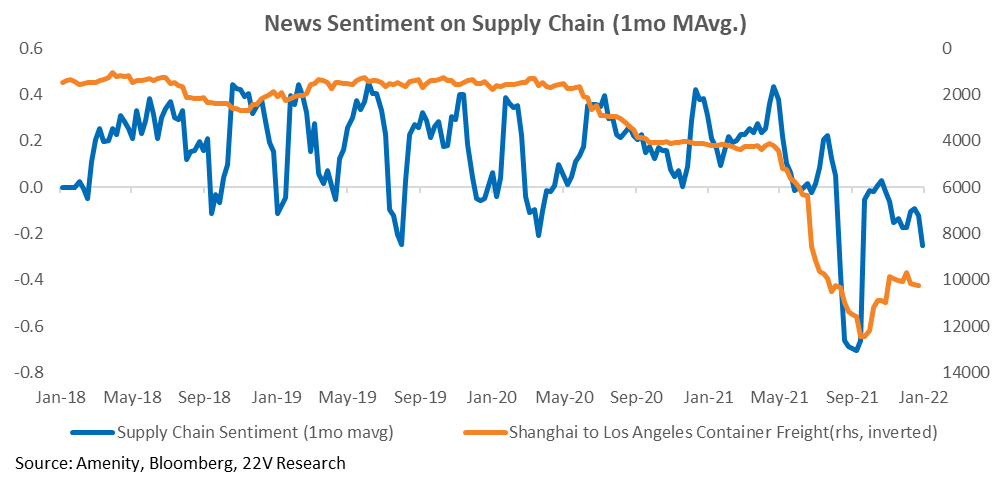
A near-term risk to the yield curve and China levered names is that supply chain sentiment is worsening again and China’s zero COVID policy is COULD be a major headwind. In addition to the news of China shutting down certain districts earlier this week, Cathay Pacific reported overnight it would suspend all long-haul cargo flights after quarantine rules were increased from 3 to 7 days. Supply chain concerns intensifying in January and goods inflation remaining elevated (most economist assume goods deflation will start to offset core inflation pressures starting now), concerns about sticky high inflation leading to demand destruction will increase again. It won’t be as intense as this past summer (other countries are keeping factories open and this wave of shutdowns is not happening right in front of the holiday), but it will be a narrative the bears latch onto.
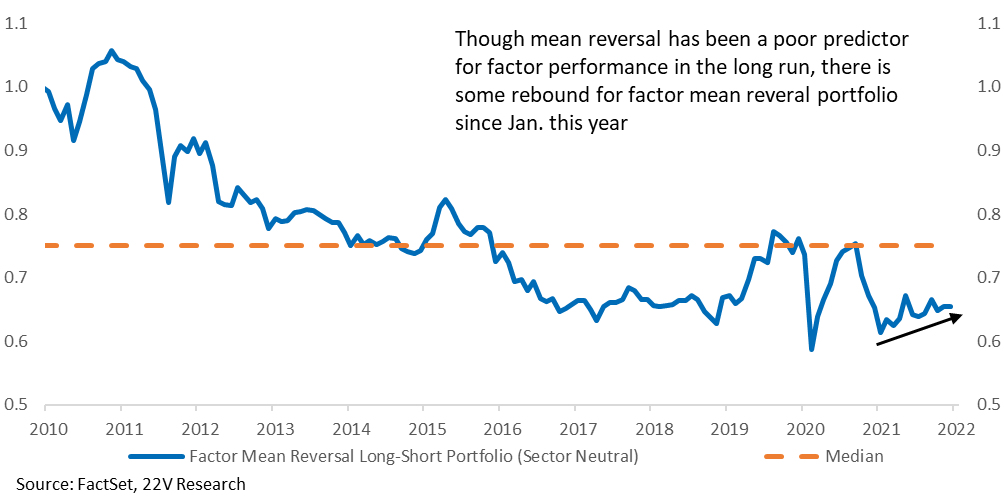
Factor Trends To End The Year: As we have noted, though factor returns have been more persistent than industry groups historically, our factor mean reversal portfolio has posted strong gains over the past few quarters, but the performance lagged significantly relative to stock picking mean reversion and Industry group mean reversion strategies.
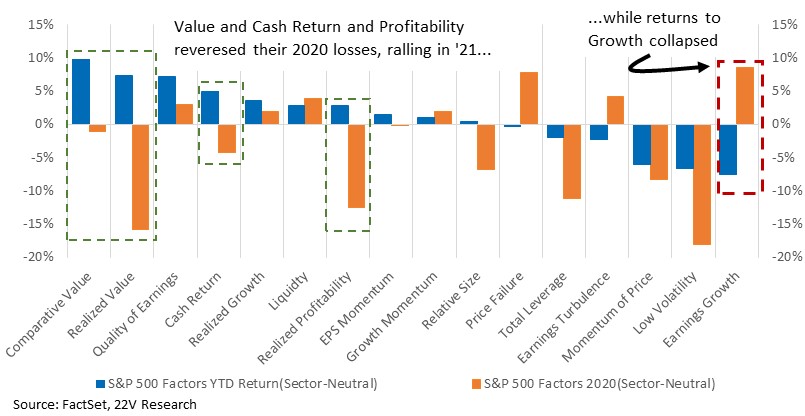
A growing mean reversal trend does not mean there were not factor winners and losers in 2021. Value factors have been the best performers, followed by Quality and Cash Return. Growth, Low Vol, and high Momentum names were the worst performers. Some of those represent a significant shift from 2020 where Growth and Price Failure were the best factors and Realized Value and Cash Return fell sharply.
Quarter to quarter return volatility was high in 2021. Realized Value was the second-best performing factor, but ALL of its gains came in 1Q. Realized Growth was the 4th best factor, but fell sharply in 1Q and rose in 3-4Q. Comparative Value, the best factor, posted consistent gains. There are two important points about those returns; 1) there was a meaningful shift in growth expectations in 1Q and 2) identifying the market regime is key to factor positioning.
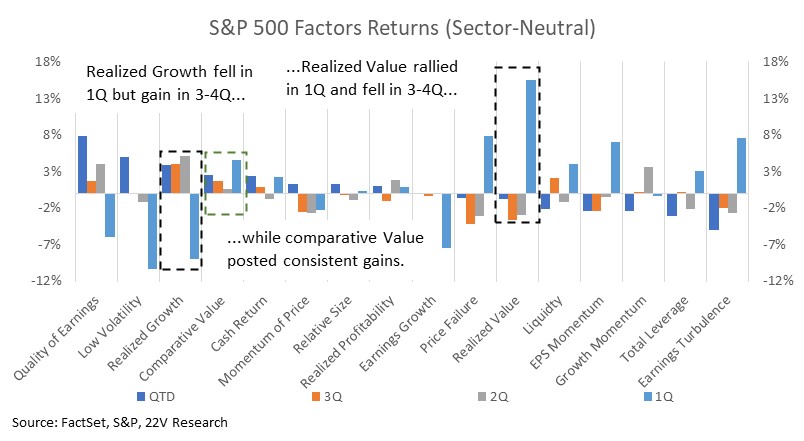
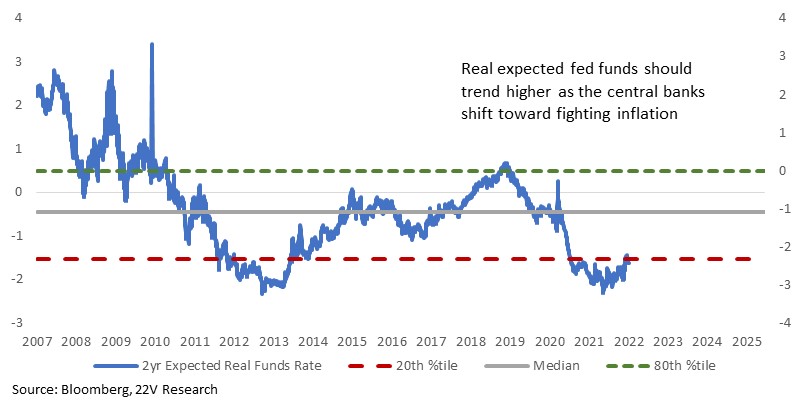
As an example on regimes, Value and Growth had major swings depending on the “regime” people thought we were in. The fiscal stimulus + Fed never raising rates trade helped Value. The summer stagflation fear helped growth. Reopening, Cyclicals and Growth worked in the Fall when inflation expectations surged (that is when people realized a demand shock was a major reason for supply problems) and momentum, low vol and earnings turbulence got crushed to end the year once the Fed pivot was internalized (higher real short rates). The market regime will still exert an influence of the types of factors that tend to work. As we have noted before, one clear trend is the upward bias to expected real rates as the fed and other global central banks shift from pursuing to fighting inflation. On the short term narrative, we think reopening will dominate in January, but supply concerns could offset that. We remain long XLE vs XLU, QQQ vs XLP, Banks generally and reopening.