Back Shoot Around

22V Afternoon Shoot Around: 10yr, SPCX, and an AAPL Hedge Idea

Published on July 8, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: 10yr and Fundamental Factors

The 10yr yield is back above 4.5%, the level at which factors become more sensitive to movements in yields. We suspect the 4.5% level may shift higher over time as the market discounts a higher neutral rate (the rate that is neither stimulative nor restrictive to economic growth), but it’s holding for now. Hedging remains in focus. Over the medium term, the case for fundamental factor leadership remains intact because a higher neutral rate + a mild degree of restrictiveness doesn’t change the economic backdrop. If yields were only increasing because of more restrictive policy, it would be a scene changer, and risk-off factors and Defensive sectors would be more attractive.

Relevant News: Momentum Factors

Momentum factors, including both EPS and Price Momentum, have surged since last September, with Price Mo accelerating this year (HERE) until the past few weeks. Price Mo has struggled as winners in AI and Semis have pulled back, leaving a -17.4% drawdown for the unconstrained Price Mo basket. In contrast, EPS Momentum remains resilient and slipped just -1.8% from its peak.

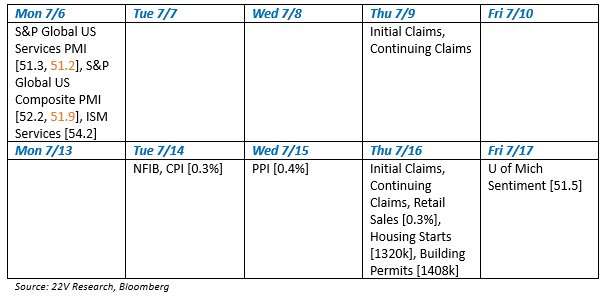
Things to Watch [Consensus, Results]:
A white table with blue text

AI-generated content may be incorrect.

Strategy:

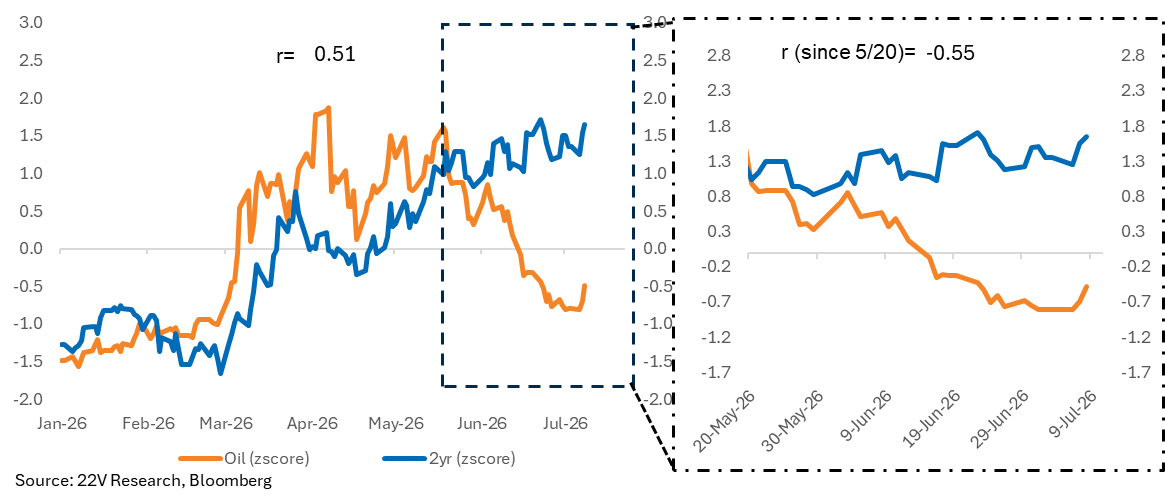
Iran Risks Adding to Existing Upward Pressure on Treasury Yields – (HERE)

Peter Williams estimates 10yr fair value is moving toward 4.5% (from 4.5% being the high end of the range). This estimate is based on the rebound of demand indicators, not Iran. How internals react to the 10yr depends on the reasons for the move. Peter raised his estimated based on a higher neutral rate + a mild degree of restrictiveness. Yields had diverged from oil as nominal demand seems to have bounced.
A graph of a graph of a graph

AI-generated content may be incorrect.

Data Infrastructure/ Commodities:

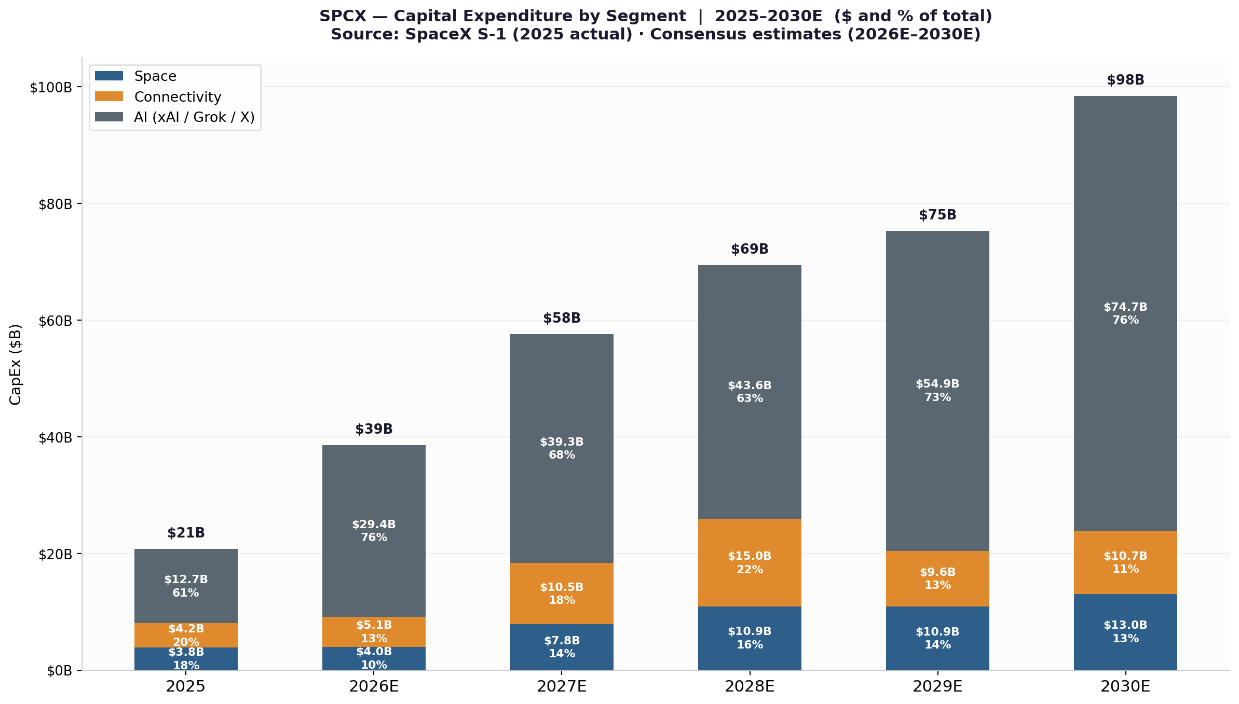
SPCX: A Post-IPO Update; Navigating a Catalyst-Rich Road to 2027– (HERE)

SPCX remains one of Dauvin Peterson, 22V’s Data Infrastructure/ Commodities anlaysts, preferred ways to gain exposure to both the emerging space economy and AI infrastructure, with the stock entering a catalyst-rich second half of 2026 after the IPO, Nasdaq inclusion, and initial analyst coverage. Near-term trading is likely to be driven by lockup expirations, Nasdaq rebalances, and the company’s first public earnings reports, creating volatility and position-building opportunities. Beyond these technical factors, investors should focus on key catalysts including Starship 3 testing, AI compute commercialization, Starlink metrics, potential Terafab developments, and the durability of major compute contracts, while monitoring the August Clean Air Act litigation tied to Colossus 2. Despite expected volatility, we continue to view SPCX as well positioned heading into 2027–28, with multiple long-term growth drivers still in their early stages.
A graph of a number of columns

AI-generated content may be incorrect.Source: Bloomberg, SPCX S-1

Derivatives:

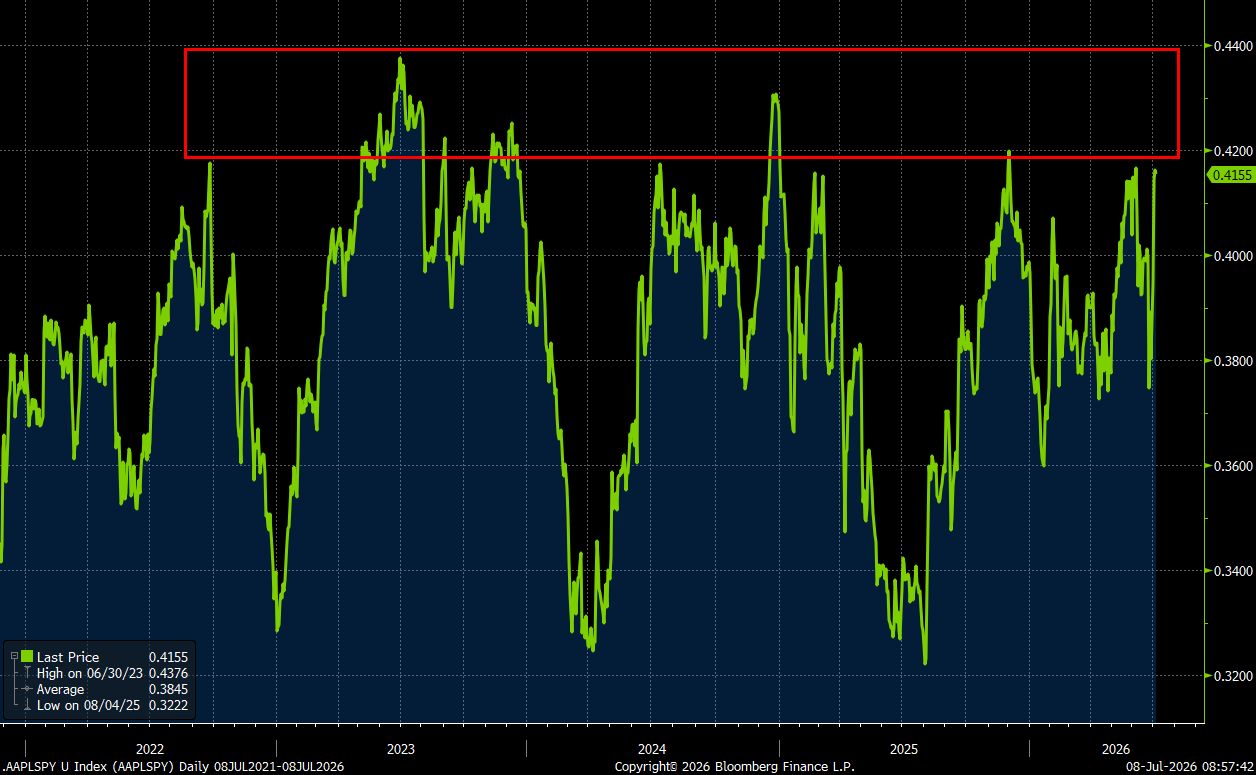
Great Time to Hedge Apple (AAPL) if it’s a “Core” Holding – (HERE)

After AAPL’s 15% rally from its June 25 lows back to prior highs, 22V’s Jeff Jacobson sees an attractive opportunity to add downside hedges. The setup is supported by a negative RSI divergence, implied volatility trading at a steep discount to realized volatility, a valuation near record P/E multiples, and AAPL trading at the top of its five-year relative range versus the S&P 500. With earnings on July 30 serving as a potential catalyst, Jeff favors owning August put spreads targeting a pullback toward the 200-day moving average, offering an attractive risk/reward profile for hedging existing long positions or expressing a limited-risk bearish view.
A graph with green lines

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.