DAILY STRATEGY: Main Point – Upcoming CPI and PPI data will shape expectations for Core PCE inflation. Current Core PCE is at a level that increases the odds of a transition from a normal expansion toward a more volatile economic and market regime — historically associated with a VIX above 20, tighter financial conditions, and headwinds for risk-on factors that have performed well year-to-date. Federal Reserve speakers have shifted dramatically toward viewing inflation as their principal concern, with monetary policy sentiment turning relatively hawkish.
The key wildcard is the Strait of Hormuz supply shock, which appears to be the primary driver of inflation sentiment and 10-year yields — if it resolves, 10yr yields should decline and the risk of moving into a more volatile economic and market regime would be reduced. In short, it is very difficult to have strong economic and labor market growth + a supply shock and not have significant upside inflation risk. That is the bad news. The good news, the main driver of inflation risk is the supply shock, which can go away over time. If that happens, riskier factors will benefit. We continue to favor Retail, Banks, and Airlines for a “catch-up”. We like Price Momentum longer term (HERE). If the main driver of inflation was labor market tightness, the markets and economy would have a much larger headwind. Thankfully that is not the case (HERE).
Charts and Commentary…
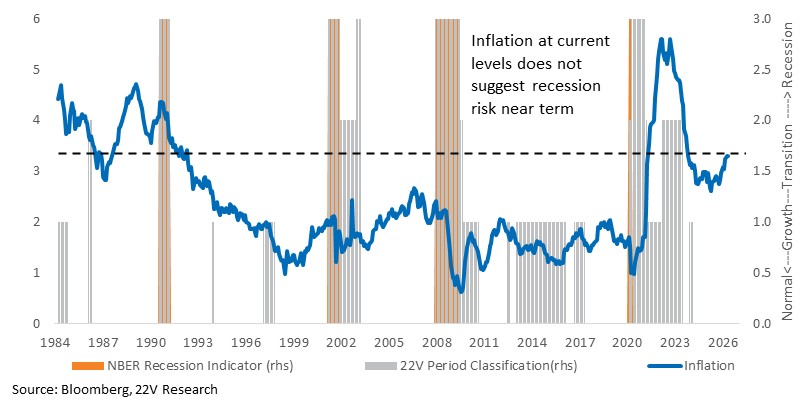
Core PCE inflation readings at their current level do not suggest increased near-term recession risk (good news) but does increase the odds that financial conditions tighten and that the economy moves into a transitionary regime. From a Normal Economic expansion. Transitionary economic regimes, which is the regime between normal economic expansion and recession, tend to be associated with a median VIX level above 20 and higher than normal correlations. The Risk-on factors that have worked YTD tend to suffer in a transitionary economic regime.
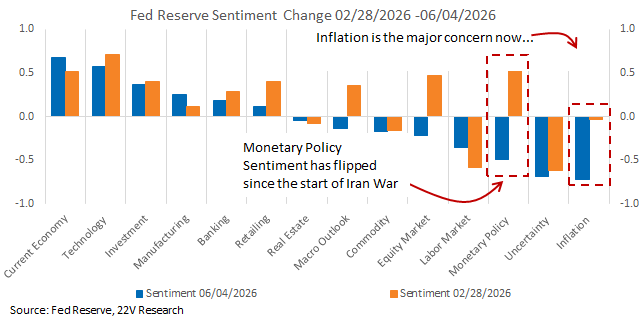
Related to the above and as pointed out in the Quant report yesterday (HERE), across all 14 economic categories, Fed speakers now treat inflation as their principal concern. At the onset of the Iran War (2/28), Inflation sentiment was mildly negative; today it is the most negative category, marking a dramatic deterioration since the start of the war. Alongside this drawdown, Monetary Policy sentiment has flipped from firmly positive to one of the most negative categories. As a reminder, we define positive Monetary Policy sentiment as dovish and negative as hawkish, so this shift signals a decidedly more hawkish stance.
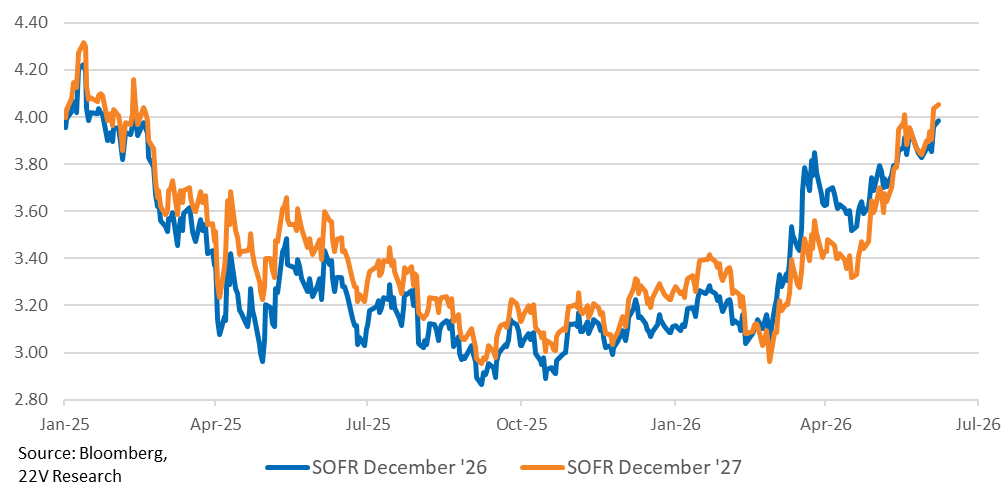
The bias for the fed funds rate is for a hike over the next two years.
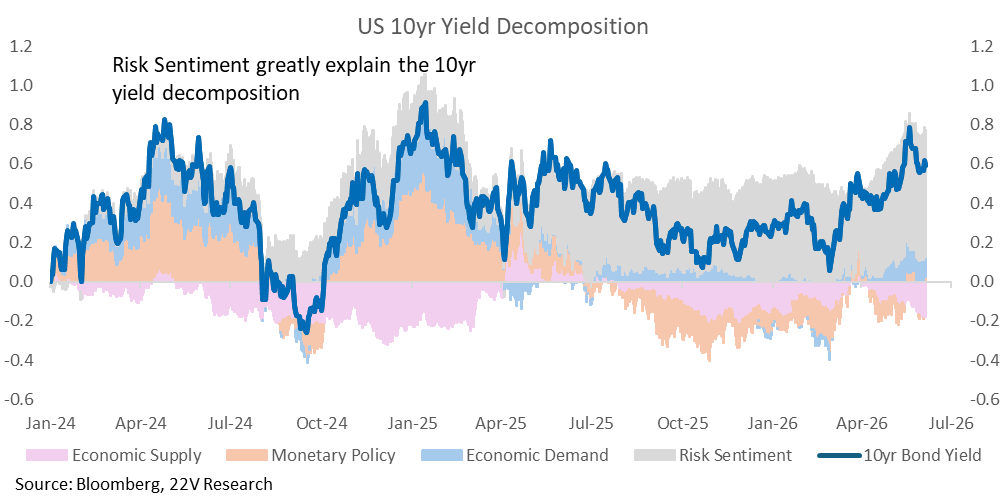
Our current 10-year yield decomposition shows that risk sentiment is the predominant factor explaining the 10-year yield’s return. This indicates that higher inflation and the heightened risk-management it creates is the key driver of the yield level, not Fed Monetary Policy sentiment. The implication is that, even though Fed Monetary Policy sentiment has flipped in recent readings, changes in inflation sentiment are likely to exert greater influence on 10-year yields. If inflation sentiment is MOSTLY being driven by the Strait of Hormuz supply constraint, which seems likely, reopening the SOH would ease inflation concerns and 10yr yields would decline.
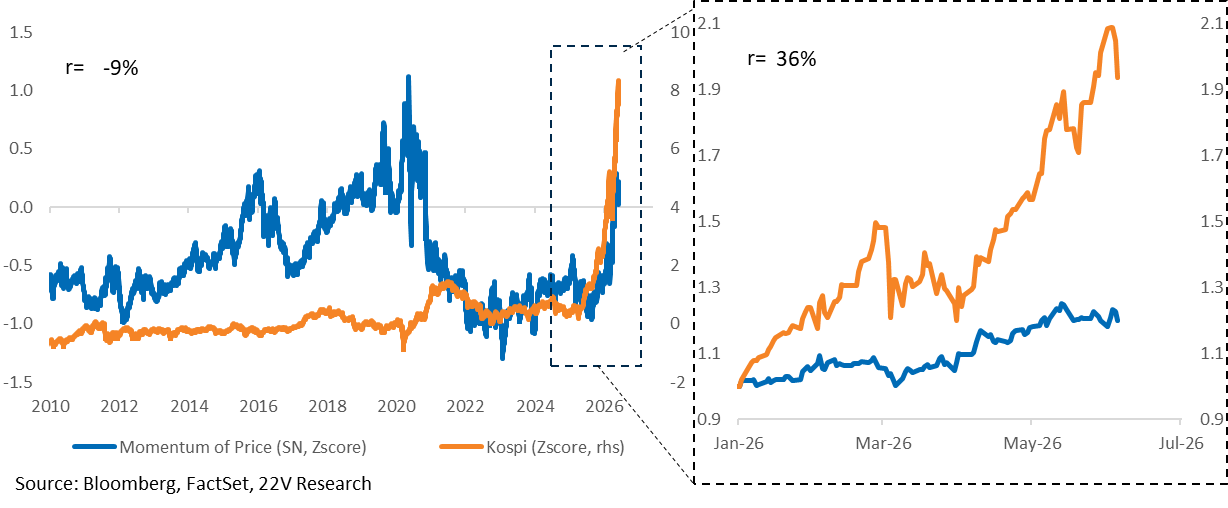
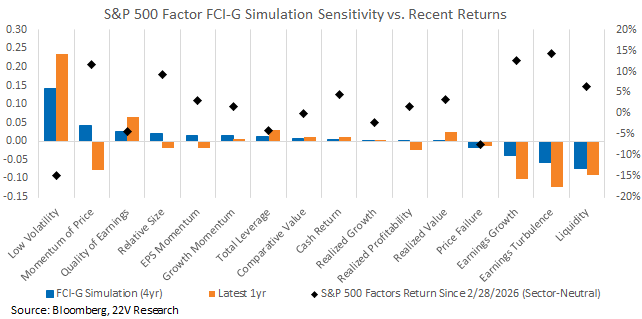
We are on the edge of financial conditions needing to tighten. If inflation were to remain at the current 0.3% MoM core readings through year-end 2026, tighter financial conditions would be priced and Low Volatility and Quality of Earnings would continue outperforming. Like they did Last Friday. While Risk-on and Earnings Growth, which are performing well, would face downside risk. Momentum and Size factors used to have positive sensitivity to financial conditions. AI idio risk weighed more on their YTD returns, which may be less driven by financial conditions now.
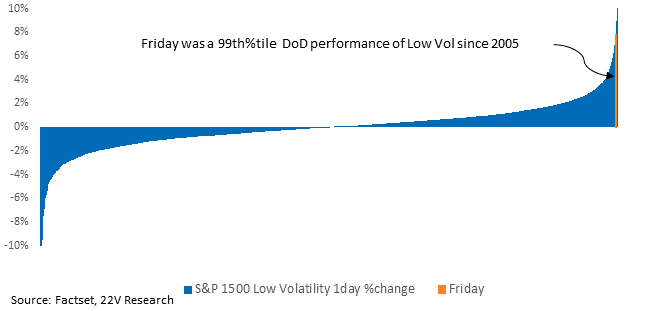
Friday was the 19th best day for S&P 1500 unconstrained Low Vol since 2005 (our sample size).
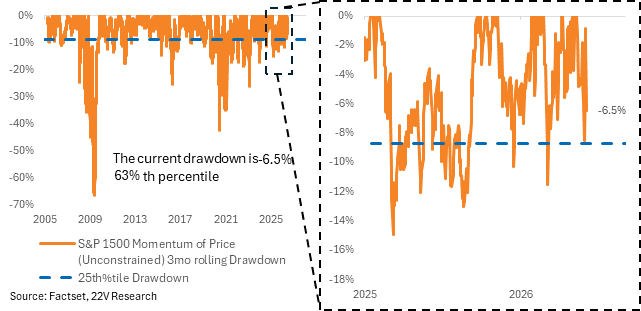
The drawdown in price momentum was a 63rd percentile drawdown. Smaller than summer of 2024, Liberation Day, and the Iran conflict.
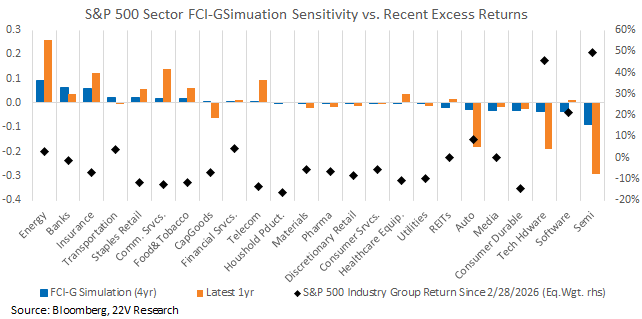
Semis and Tech Hardware are the best performing industry groups this year on the massive AI buildout. Those groups have negative sensitivity to financial conditions. If core inflation prints 0.3% or higher, Semis and Tech Hardware would face headwinds while Energy, Banks and Insurance are more likely to benefit.
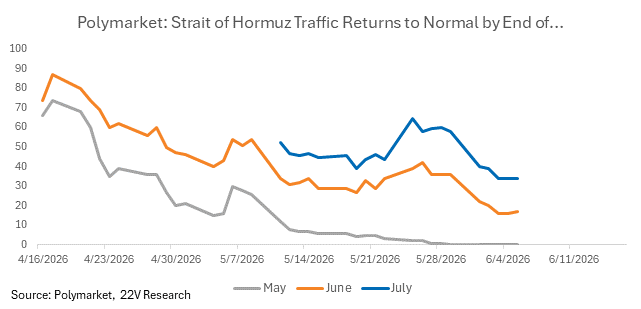
The problem is the Strait of Hormuz (SOH) supply shock keeps getting rolled forward. We are tracking Polymarket odds for SOH traffic “returning to normal.” Odds of traffic returning to normal by the end of July are 30%. “Return to normal” is a high bar, but there are not more precise contracts. SOME relief is needed in the SOH for non-AI cyclicals to benefit from economic strength.