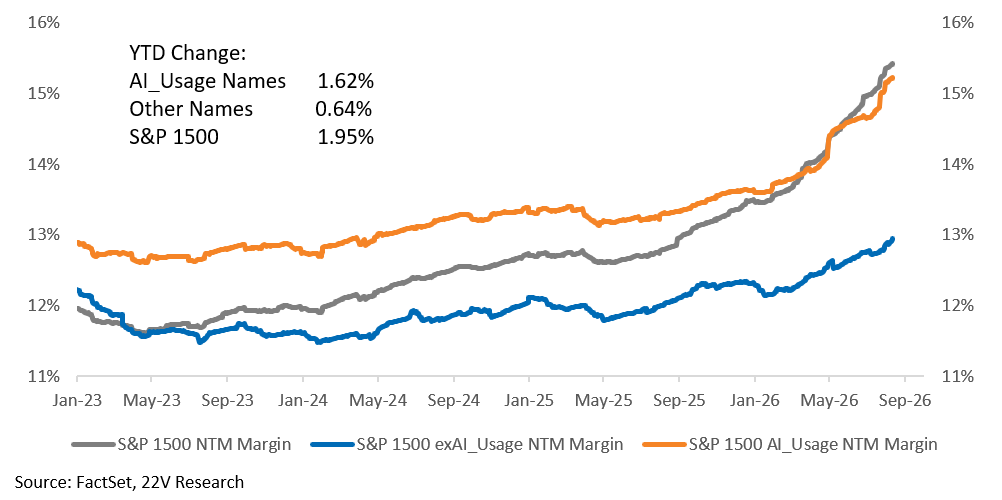
DAILY STRATEGY: Main Points – 1) the direction of travel after the payroll and CPI/PPI data is continued easy financial conditions and risk asset supports. 2) Through 2QEPS seasons, NTM margin estimates for AI Users (companies with specified AI use cases) continued to outpace non-AI Users, both in level terms and rate of change. Margins remain biased higher.
Marking To Market Post Payroll & CPI/PPI – The right tail for equities has increased. REALTIVELY benign labor market and inflation data suggest financial conditions can remain easy in the coming months and potentially much longer. Continued easy financial conditions, along with a firm fundamental backdrop supports risk assets.
EPS growth remains strong, and confidence in the durability of AI demand continues to rise. Stronger AI demand also increases the probability that hyperscalers can generate attractive returns on their AI investments, supporting continued capex spending.
Against this backdrop, we continue to favor both AI goods and AI services. We remain constructive on non-AI cyclicals, particularly Retail, Banks, and Transports. We are long Cyclicals in aggregate and short Defensives, Low Earnings Vol names and other “risk of” factors.
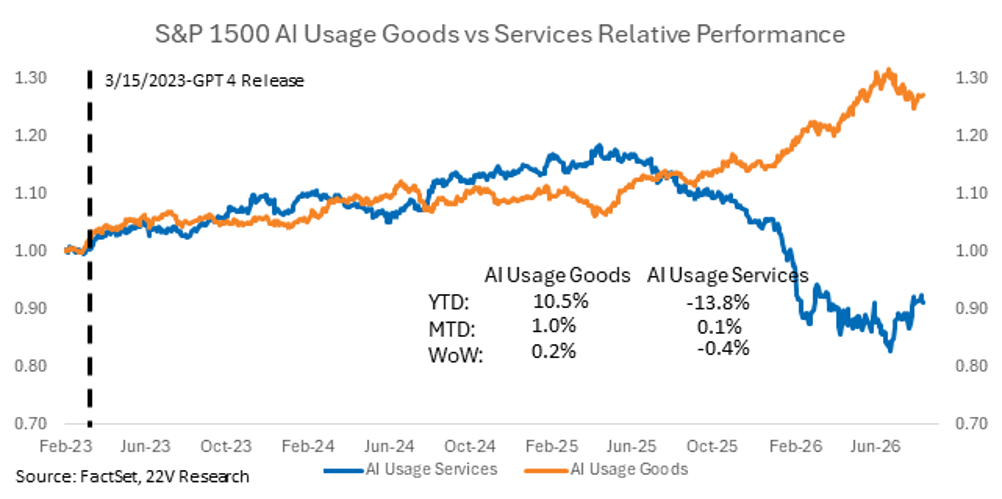
FYI – On July 31st we made the call that both AI service stocks and AI goods baskets (think Semis, AI power, etc.,) could work together (HERE). They have had a deeply negative correlation since October 25th and we expect that to change. Both baskets are positive month to date.
WEEKLY AI Update: Simple update today. We are focused on how effectively AI is improving profitability, across companies, because that determines the direction of travel of the various cutups of the AI Users AND buildout beneficiaries. The more signs AI is improving profitability across multiple different types of businesses the better it is for users and buildout beneficiaries. The main point of the below is that the early indications are still that AI improves margins.
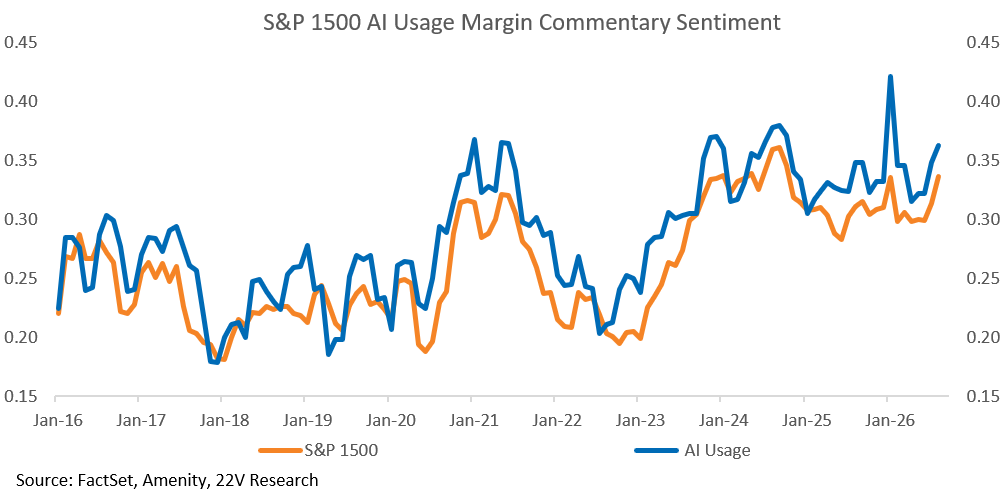
Through most of 2Q, the NTM margin estimates for companies that have specified use cases of AI (AI Users) continued to outpace non-AI Users, both in level terms and rate of change. The sentiment expressed by the management teams of AI Users about the forward outlook for their company’s margins is also better than non-AI Users.
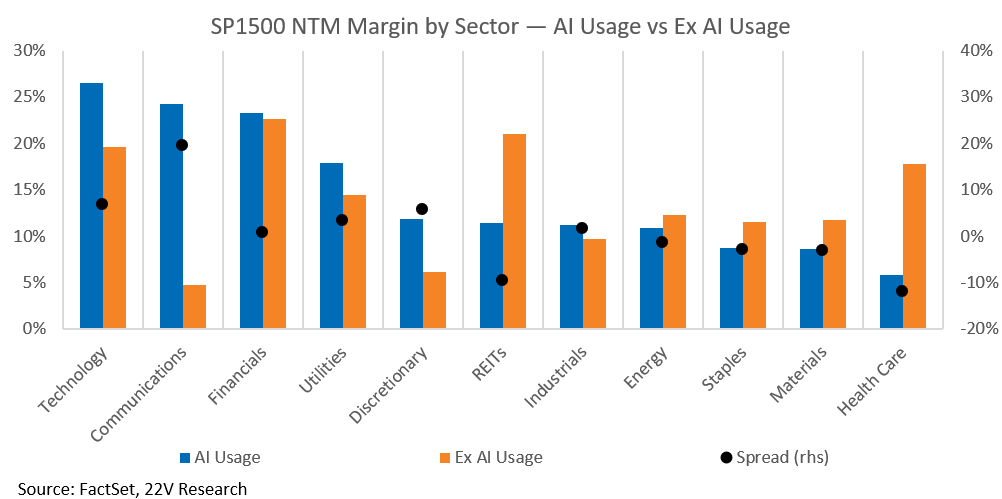
The margin advantage is highest in Tech and Communication Services, but not exclusive to it. AI users also have higher margin estimates within Financials, Utilities, Discretionary, and Industrials. AI Usage is not yet an advantage aggregated across REITs, Energy, Staples, Materials, or Health Care. There are idiosyncratic examples in which this is wrong, like a specific Health Care company using AI vs not. We are painting with a broad brush because breadth of margin improvement is an important consideration to the demand for AI.
FYI, our work with the AI Users that have quantified the expected impact from AI showed that AI usage is highest in asset light companies. Asset light companies have the largest weights in the S&P, which is helpful from an index valuation perspective (see a lot more HERE), but the broadening out of margin improvement from AI remains a watchpoint. This is second in importance to the good news from aggregated margin estimates and sentiment.
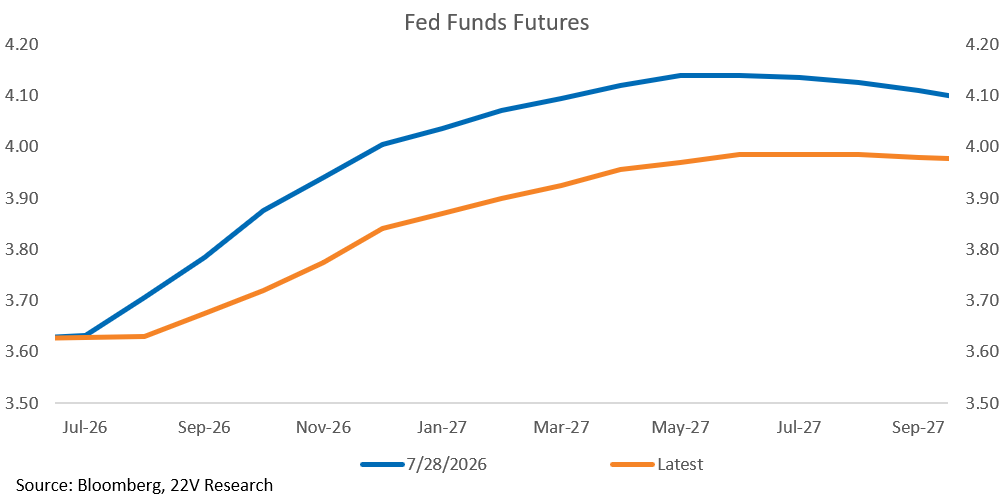
Charts – Fed rate hike expectations have moved meaningfully lower over the past few weeks. More benign than expected labor and inflation data is the main reason. That is a support for risk assets all things equal.
Following the CPI/PPI data, PCE measures are expected to hook down. As Gerard shows in the charts below. The Core PCE estimate, ex financial service prices (as we noted yesterday, financial services prices are being revised in Sept, so everyone removes them now) was only 10bp. The 3-month annualized rate is 2.06 on that measure. Net net, the odds that the cycle is more durable have increased over the past few weeks. That is risk assets positive (HERE).
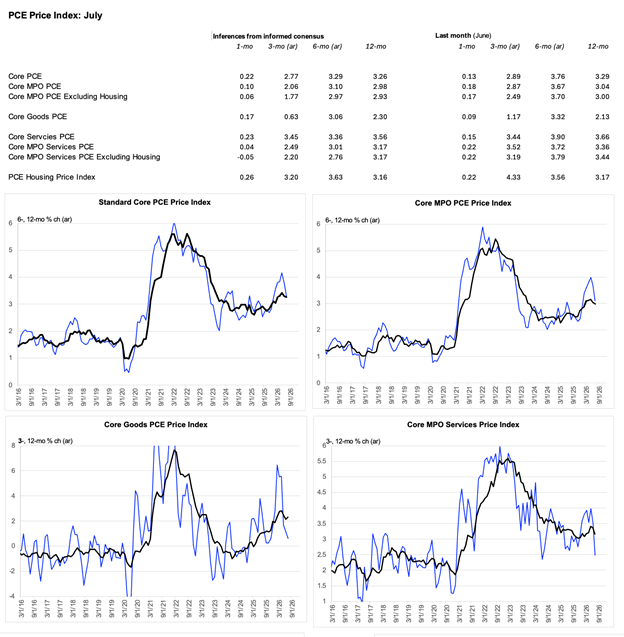
Source: BEA, FH inferences from informed consensus. Data are actual to June and estimates for July.
On July 31st we made the call that both AI service stocks and AI goods baskets (think Semis, AI power, etc.,) could work together (HERE). They have had a deeply negative correlation since October 25th. Both are up MTD (July 31 fwd).
WEEKLY AI CHARTS – FYI, see our 2Q list of AI Users (so far) HERE. Margins go high.