Bottom Line: Non-AI Cyclicals
<4.5% on 10yr yields should support non-AI Cyclicals. Along with all Cyclicals and Fundamental factors. Unfortunately, the SOH resolution catalyst keeps being pushed back. Polymarket odds of traffic “returning to normal” by end of June are down to 15%. The potential asymmetric returns for non-AI related Cyclicals if there is a SOH resolution remains interesting. But the situation is volatile and it’s an open question if a resolution can be reached without significant demand destruction first. i.e. oil prices increase to $120+ before something gives in the negotiations. We have been recommending options to hedge against event risk when volatility cheapens (HERE).
Relevant News: May Employment Report
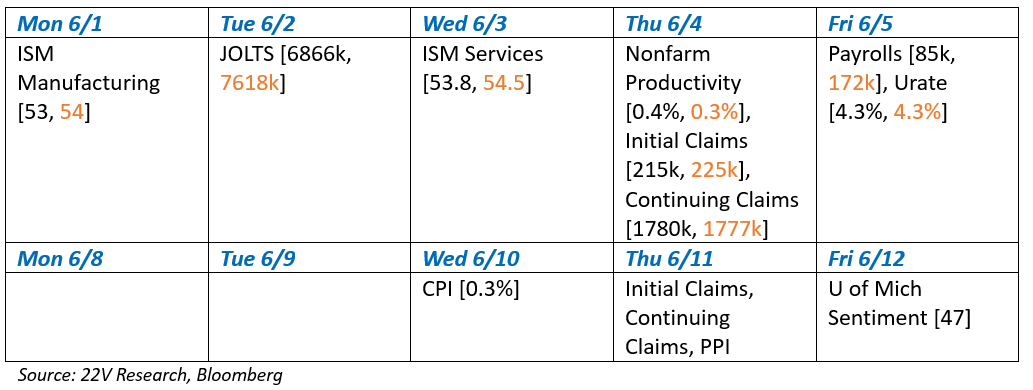
Nonfarm payrolls came in well above consensus at +172k with large positive revisions to the prior two months as well. After averaging only 11k in 2025, NFP growth has clearly reaccelerated in 2026 (the 3mma of +188k is eyepopping). Measures of slack and wage growth do not point to strong retightening concerns yet. This is a bit of a puzzle given how much NFP growth has reaccelerated but it may simply be a matter of time. The data is moving against views that labor market softening would swamp other inflationary impulses and allow or force cuts. The question is if inflationary backdrop might require that. As the war and tariff inflationary impulses add upside risks and deanchoring concerns. Even without them, the labor market seems steady to improving, growth solid, and inflation appreciably above target. That sounds like an economy at neutral, or maybe a bit below it.
Things to Watch [Consensus, Results]:
Strategy:
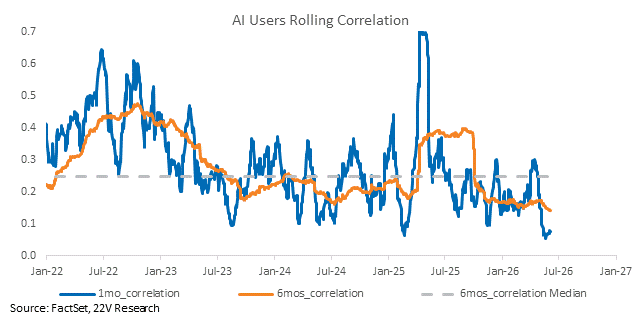
Stock Picking is Now More Effective in AI Baskets – (HERE)
AI baskets as a whole are less obvious longs while some constituents work and some don’t, favoring a rotation. Non-AI Cyclical laggards – Banks, Retail – could benefit longer-term given the economic backdrop (HERE), though short-term volatility is still dependent on the Strait of Hormuz, and now some financial conditions tightening after this morning’s hawkish jobs report. Today’s jobs report doesn’t change the longer-term outlook for financial conditions. That would take more evidence that the labor market is inflationary. The urate is still above the Fed’s estimate of the non-accelerating inflation rate of unemployment (4.2%), and wage growth remains in its downward trend. The 10yr above 4.5% is a headwind for non-AI cyclicals for now, but the supportive backdrop is intact longer-term.
China
The View from Washington– (HERE)
Following a closed-door Washington conference convening leading China experts and policy community members, the key takeaway is that while US-China relations have improved following Trump’s visit and Xi’s planned September trip to the US, structural mistrust and strategic competition remain persistent undercurrents. On AI, both sides hold distinct advantages across the tech stack but have begun a dialogue on safety guardrails, though China’s ability to deploy cost-effective models raises questions about the durability of the US lead. China’s economic outlook remains constrained by weak domestic demand, overcapacity, and structural distortions, while Taiwan conflict risks are seen as low near-term but bear watching into the 2028 presidential election, and Xi Jinping is widely expected to pursue a fourth term with no meaningful political obstacles in sight.
Data Infrastructure/ Commodities:
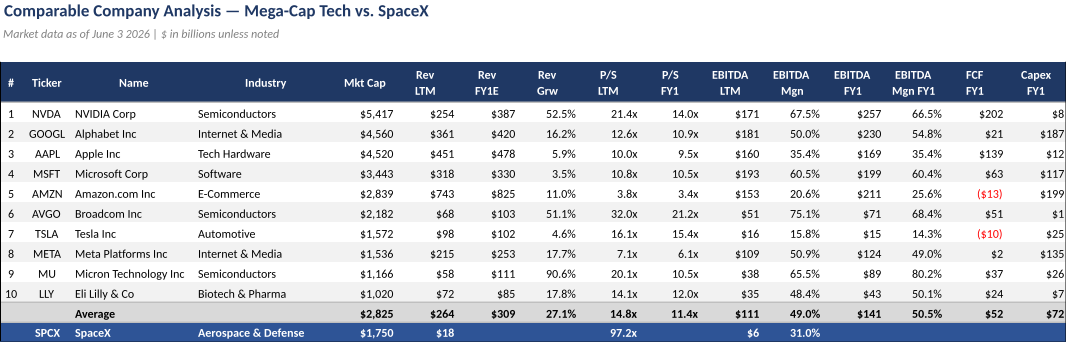
The SpaceX IPO — A Catalyst-Rich AI and Space Story– (HERE)
SpaceX (SPCX) is set to begin trading June 12th as the largest IPO in history, instantly joining the $1T+ market cap club with a catalyst-rich story spanning commercial space, orbital data centers, AI infrastructure, and the pending Cursor acquisition. While the headline IPO multiple of 90x sales looks steep based on 2025 revenue, a more current view incorporating the Anthropic compute deal and Cursor option brings that closer to 40x, which feels more reasonable given the growth trajectory toward a potential $45B revenue run rate by year-end. Near-term catalysts including Nasdaq index inclusion in early July, the Cursor acquisition, continued Starship testing, and the Anthropic/Colossus expansion should support the stock, though the path will be volatile and long-term value creation ultimately hinges on successfully scaling commercial space launches and building a defensible AI infrastructure business.