Back Portfolio Strategy

AI Beneficiaries Correcting as the Price Momentum Factor Corrects

Published on June 2, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Kevin Brocks

Sophia Wang

DAILY STRATEGY: Our call is for the 10yr yield to grind sideways in a 4.2-4.5% range (HERE). That implies some downside skew from current levels. A continued economic expansion with 10yr yields in the 4.2-4.5% range favors fundamental factors (Earnings momentum, GARP, Growth, Value), Cyclicals, and AI Capex beneficiaries. Some AI beneficiaries are correcting now as the Price Momentum factor corrects.

FYI – We would look to add to the AI capex beneficiary baskets AFTER the volatility of the Price Momentum declines (HERE). High single-stock implied volatility (99th percentile) and accelerated turnover rates in the price mo factor suggest a heavy influence from retail “swarming” and momentum chasing. Some of the “chasing” in momentum stocks is unwinding now as 10yr yields decline. Recall that the Price Mo factor tends to do well when 10yr yields move above 4.5% (HERE). Economic growth expectations decline when 10yr yields move above 4.5% (demand destruction odds increase). Price Momentum stocks are considered less economically cyclical. They benefit as weaker economic growth is priced.

We favor Retail, Banks and Airlines now. They would benefit as/if 10yr yields grind lower and the economic expansion continues at the roughly 2% real GDP pace. These industry groups have lagged significantly.

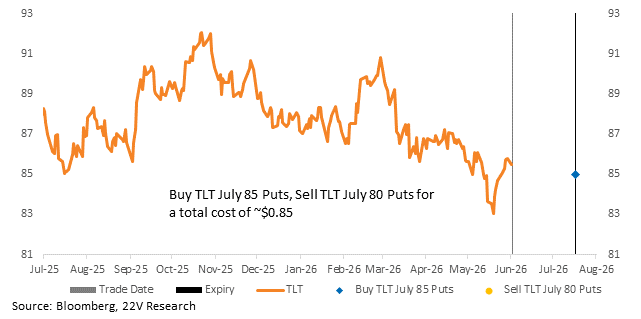
Event risk is not behind us though. That is why we want to take advantage of implied volatility cheapening to hedge against yields spiking higher via options. Jeff Jacobson, 22V Derivatives specialist, likes hedging the TLT when implied volatility drops below realized volatility, as is the case now. From Jeff, “the last time the 2-month, 40 delta implied volatility traded at this much of a discount to the 2-month realized volatility was in mid-April. Shortly after, the TLT dropped -5% over the following month.”

Trade: Buy TLT July 17th 85/80 put spread for $0.85 (85.47 ref).

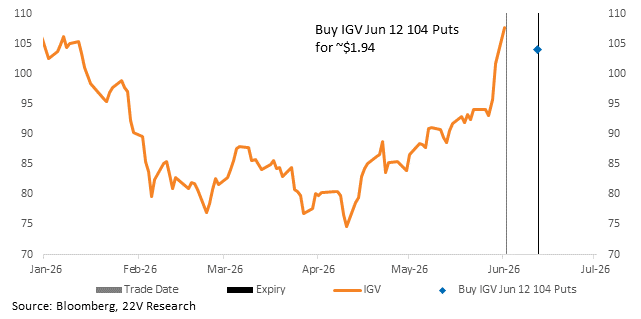
The logic of hedging volatile markets when implied vol drops applies to Software too. We have been long software since the beginning of earnings season (full details HERE). However, IGV has now increased +16% in three days. PANW, CRWD, and ORCL – which are 24% of the IGV – report in the next week and a half, a potential catalyst for volatility. We don’t like shorting Software, but hedges make sense here.

Jeff likes June 12th 104 puts for $1.94 (107.60 ref).

Charts…

Implied volatility is below realized volatility for the TLT. This year, that has been a good opportunity to buy puts. Longer term, yield vol will decline, but short-term, it is still a function of geopolitics.
The IGV has rallied +45% since mid-April and +16% in 3 days. We do not want to short Software, but hedging is appropriate.
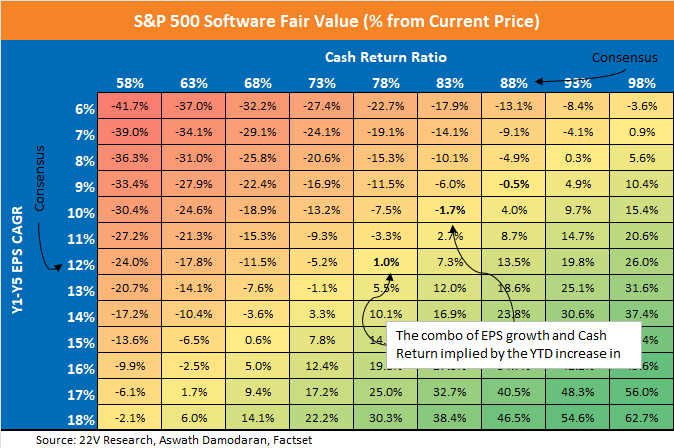
The move in Software (ex Hyperscaler) valuations now discounts a lower but still significant, decline in earnings estimates or cash return. On their own, valuations imply the 5y forward EPS CAGR falling from 12% to 9% (or 2y forward EPS CAGR falling from 19% to 13%), or Cash Return falling from 88% to 77%. Together, something like an ~83% cash return ratio and an EPS CAGR of 10%. In 1Q, earnings estimates increased, and cash return remained stable. One quarter in, there is little evidence of the downside developing in aggregate. There will be relative losers, but some winners as well.

The below matrix shows Fair Value (% from current price) of different combinations of cash return and earnings, assuming that the equity risk premium was moving ahead of earnings and cash return estimates.
A colorful chart with numbers and numbers

AI-generated content may be incorrect.

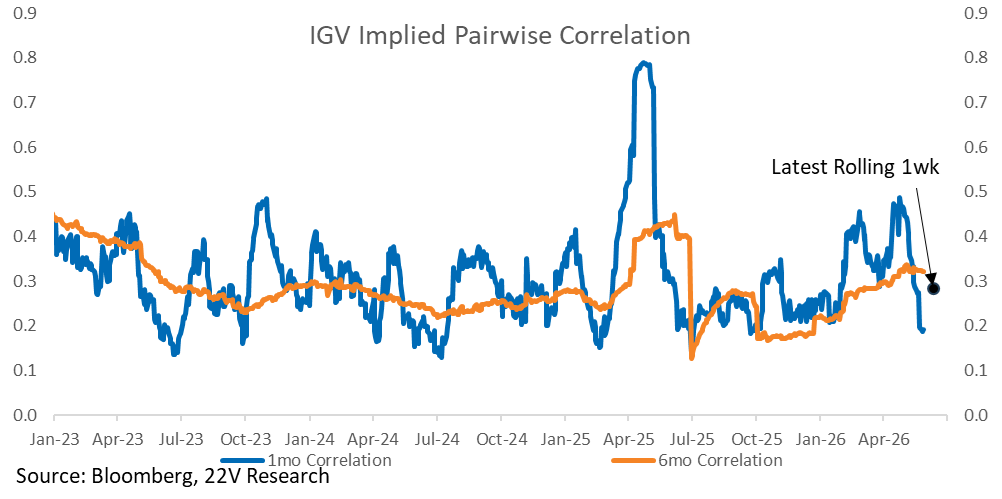
Correlations within Software dropped over earnings season. Stock picking is effective within Software again.
A graph with blue and orange lines

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.