Back Portfolio Strategy

Searching for Software Fair Value After Earnings

Published on May 29, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Kevin Brocks

Sophia Wang

Two things inspired this week’s AI update 1) The calendar, which is always a fun source of inspiration. With earnings season largely behind us, we are forced to mark to market our call on AI differentiation. And 2) High frequency data that fits with our HUNCH – based on comments from Jenson Huang and Ben Thompson at Stratechery HERE and HERE – that the death of all software companies is exaggerated. Ara Kharazian, an economist at Ramp, a corporate payments processor, detailed on Andreessen Horowitz’s a16z podcast how Ramp’s spending data shows incumbent Software has been resilient (so far) (HERE).

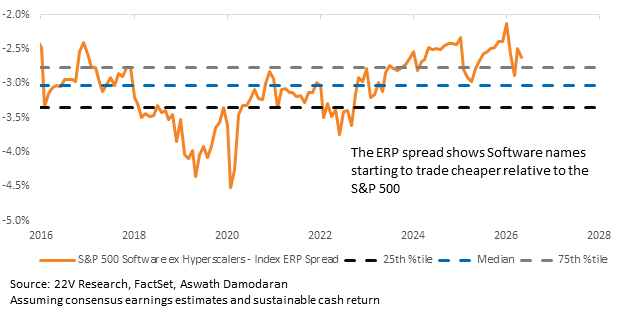
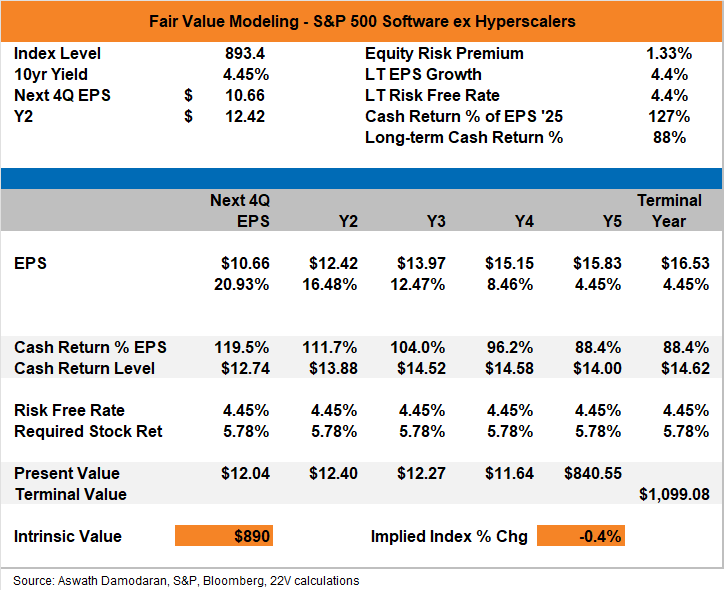
At the beginning of earnings season, we argued there may be some upside in S&P 500 Software ex Hyperscalers IF enough companies began proving they weren’t being displaced by AI, given the hits to forward earnings growth and cash return already priced in. Our fair value modeling* implied valuations were discounting a 6pp hit to the forward earnings CAGR or a ~20pp hit to cash return (dividends + buybacks / net income) (HERE). Our main point was if some Software companies are able to defend their moats/utilize AI themselves, the index was not a compelling short. Today we are marking to market that thesis…

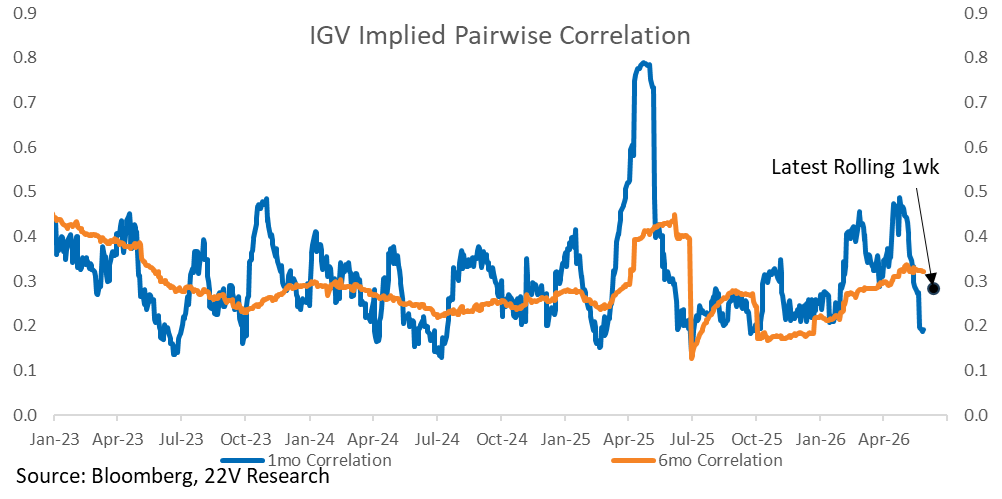
Net net, earnings and the narrative shift around earnings reinforce our view that Software ex Hyperscalers is still no longer an obvious short. There are still significant hits to earnings and/or cash return priced in, while earnings and cash return held up in 1Q and the evidence is that businesses are not yet pivoting away from paying seat-based subscriptions. Software has not yet proven it won’t be disrupted, so it’s not an obvious long either. The practical implications are 1) the asymmetry is higher for the group as a whole and 2) stock picking between winners and losers will matter more going forward. Correlations within Software have declined, supporting this thesis.

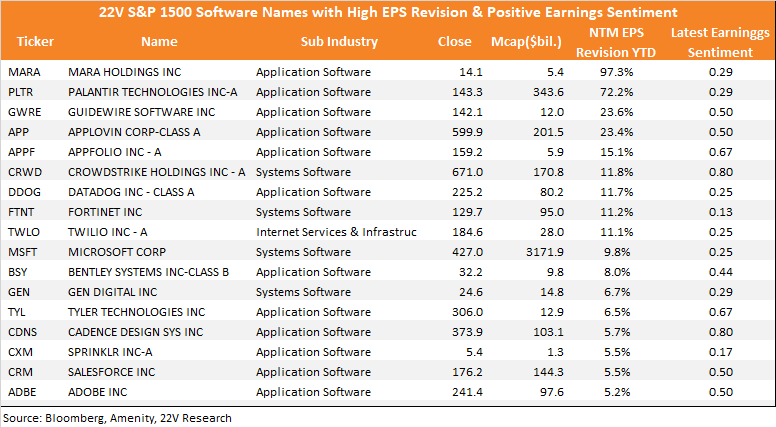
Earlier this week, the Quant team highlighted a list of Software stocks with high EPS revisions and positive earnings sentiment (an objective score of how optimistic management teams sounded about their company earnings during their earnings calls). These names have outperformed the S&P 1500 by +10% YTD, accelerating higher during earnings season. Full report HERE and stock list below.

Details and charts below…

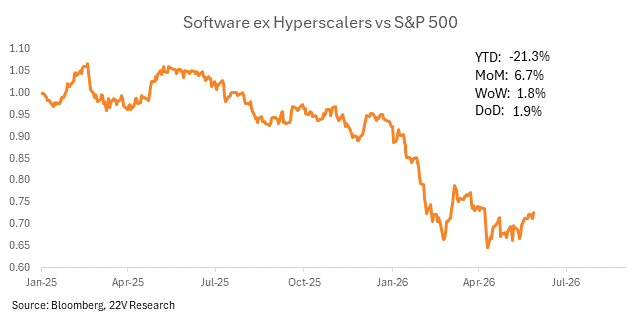
S&P 500 Software ex Hyperscalers are up +7% MoM relative to the S&P 500. Earnings helped the group stabilize; on aggregate, the average excess return from earnings was positive (+1.2%), though the median was negative (-1.2%). In other words, the hit rate of earnings wasn’t great, but the skew of returns was positive. That was the point we made about the asymmetry heading into earnings.
A graph showing a line of a graph

AI-generated content may be incorrect.

Narrative shifts help explain the price performance more than earnings releases. For that, we can draw on some evidence. Ara Kharazian, an economist at Ramp, a corporate payments processor, detailed on Andreessen Horowitz’s a16z podcast how Ramp’s spending data shows incumbent Software has been resilient (so far). Businesses are still paying seat-based subscriptions, not consumption-based models — AI hasn’t disrupted the buying behavior yet. Podcast HERE. This lines up with conversations we are having with investors.

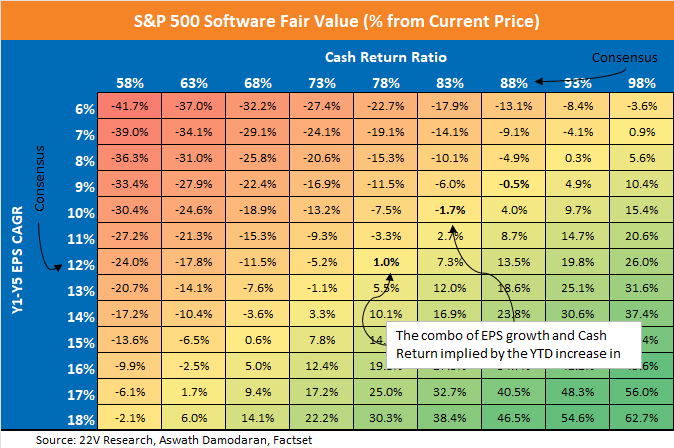
The move in valuations now discounts less, but still significant, declines in earnings estimates or cash return. On their own, valuations imply the 5y forward EPS CAGR falling from 12% to 9% (or 2y forward EPS CAGR falling from 19% to 13%), or Cash Return falling from 88% to 77%. Together, something like an ~83% cash return ratio and an EPS CAGR of 10%. In 1Q, earnings estimates increased, and cash return remained stable. One quarter in, there is little evidence of the downside developing in aggregate. There will be relative losers, but some winners as well.

The below matrix shows Fair Value (% from current price) of different combinations of cash return and earnings, assuming that the equity risk premium was moving ahead of earnings and cash return estimates.
A colorful chart with numbers and numbers

AI-generated content may be incorrect.

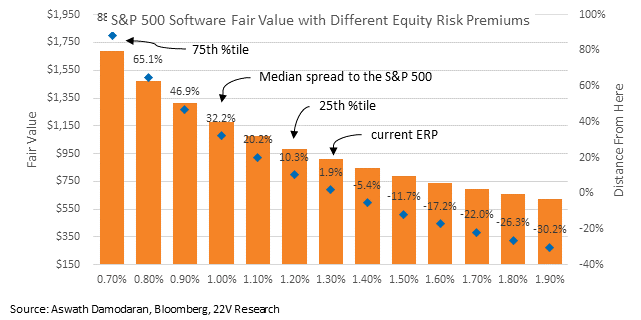
It is still plausible that Software margins or revenue will be impaired. We are not disputing that. Our point is how much is already priced in. IF Software can continue to prove resilience, the equity risk premium is biased towards falling back in-line with a more “normal” spread to the S&P 500. Recovering the entire spread implies a +32% relative return.

Fair Value with different ERPs is charted below, for reference.
A graph of a graph of a graph

AI-generated content may be incorrect.

Correlations within Software dropped over earnings season. Stock picking is effective within Software again.
A graph with blue and orange lines

AI-generated content may be incorrect.

Earnings estimates increased in 1Q and cash return improved. Downside cases are not yet being realized on aggregate.
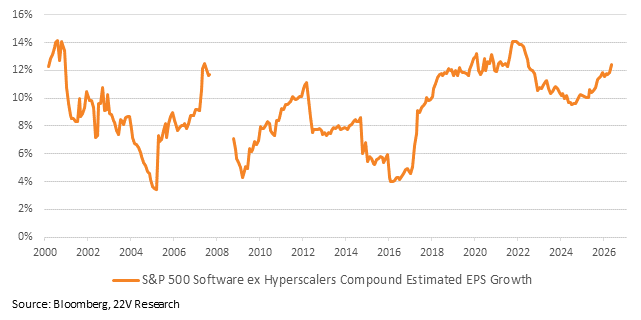
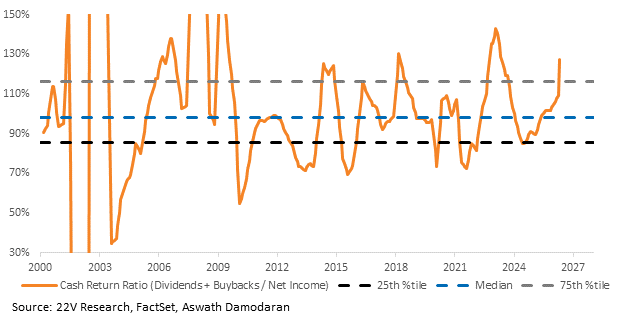
*Our Fair Value model is based off the work of valuation guru Aswath Damodaran. It is a DCF style approach that is akin to valuing an index like a single stock. The cash that is discounted is the cash returned to investors through dividends and buybacks. This approach has helped us work through valuations in a way that is more tangible than say an NTM PE. Please let us know if you would like a copy of our model (or a clearer explanation).
A screenshot of a graph

AI-generated content may be incorrect.

Software names with positive EPS revisions and earnings sentiment have outperformed this year, accelerating higher during earnings season. This is a good list to look for longs within Software as Software correlations decline.
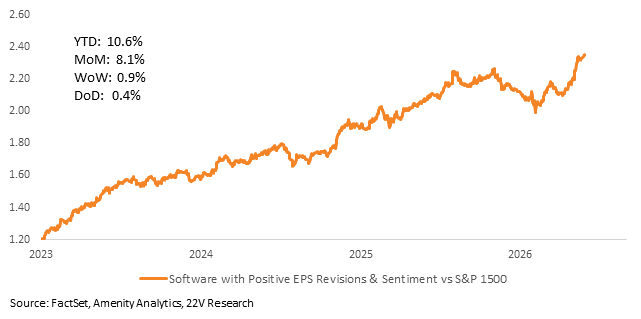
A screenshot of a computer software

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.