
SUMMARY: Our base case remains a benign tariff outcome, defined by us as no tariff-driven price level shock that 1) triggers a short jump inflation, 2) a decline in real incomes, and 3) a more hawkish Fed. Trump’s hawkish tariffs comments overnight (HERE) are being blamed for the +70bp increase in the DXY today. There is not much signal in the USD move. The DXY is down almost -3% since January 13th.
We covered our macro AI views yesterday (HERE). On net, a reduction in AI investment, to the extent it happens, does create a headwind for economic growth and that biases 10yr yields lower. But a sharp slowing in economic growth SHOULD NOT be the base case.
When we marked to market our 10yr view over the weekend (HERE), we highlighted that there is more downside risk to 10yr yields (population growth slowing and now AI capex risk), but recession risk is still very low. The skew around 10yr yields has changed relative to what we thought a few weeks ago, when the skew was higher. Extrapolating yesterday’s 6th %tile DoD decline in 10yr yields is probably not a best practice. though. The economic expansion remains, and is highly likely to remain, in place.
The bigger impact of the DeepSeek story is on equity internals.
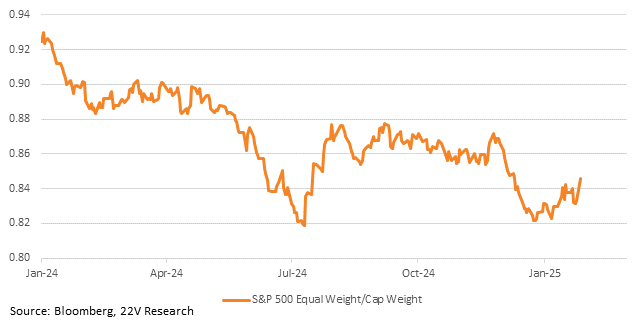
The average company will benefit from cheaper AI tools. That pricing largely played out yesterday, with the equally-weighted S&P 500, mid caps, and small caps outperforming the cap-weighted S&P 500. Focus turns to AI earnings commentary this week.
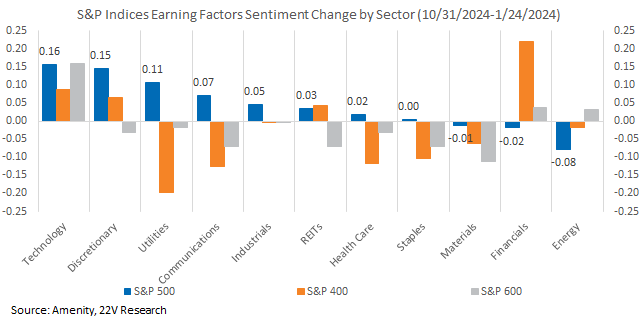
Large cap Early Cyclicals have seen the greatest improvement in forward looking earnings sentiment over the past few months, led by Technology/Discretionary (HERE). Strong earnings reports would be a powerful combo for the potential beneficiaries of cheaper AI models (the average tech stock). Early Cyclicals could have a very strong earnings season, even if some mega caps are coming under pressure. In the full report below, we highlight the Tech + Comm Svcs stocks on our earnings beat basket. These are interesting longs (after vetting for AI provider vs. user, which is not our expertise). We can send the Discretionary names as well.

Here’s an X thread from Helen Toner, formerly OpenAI board, parsing the DeepSeek news that we found helpful: THREAD LINK.
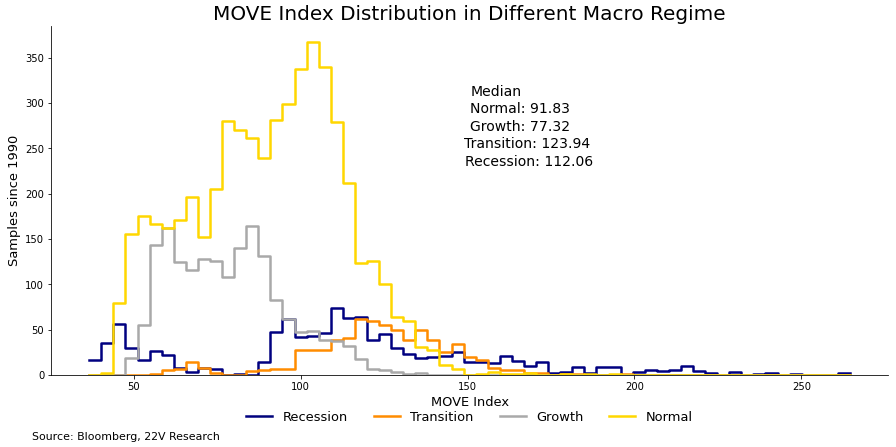
MARKET VIEWS: The tariff pendulum swung back towards blanket tariffs this morning (HERE). There was no new incremental information in the report. This volatility will stay with us. As we pointed out in our 2025 Outlook (HERE), the higher implied rate vol is still consistent with a normal economic expansion. Our base case remains no blanket tariffs, partly because Trump has historically preferred market-friendlier policies.
AI: We covered our macro AI views yesterday (HERE). Net net is that a reduction in the AI investment cycle, to the extent it happens, does create a headwind for economic growth and that biases 10yr yields lower. But a sharp slowing in economic growth SHOULD NOT be expected.
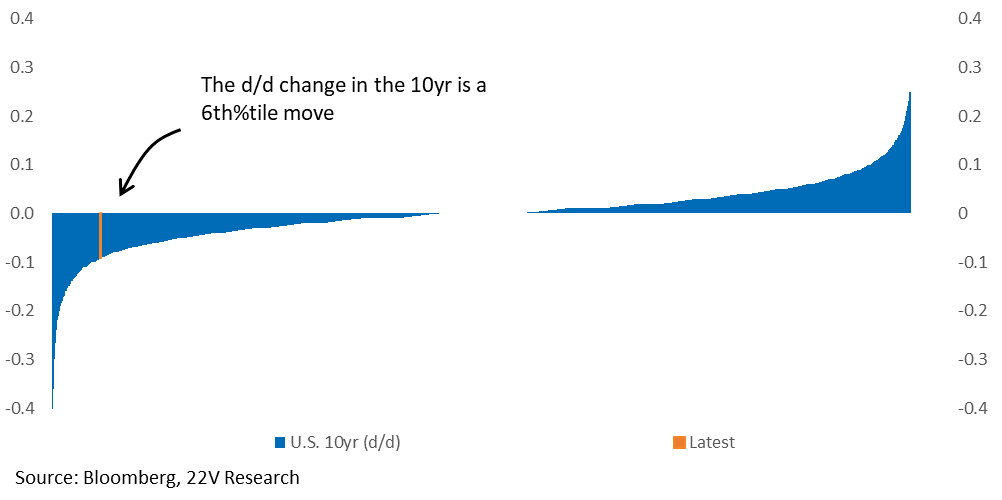
It might be too early to call the AI-related price action yesterday a trend, but it was a massive1 move and will dictate internals. AI infrastructure providers (Semis, Utilities) were crushed on potentially lower demand for chips and power. AI-based cloud-computing services (GOOG, MSFT, ORCL) were weighed down by potential over-investment in AI architecture and shallower moats. AI users and laggards (like AAPL) are the relative winners if they can catch up on the cheap. The average company will benefit from cheaper AI tools. That pricing largely played out yesterday. There are a lot of questions outstanding about DeepSeek’s model and how much it really cost, but it was a shoot first and ask questions later type of day. Focus turns to AI earnings commentary this week.
1NVDA lost almost $600 billion in market cap, the largest 1 day decline in market cap ever, so no hyperbole in “massive.”
In the background, large cap Early Cyclicals have seen the greatest improvement in forward looking earnings sentiment, led by Tech (HERE). Strong earnings reports would be a powerful combo for the potential beneficiaries of cheaper AI models (the average tech stock). Early Cyclicals could have a strong earnings season, even if some mega caps come under pressure.
Here are the Tech + Comm Svcs names in our earnings beat basket – stocks with high Quality of Earnings scores with strong earnings sentiment. Historically, this combo has led to better earnings beat rates than the rest of the index. These are good places to look for longs, though we don’t attempt to filter for AI provider vs. user here.
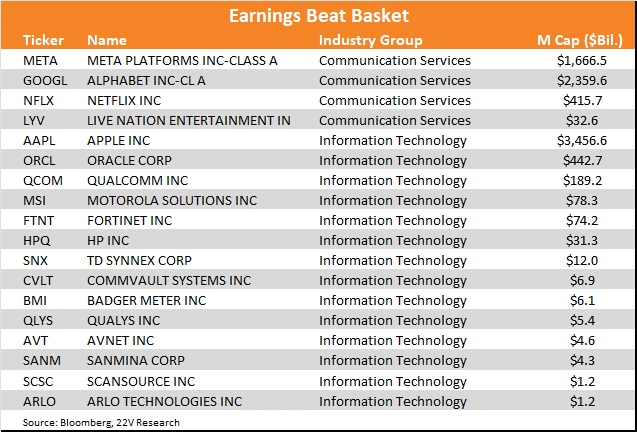
And here are the Tech + Comm Svcs in our earnings miss basket. These are names to be more cautious about.
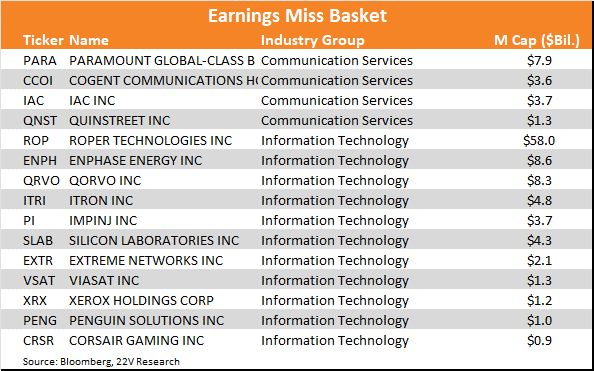
We aren’t AI experts. Here’s an X thread from Helen Toner, formerly OpenAI board, parsing the DeepSeek news that we found helpful though: (1) Helen Toner on X: “Bad DeepSeek takes flying thick and fast today. Thread of good ones instead: (all subject to Matt’s correct meta-take, caveat lector ⬇️ )”/X

