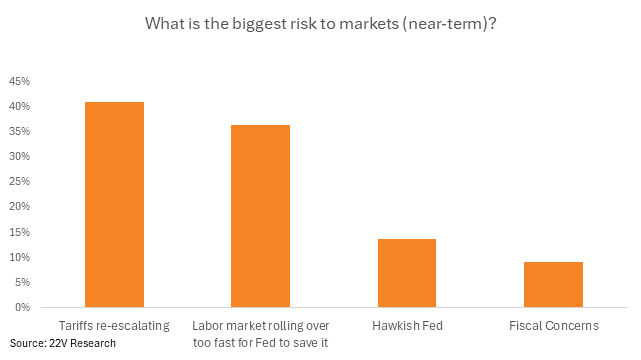
SUMMARY: The investor survey we conducted last week showed a rolling over of labor markets as one of the biggest investor concerns (HERE). Claims data were fine yesterday, but we are still getting questions about labor market weakness this summer.
As Peter Williams laid out HERE, tariffs are imposing modest hits to productivity growth and investment, and immigration’s rapid decline is slowing trend labor supply growth. GDP growth should slow over the summer, and the labor market slack will increase some. Investors will be concerned about pre-recessionary economic conditions. That SHOULD keep 10yr yields anchored and financial conditions easy.
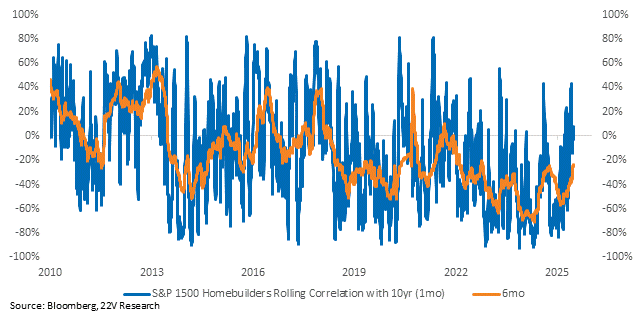
The process of economic and payroll growth slowing COULD be a tailwind for Homebuilders over the coming months. A group that many investors are negative on (we agree with the negative long-term homebuilder call). Biotech also looks interesting on the long side. Biotech has unusually high short interest now. With the help of Jeff Jacobson, 22V options strategist, we introduce two options trades today to take advantage of upside risk in Homebuilders and Biotech through the summer.
Longer Term – The lack of accelerating weakness in the labor market and continued health in aggregate balance sheets, credit markets, and the private sector financial balance should help put a floor under growth and recessionary fears. On Tuesday (HERE), we outlined how an increase in yields can happen in late summer as labor markets and demand growth stabilize, and a fiscal impulse in the 1H26 is discounted. With inflation still likely to be above the Fed’s 2% target at the same time, 10yr yields WILL have significant upside risk. That will be a major headwind for interest rate-sensitive sectors like Homebuilders and Biotech. But we can’t ignore what looks like a pretty benign short-term backdrop for rate vol near term.
More details in the full report below…
MARKET VIEWS: The 22V call is that tariffs are imposing modest hits to productivity growth and investment, and immigration’s rapid decline is slowing trend labor supply growth (HERE). These jointly are imparting a downward blip to GDP growth that is NOT expected to lead to a non-linear recessionary weakening of the economy. Some labor market slack is going to increase over the coming months though. It is fair to assume that as GDP growth slows and the labor market slack opens some, investors will be concerned about pre-recessionary economic conditions.
INTEREST RATE SENSITIVE TRADES: The lack of accelerating weakness in the labor market and continued health in aggregate balance sheets, credit markets, and the private sector financial balance should help put a floor under growth and recessionary fears. On Tuesday (HERE), we framed out how an increase in yields can happen in late summer as it becomes apparent that we have a tighter-than-expected labor market, stronger-than-expected demand growth, and a fiscal impulse in the first half of 2026*. In the meantime, yields are likely to be anchored and financial conditions easy. That COULD be a tailwind to Homebuilders over the coming months. A group that many investors are negative on (we agree with the negative long term homebuilder call).
*None of the developments in the fiscal picture yesterday were surprises. This point remains in place. Our broader view on yields depends more on our labor market and demand growth views though.
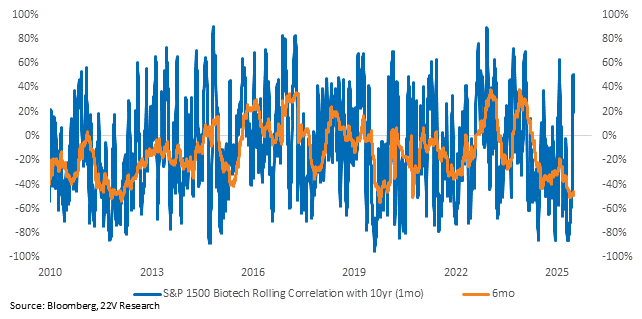
The same logic applies to Biotech. There’s an overhang from government policy, but the group is still trading with high sensitivity to yields…
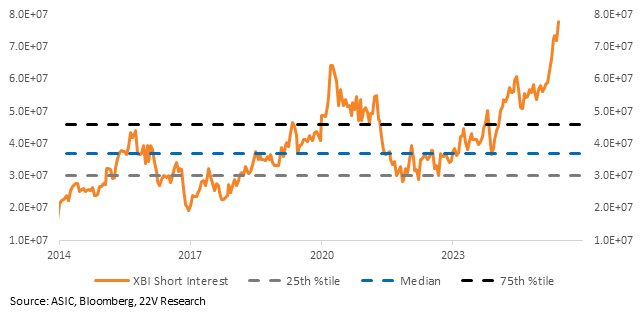
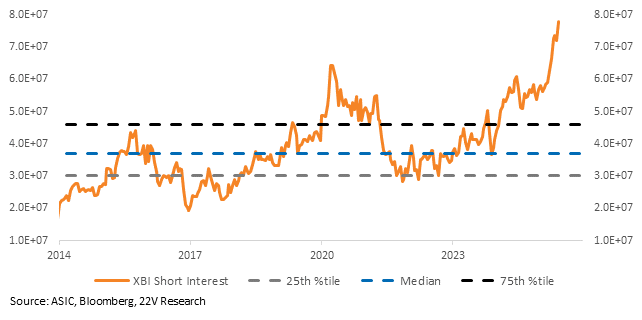
…while Biotech short interest is at an all-time high.
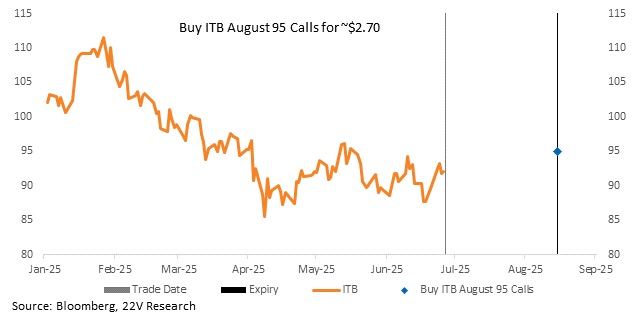
Jeff Jacobson, 22V Derivatives specialist, structured short-term ITB and XBI options trades, expiring in August, to position for our view.
ITB: Jeff would target a breakout above the YTD downtrend as well as the 100-day moving average.
2-month (Aug) implied vol has come down substantially, and with sentiment (and likely) positioning negative, buying calls outright makes the most sense.
Trade:
Buy ITB Aug 95 calls for ~ $2.70 (ITB 92 ref)
> Buying the August 42-delta upside calls
> Implied vol down to ~ 26-27 from a high ~ 44 in April
> The 95 strike call is just above both the YTD downtrend as well as the 100-day moving average
> Aug expiry captures earnings from many of the main builders (DHI, PHM, NVR)
XBI: Similar to ITB, Jeff wants to own calls outright in XBI if looking to play upside:
1) 2-month 40-delta call vol is back near the lows
2) Sentiment remains very bearish and perhaps most importantly, short-interest is now at 5-year highs
Trade:
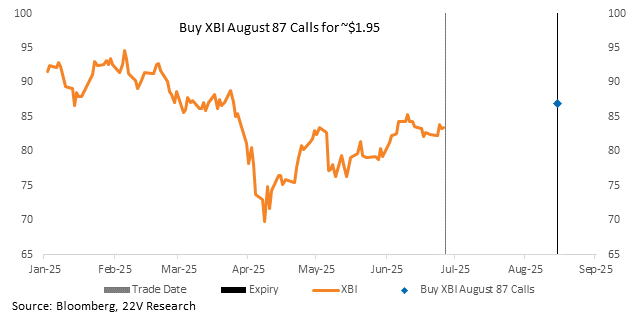
Buy XBI Aug 87 calls for ~ $1.95 (XBI 83.55 ref)
> Buying the Aug 37-delta calls
> Seeing 2-month 40-delta call vol down from 47 to a current 26
> With short-interest at these levels any good news for the sector could really get things moving quickly