DAILY STRATEGY: We are making the call that bond vol is biased lower and that will support some recent industry group laggards. The economic data test for bond Vol will be CPI and PPI data on 10/14 and 10/15. Bond vol will not MOVE lower (pun intended) if the inflation data is more hawkish than expected.
10yr yields are still primarily driven by the current strength of economic growth, which is why the overall market has reacted well to the increase in 10yr yields. BAA-AAA spreads are tight, and the yield curve has re-steepened. Both suggest strong growth is supporting the 10yr. As we highlighted yesterday, the spread between the VIX and the MOVE (bond VOl) is a 77th %tile reading. Investors we talk to are more worried about the VIX increasing to “close the gap with bond Vol”. If 10yr yield were obviously restrictive and increasing recession probabilities, the VIX should move higher and close the gap with bond vol. BAA yields would widen relative to AAA.
We think the opposite happens near term and bond vol moves lower to close the gap with the VIX. The risk reward is better for non-AI Cyclicals that lagged significantly in September. Like Transports, Retail and Banks. 4-5 rate hikes already priced in (and unlikely in our view. Our call is 2-3 hikes), and the current level of financial conditions and 10yr yields should slow growth. See a short video for more details on this HERE.
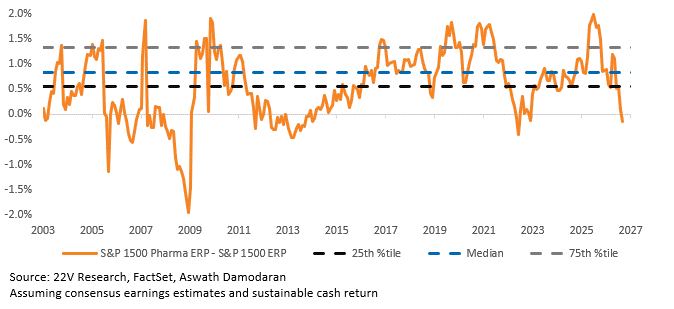
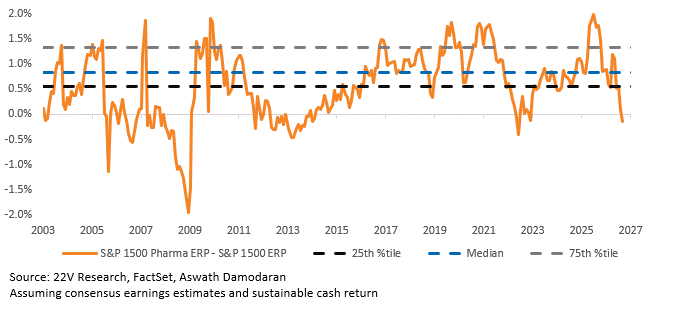
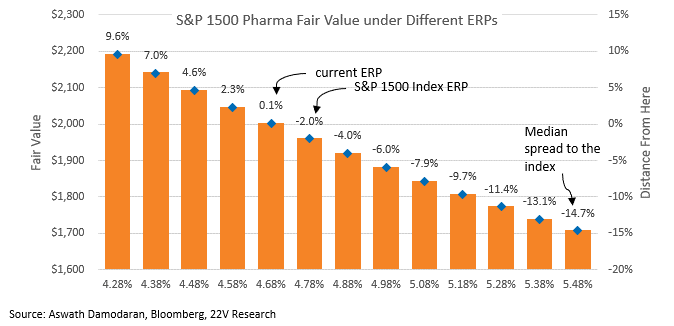
PHARMA & BIOTECH: Pharma & Biotech valuations have moved into a new regime relative to the S&P 1500. The Pharma & Biotech index equity risk premium (ERP, discounting expected dividends + buybacks) is richer than the S&P 1500 index, which is highly unusual outside of recessions or bear markets, and the macro and equity backdrop is far from recessionary, with the speed limit on growth being the primary concern (HERE). Valuations are implying AI will transform the industry into one of higher growth.
We don’t have an expert view on how much AI will transform the earnings and operational efficiency of drug development. The Quant team highlighted how AI is not yet, in aggregate, showing up in earnings (HERE). Our goal is to simply lay out what the bet is at this point. Hopefully that is helpful. Consensus estimates for Pharma and Biotech earnings growth have already moved up to the 93rd percentile. The richening in valuations has happened concurrently, and since AI began trading as a major market theme in 2023. An equity risk premium at the current level is discounting record high earnings growth.
Details below…
The S&P 1500 Pharma and Biotech ERP is trading with a richer valuation than the index, which is unusual outside of recessions/bear markets.
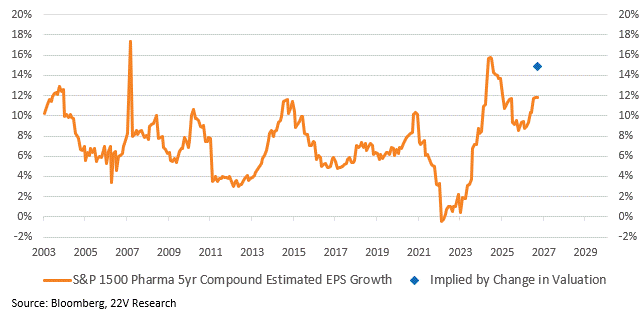
EPS estimates have already moved to reflect a better outlook. The 5yr compound EPS growth rate is at its 93rd percentile. Valuations have increased in addition to the increase in EPS estimates. If we consider the change in valuation equity price moves ahead of additional eps upgrades, the expected EPS CAGR would be +3pp higher to15%, a 99th percentile growth rate.
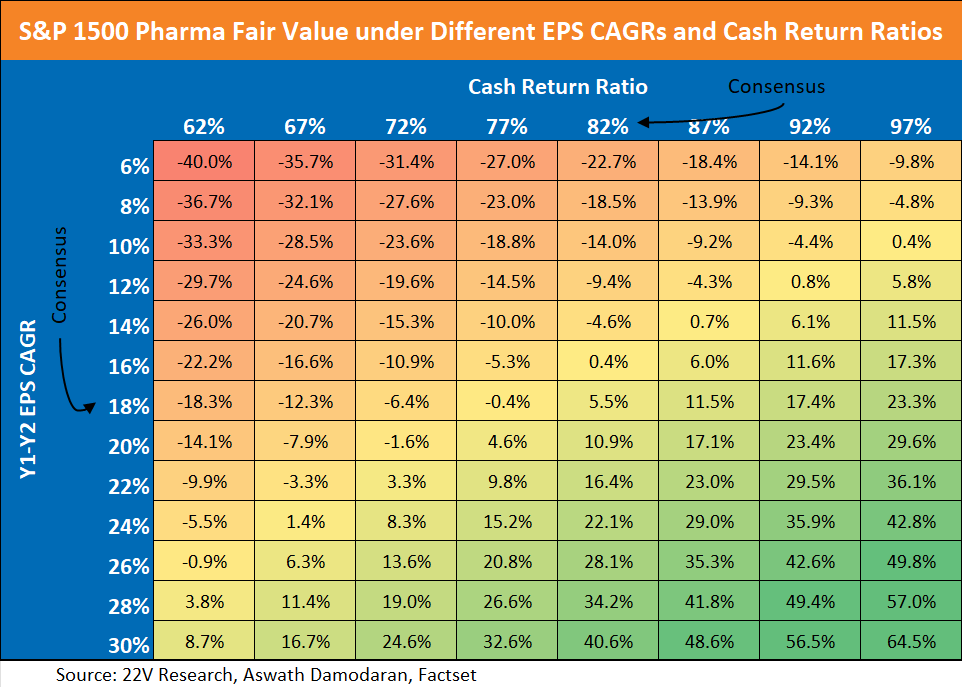
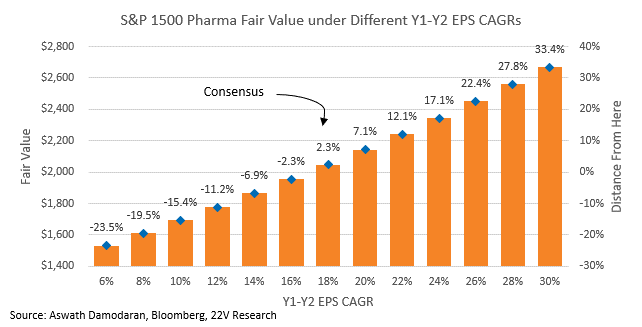
Fair value with different EPS CAGRs is below, assuming the current ERP holds. We do not have an informed view on how AI will transform drug development, but the below is hopefully helpful towards getting a sense of risk reward. Again, assuming the current level of valuations holds.
Fair Value given different levels of the ERP below…
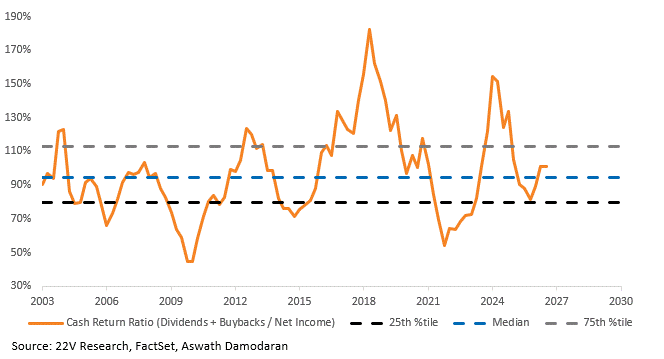
If AI boosts profitability enough that Pharma allocates more to cash return, there is further upside. Fair Value with different combinations of EPS and cash return below. Again, use this table to get a sense of risk reward around different scenarios. This assumes the current ERP, which is unusual relative to history, holds.