

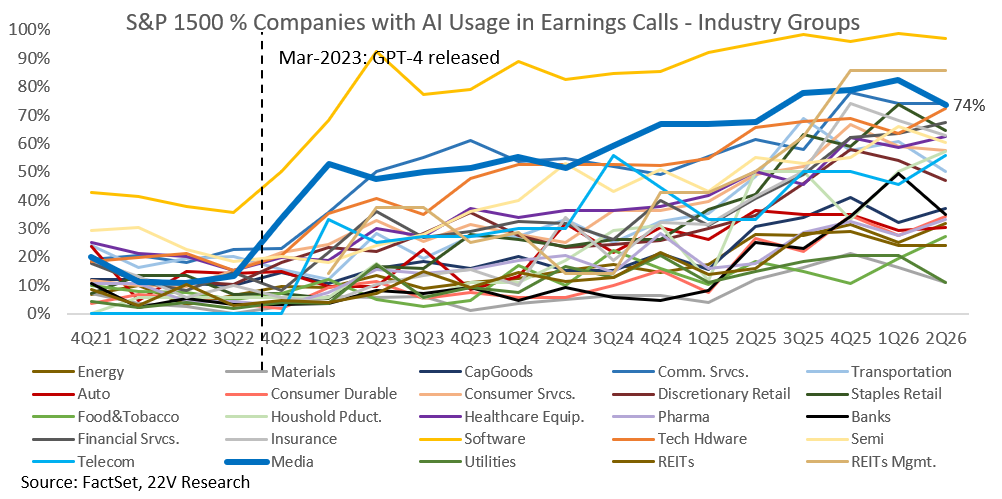
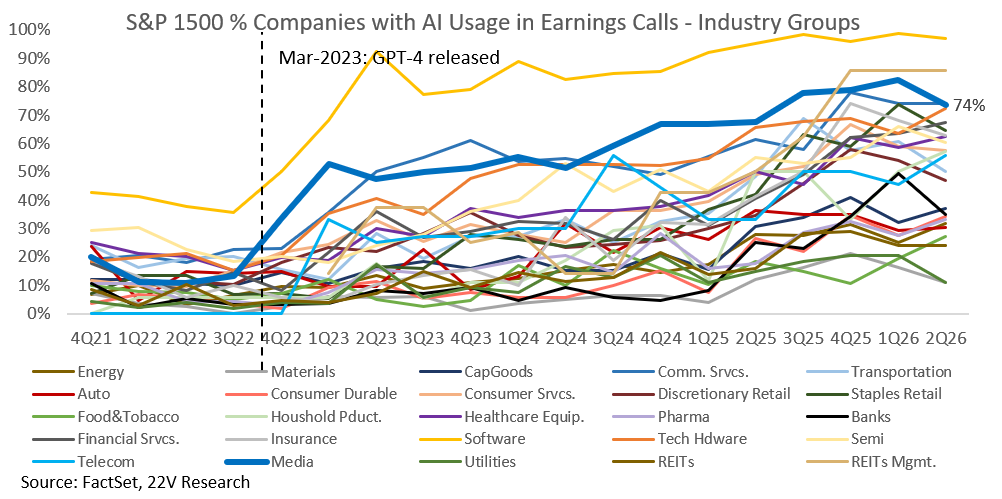
Media & Entertainment competes for consumers’ time. Every minute spent on one platform is a minute unavailable to another, making attention a more constrained resource than consumer spending. AI is becoming central to that contest. 74% of media companies now cite AI usage, the third-highest share among industry groups.
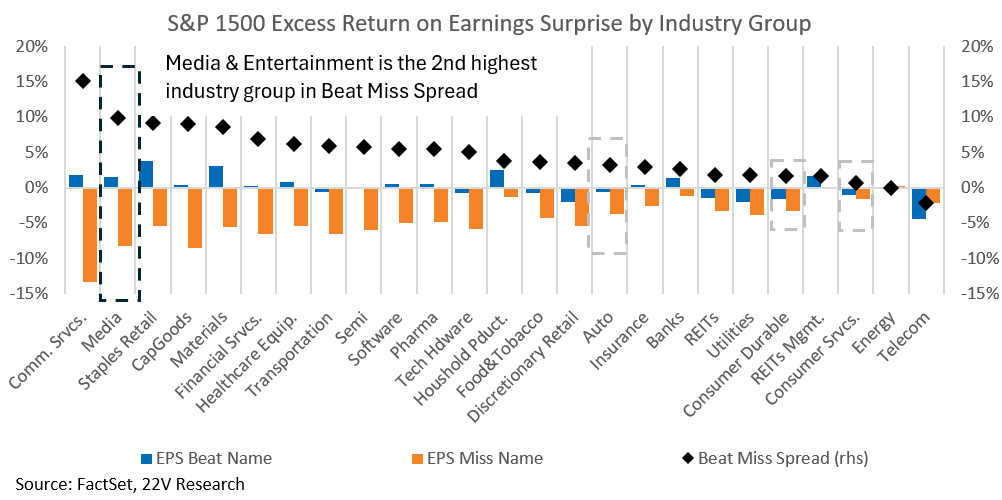
The 2Q26 earnings data suggests AI adoption raises stakes rather than guaranteeing reward. Media & Entertainment recorded the second-highest beat–miss return spread of any industry group. On the beat side, AI users and non-users both posted median excess returns modestly above their historical medians. On the miss side, AI users were punished much more severely, driving most of the spread.
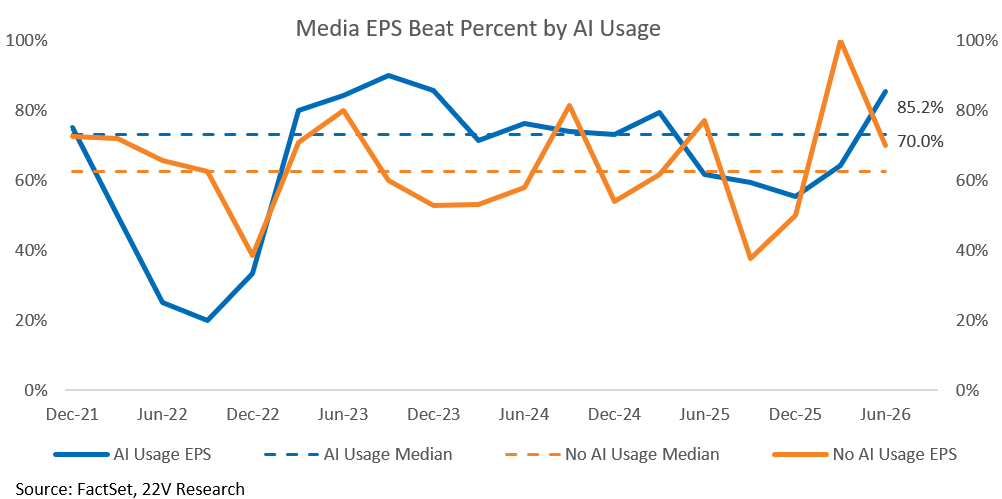
AI users also help explain an unusual split in operating results. The group’s EPS beat rate rose 14pp to 80%, while its sales beat rate fell seven points to 77%. Sales beat rates declined in both cohorts, but EPS beat rates rose sharply among AI users and fell among non-users.
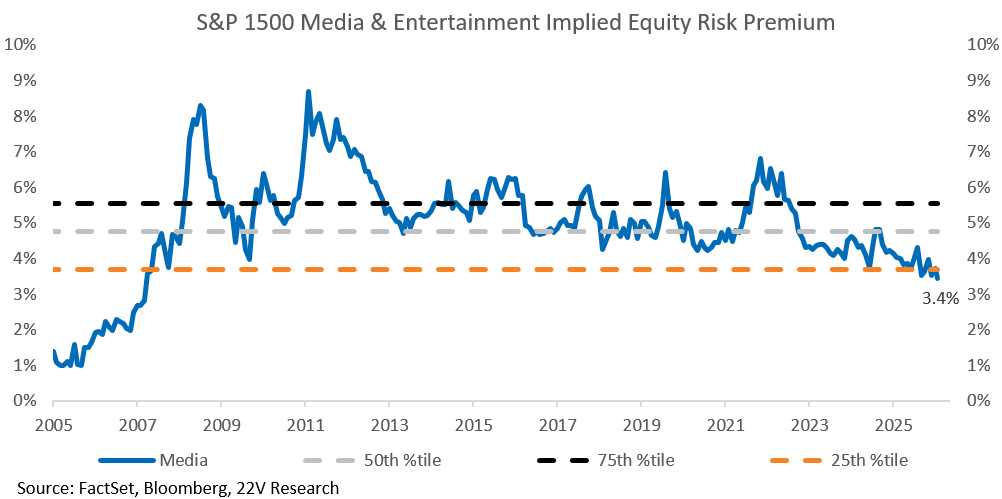
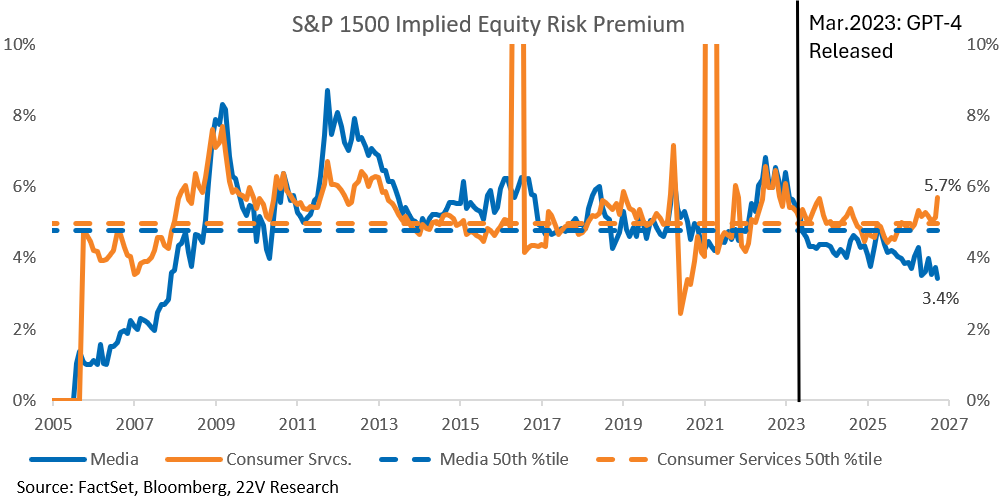
Currently the group’s implied equity risk premium is at a post-GFC low, diverging significantly from Consumer Services post GPT-4’s launch. That suggests the market has already priced the attention premium and the high valuation leaves little room for disappointment.
Meta’s launch of its first personal AI agent, Muse, is fueling AI optimism while raising questions for the business model it sits inside. If AI agents complete tasks with less scrolling and browsing, they could reduce the consumer attention that today’s platforms monetize. From this perspective, AI agents could reshape both the competitive set and the ecosystem for the group.
Attention is the Scarce Asset and Muse May Break the Rule: Similar to Autos and Consumer Services, which we covered in previous weeks (HERE) and (HERE), Media & Entertainment is also consumer-facing. The difference is what it monetizes. Media & Entertainment earn from where consumers spend their time, not what they buy. As the DoorDash CEO mentioned, “…there would be two big wars that would occur, one is kind of the battle for attention…the other is kind of the battle for atoms…”, and Media & Entertainment is fighting the first war for attention while Consumer Services is fighting the second.
Media & Entertainment carries the second highest beat–miss spread of all industry group in 2Q26, well above other consumer facing groups we highlighted in recent weeks: Auto, Consumer Durables and Consumer Services. Fundamental delivery is rewarded and punished more sharply here than almost anywhere else.
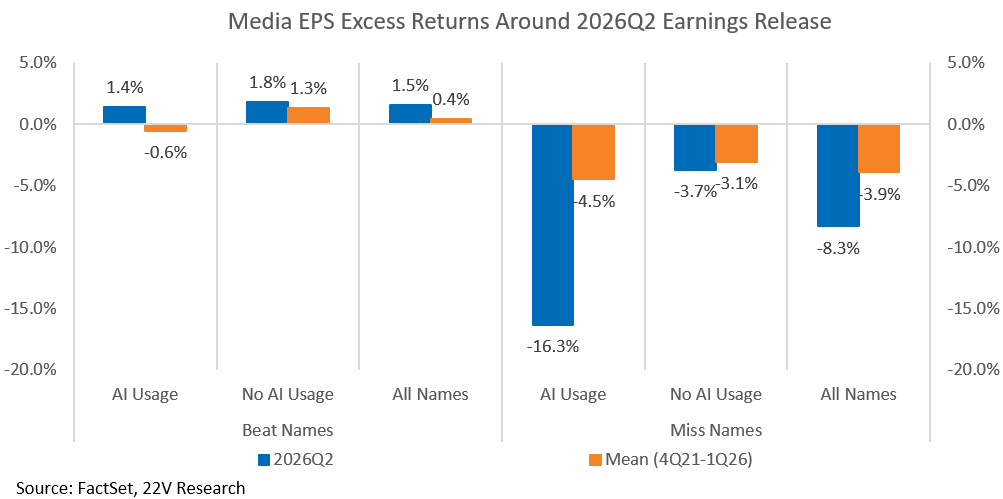
Decomposing the Media & Entertainment beat and miss baskets into AI-usage and non-AI-usage names explains the large spread. On the beat side, both AI and non-AI baskets saw median excess returns modestly above their historical medians. On the miss side, AI-usage names were hit much harder than non-AI misses, pulling down the overall miss return and widening the spread. The implication is not that AI usage is rewarded. It’s that AI usage raises the cost of a miss. Once a company tells the market that AI is part of its growth strategy, a miss can be interpreted as evidence that the strategy isn’t working.
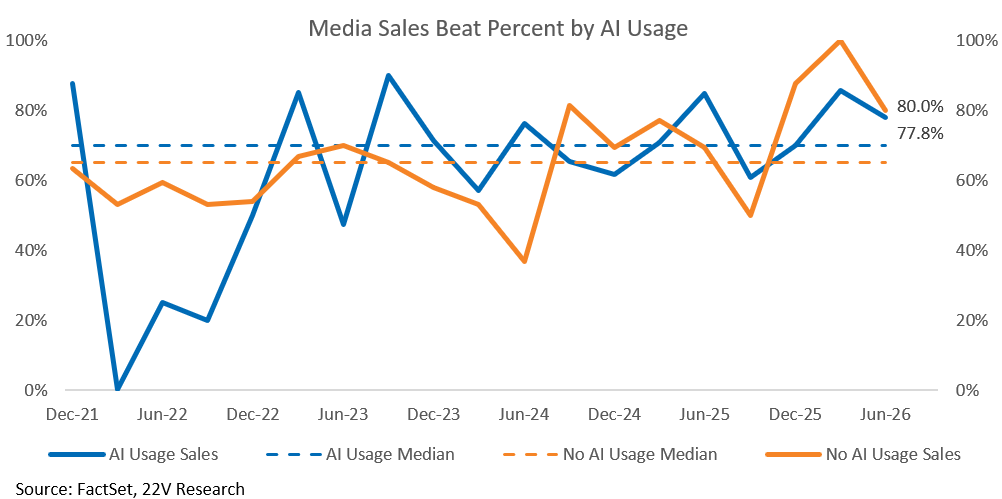
On the EPS and sales beat side, AI usage again helps explain the divergence in 2Q26. Both beat rates were above their historical medians, but they moved in opposite directions. EPS beat rates rose 14pts to 80%, while sales beat rates fell 7pts to 77%. A divergence of this size within Media & Entertainment has rarely been seen since 2018.
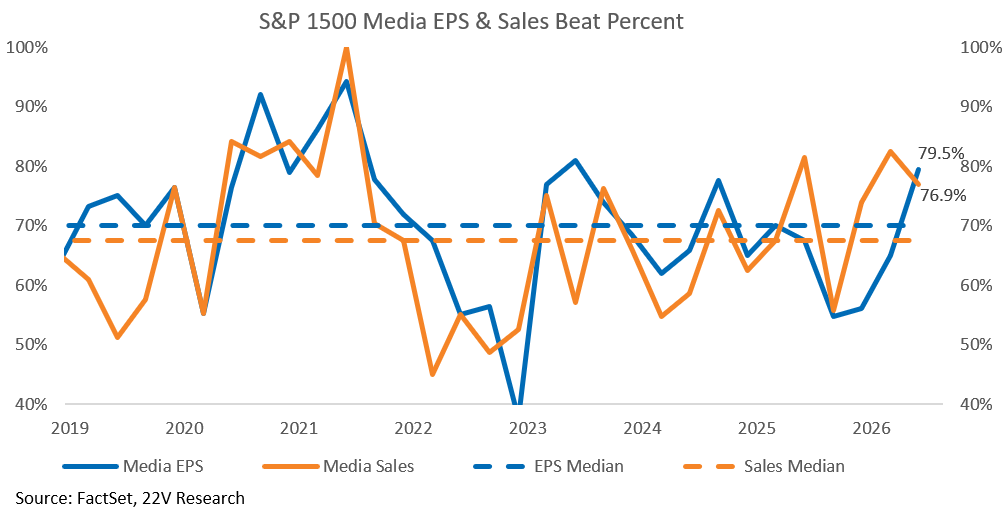
The sales side was unremarkable. Beat rates fell for both AI-usage and non-AI-usage names, and the two together pulled the group’s sales beat rate down.
The EPS side is where the anomaly shows up. AI-usage Media & Entertainment names saw EPS beat rates tick up sharply in 2Q26, while non-AI-usage names ticked down just as sharply. That split accounts for almost all of the divergence between sales and EPS at the group level, and it raises some questions. Why do AI-usage Media & Entertainment names behave so differently, and what in their business models or operations accounts for it?
Why Median & Entertainment is an AI-usage leader
Attention, unlike a wallet, can be actively enhanced by AI, the benefit to the underlying business model is structurally larger in Media & Entertainment than any other group. Since GPT-4’s release, Communications has ranked second among all sectors by percent of companies citing AI usage. That is not simply a Google and Meta effect. The breadth of adoption across the sector points to a common objective of using AI to capture more consumer attention.
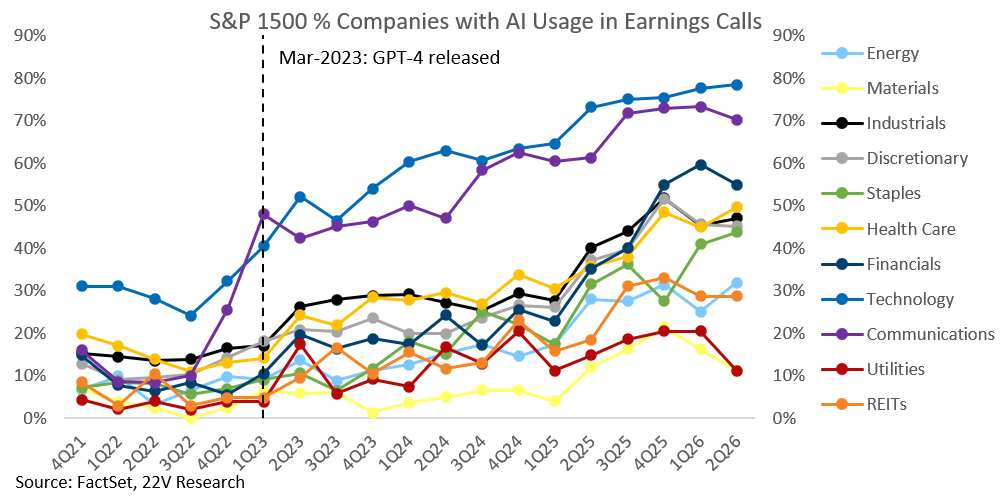
Within Communications, Media & Entertainment is the higher-adoption industry group currently at 74%, the third highest of all industry groups. Only Software and REITs Management rank higher —Software is widely acknowledged as the AI adopter group and REITs Management has higher usage only until recently, making Media & Entertainment higher adoption rate more meaningfully tied to its business model.
In 2Q26 earnings calls, the language of “AI used to win attention” was widespread across the group. For example, Pinterest CEO mentioned “I will focus my remarks on two topics that cut across those priorities, how AI is powering our user momentum and how we’re turning that strong engagement into more durable monetization.”, and Disney CEO said “AI is helping us improve personalization on Disney+ and it allows us to further enhance our recommendation engine…In an increasingly fragmented attention economy, consumers are choosing to spend their time with us.”
By comparison, Consumer Services executives describe the opposite objective in using AI – conversion, not engagement. As restaurant company Papa John’s CEO mentioned, “…a more frictionless path to purchase…customers using Lou AI are converting at an 18% higher rate and completing their orders approximately three minutes faster.”, which treated reduced time-in-app as the achievement. Three minutes less in the app is a win for Consumer Services while a loss of inventory for Media & Entertainment. The same technology is being pointed at opposite goals.
Valuation: the market has already priced the attention premium
Alongside rising AI adoption within Media & Entertainment since 2023, S&P 1500 Media & Entertainment’s implied equity risk premium has fallen continuously, and now sits at its lowest level post-GFC, which indicates the group’s most expensive valuation in eighteen years.
The more striking observation is its relative valuation. Media & Entertainment and Consumer Services ERPs tracked each other closely post-Covid, and before GPT-4 released the two series were nearly overlapping. While their implied ERP diverged post the GPT-4 release and moved in opposite directions in recent quarters.
As a Strategy report mentioned (HERE), Consumer Service is negatively exposed to AI driven factors, and it needs to slowdown to absorb the dropping inflation. While the divergence cannot be attributed to AI alone. The two groups run opposite business models — targeting attention versus targeting the wallet — and applying the same technology to both has widened the gap: one re-rated to its cheapest level in three years, the other to its most expensive level since the GFC.
Forward risk: Meta’s Muse brings risk to the attention model
Muse is the clearest candidate to break the attention model from inside the group. One paper argues that “Superplatforms Have to Attack AI Agents” (HERE), identifying the fundamental tension underlying the relationship between superplatforms and AI agents: superplatforms monetize user attention, while agent autonomy is attention-free.
Whether that conflict resolves as the paper suggests is debatable, and the ethics of the scenario are contested. But it frames the outlier risk. An agent that completes tasks for users removes the scrolling, searching and browsing that the incumbent model monetizes. Based on what the paper suggests, Muse could invert the mechanism, targeting advertising and algorithmic curation that makes attention valuable to Media & Entertainment today. Consumer inertia is what decides the speed, and it cuts both ways, protecting incumbents, and delaying Meta’s own monetization. Muse may become the rule-breaker to watch, and it could reshape both the competitive set and the ecosystem for the group.

