

Bottom Line: Our Call
The economy should remain in a normal expansion as tariff and oil-related inflation fades and consumer spending returns toward trend. The Fed may hike 1–2 times to contain inflation but has room to cut IF growth slows too much. This environment should favor fundamental factors, price momentum, and cyclicals over defensives. Risk-on factors should outperform, though with weaker risk-adjusted returns than in a stronger growth, lower-volatility environment.
Relevant News: Inflation Risk to Our View
If the sum of CPI/PPI data this week leads to forecasts of 0.3% MoM for Core PCE, that will keep hikes on the table for September. Recall, last month Core PCE inflation data was more dovish than expected. Core PCE can now come in at 0.22bp a month to hit the Fed 3.3% target for 2026 Core PCE (vs 0.21 previous). 0.25bp for core PCE is likely not a problem given the dovish last month and labor data. Close to 0.3%, or more, MoM could be more of a problem for risk assets. Higher inflation is a risk to our bullish framework, which is why lower costs hedging against a hawkish inflation outcome makes sense now.
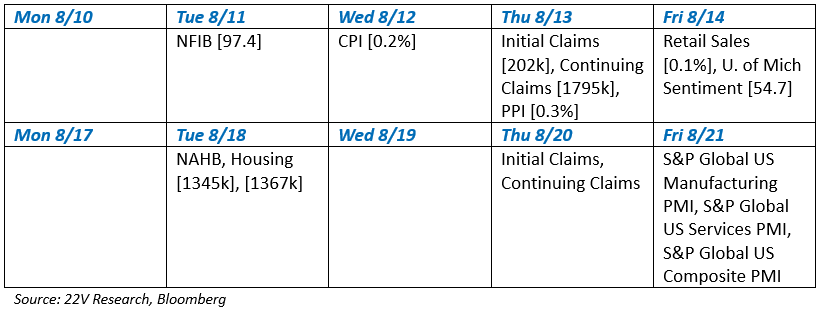
Things to Watch [Consensus, Results]:
Strategy:
More Durable Expansion Setting Up a More Positive Risk-On Skew– (HERE)
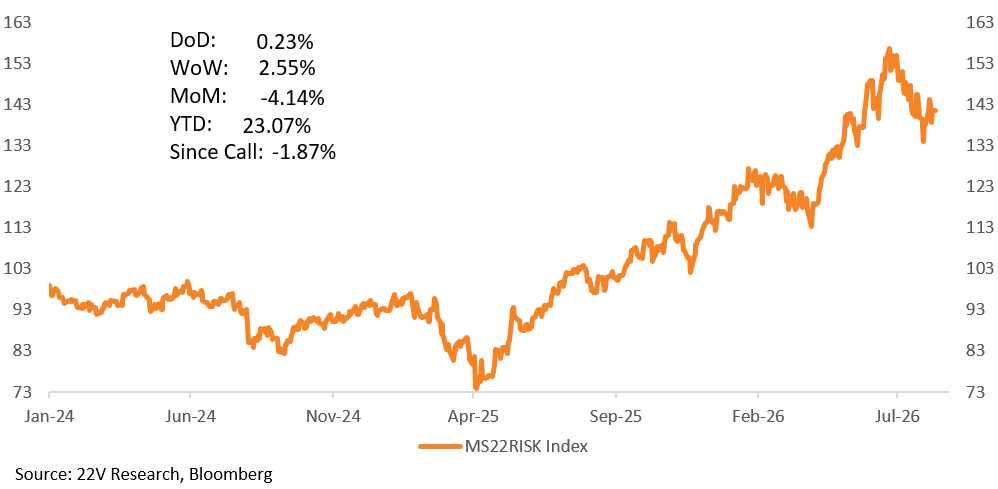
The Risk-On factor baskets outperformed Risk-off by +2.55%. The NTM PE spread between Risk-on and Risk-off is below its long term median and NTM EPS growth is +10% for the Risk-on basket relative to Risk-off. Also, fundamental factors continue to perform unusually poorly RELATIVE to what is typical in economic expansion.
Derivatives Strategy:
Put/Call Skew at the Lows Makes Owning Low-Cost Collars a Very Attractive Option as Markets Hit New Highs– (HERE)
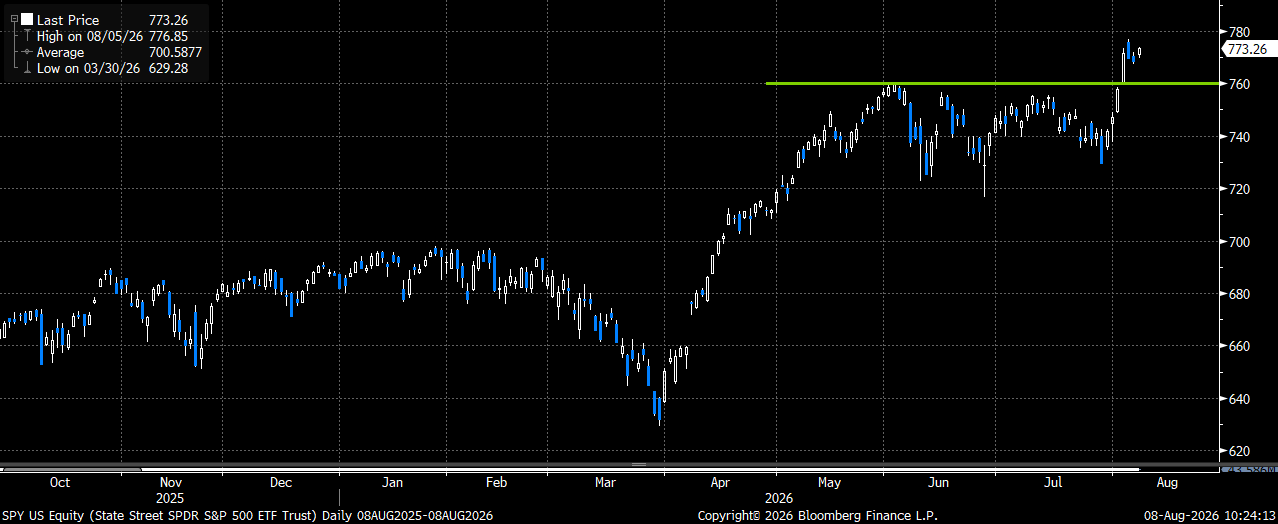
Equities rallied strongly last week, with the S&P and small caps gaining over 3% and the Nasdaq up 5%, while gold and silver also surged as the US dollar weakened. With SPY at all-time highs and the VIX near a multi-year floor, the market still favors the long side, but geopolitical risks and stubborn yields warrant some protection. Favorable put/call skew makes low-cost SPY collars attractive for protecting equity exposure, while a similar dynamic in gold creates an opportunity to use costless GLD collars to stay long while protecting recent gains.
Data Infrastructure / Commodities:
Regulatory Pressure Into Midterms: Scarcity Value Builds for Compute and Permitted Power; Hyperscaler capex update – (HERE)
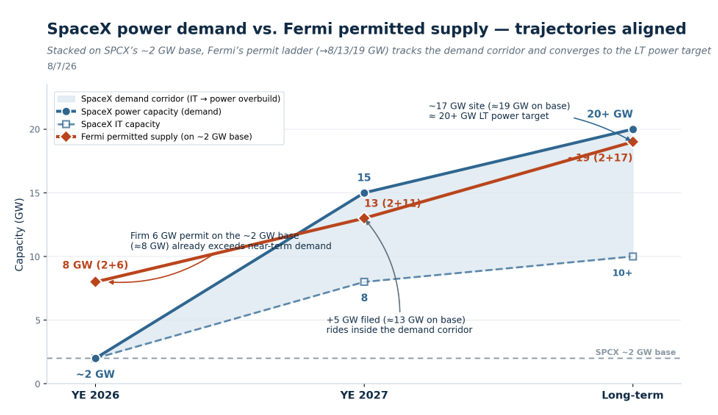
Regulatory scrutiny around AI data centers is increasing, raising the value of existing compute capacity, permitted power, and grandfathered projects and supporting names such as SPCX, ORCL, CRWV, NBIS, and FRMI. At the same time, hyperscaler capex expectations continue to climb, reinforcing strong demand for compute and power infrastructure. With CRWV, NBIS, and FRMI reporting this week, key areas to watch include competitive dynamics, financing conditions, and the pace of capacity buildouts.
Source: 22V Research; SPCX Q2 Earnings; FRMI Q2 Presentation

