

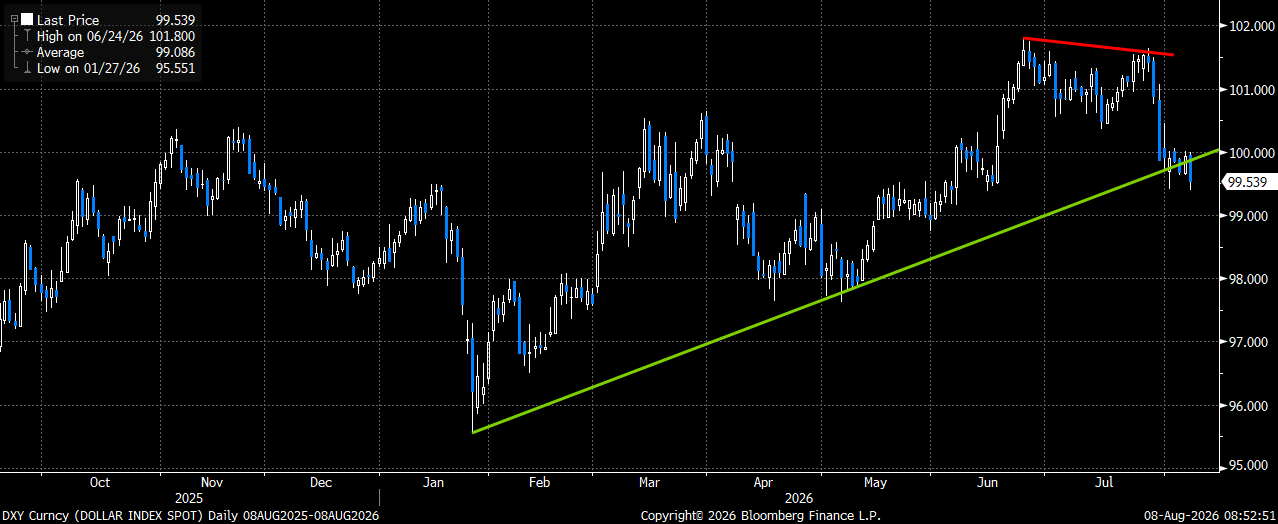
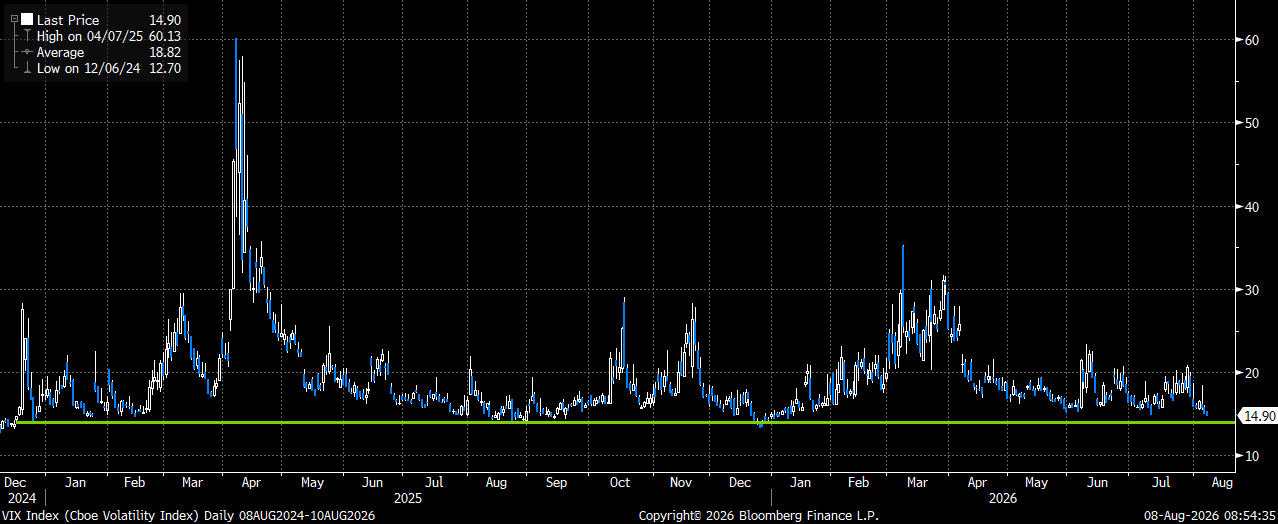
Last week was another strong one for the equity markets, with both the S&P (SPY) and small caps (IWM) gaining over 3%, while the Nasdaq (QQQ) gained 5% (and it has now erased most of the 11.6% recent decline). Silver (+9.8%) and gold (+7.25) were also standouts as the US$ index closed at a 2-month low. The VIX closed at lows last seen in January and is now once again back at levels where we have seen a vol “floor” over the past few years.
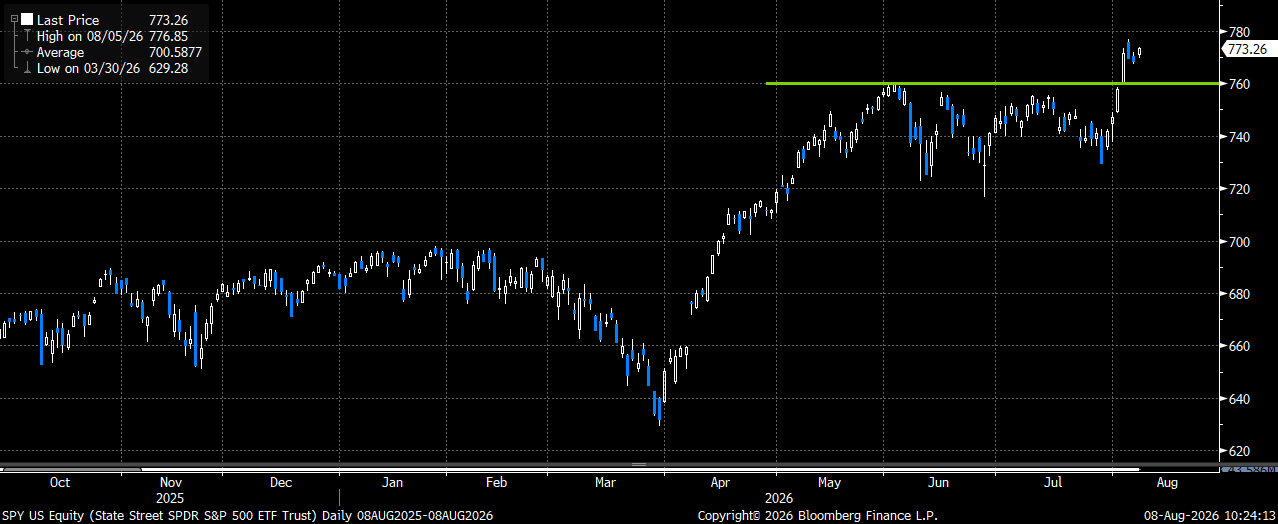
SPY with a clear breakout above the former highs this week
The US$ index (DXY) with a break below the January uptrend. A weaker US$ should continue to give a bid to commodities
The VIX index closed the week at the January lows and is back to levels where it has bottomed over the past two years
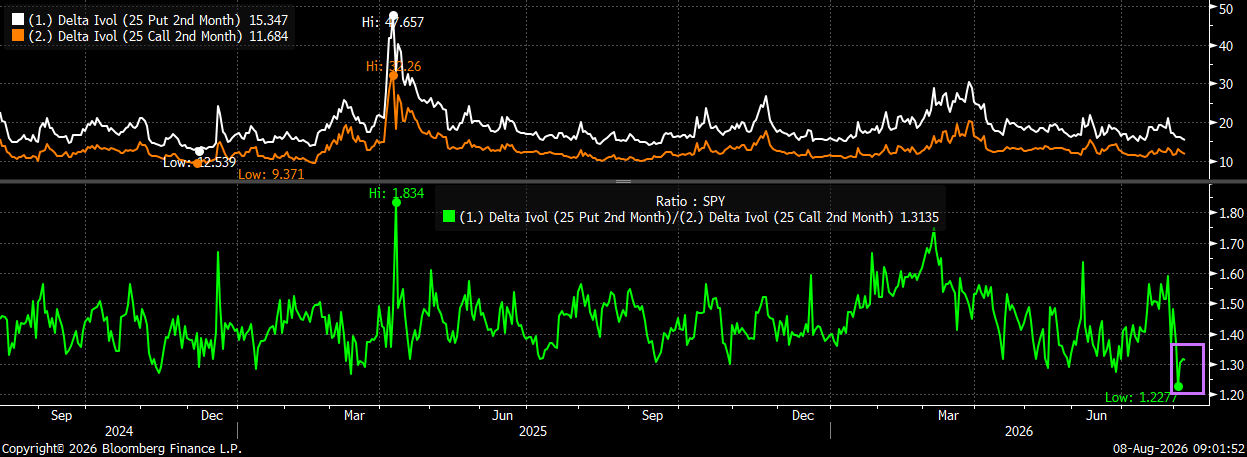
With VIX at the lows, and SPY at new all-time highs, this is still a market you want to continue to play from the long side. However, with remaining geopolitical concerns as well as yields still unable to make any sustainable move lower (even on the dovish jobs report yesterday), you want to be smart about playing for continued new highs. The one chart that keeps sticking out to me is the current put/call skew I am seeing across most equity indexes. Whether it is the continued bid for upside market exposure, or a bit of complacency with regard to owning downside protection, puts are now trading at their cheapest levels relative to calls in years.
SPY 2-month (Sept) 25-delta put/call skew is just above the cheapest levels in two years (bottom chart)
I believe investors should use this very attractive skew when either adding new long portfolio exposure at the highs, or if looking to potentially hedge some existing long exposure. An example of this trade would be something like this:
Sell SPY Sept 18th 800 calls
Buy SPY Sept 18th 750 puts
Costs ~ $2.35 (SPY 773.26 Fri close ref)
Trade Details:
- Selling the 3.5% (25d) upside calls to buy the 3% (25d) downside puts
- Selling the upside call covers more than 62% of the cost of owning those downside protective puts (speaks to the attractive put/call skew)
- SPY now at all-time highs, but was trading < 730 as recently as 7/29
- With VIX at these levels, I would expect to see both downside put vol AND skew to move up meaningfully should we actually see a decline (another reason why I like the low-cost collar trade here)
- Trade looks especially attractive if adding more upside exposure in futures or cash at these levels
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities
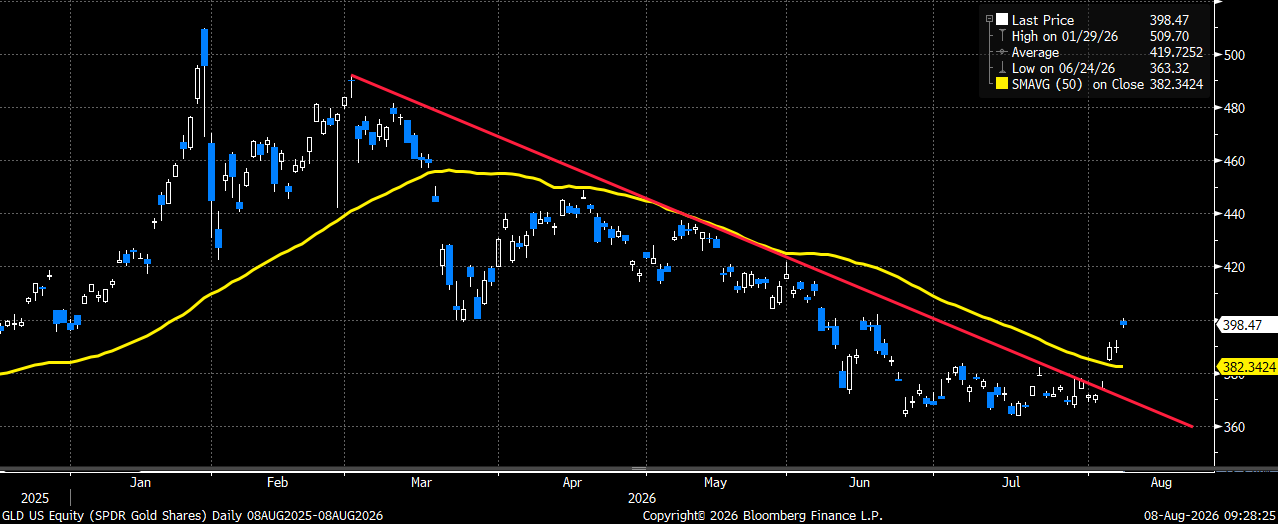
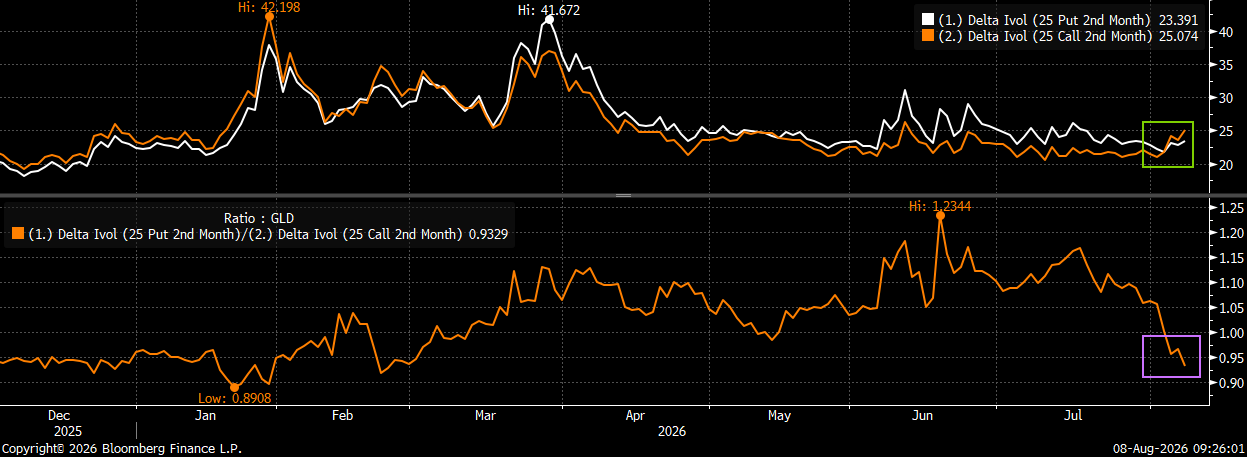
Favorable skew isn’t just showing up in the equity indexes, I am also seeing it in the commodity space. We saw a sharp breakout in gold this past week as the US$ continued to come under pressure (something I had suggested could happen in my note from 7/26 (here)). Now that the breakout has happened, we have seen a sharp move in the respective put/call skew as well. In fact, upside GLD 25-delta calls are now trading at a vol PREMIUM to the same delta downside puts (see below). While I do believe gold can continue to work higher, especially if the US$ continues to weaken, I do think adding these COSTLESS collars after the nice rally we have seen does make sense.
GLD with a breakout above the March downtrend as well as the 50-day moving average. Costless collars can keep you in the trade
GLD 2-month 25-delta calls are now trading at a vol premium to the 25-delta puts. Put/call skew has moved back to the lows (bottom)
Here is an example of a costless GLD collar I would now consider:
Trade:
Sell GLD Sept 18th 425 calls
Buy GLD Sept 18th 380 puts
Trades for ~ EVEN cost (GLD 398.47 Fri close ref)
Trade Details:
- Adding costless September collars in GLD following the 10% rally we have seen off the recent lows
- Upside calls now trading near their richest vol/skew to similar delta puts
- Selling the 6.6% upside call to buy the 4.6% downside put (speaks to the very favorable skew)
- Great add-on trade if you have caught this recent rally, or looking to add long exposure via futures or cash
- Please reach out to me or the 22V sales team for updated pricing and execution capabilities

