Back Quantitative

Quant Market in Numbers: Banks Kick Off a Strong 2Q26 Earnings Season

Published on July 19, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Sophia Wang

Kevin Brocks

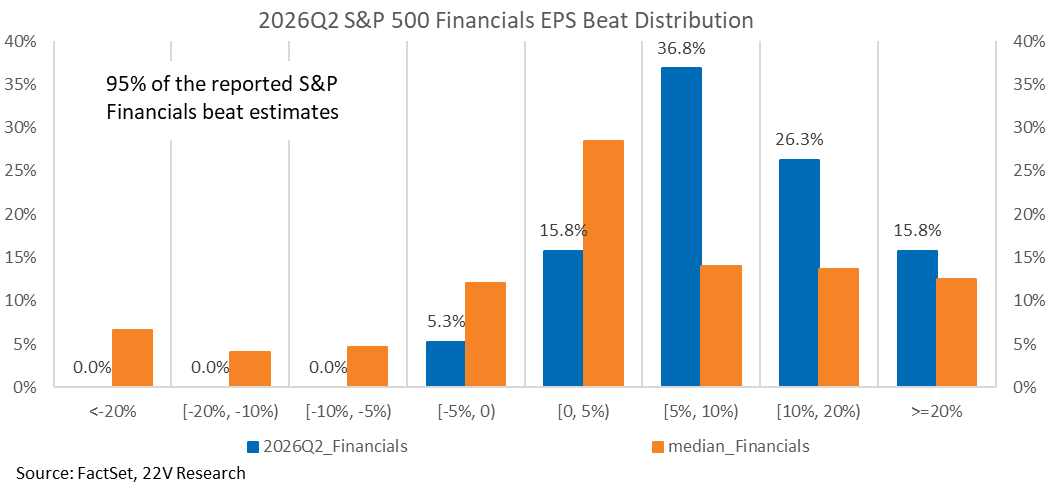
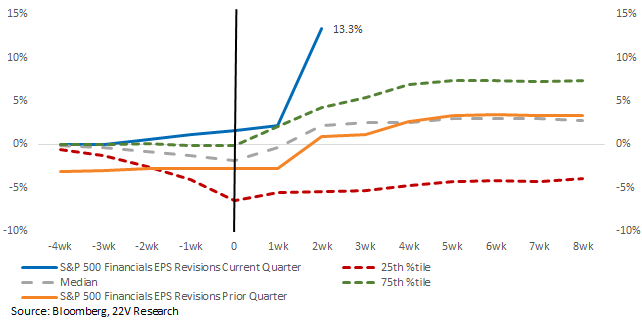
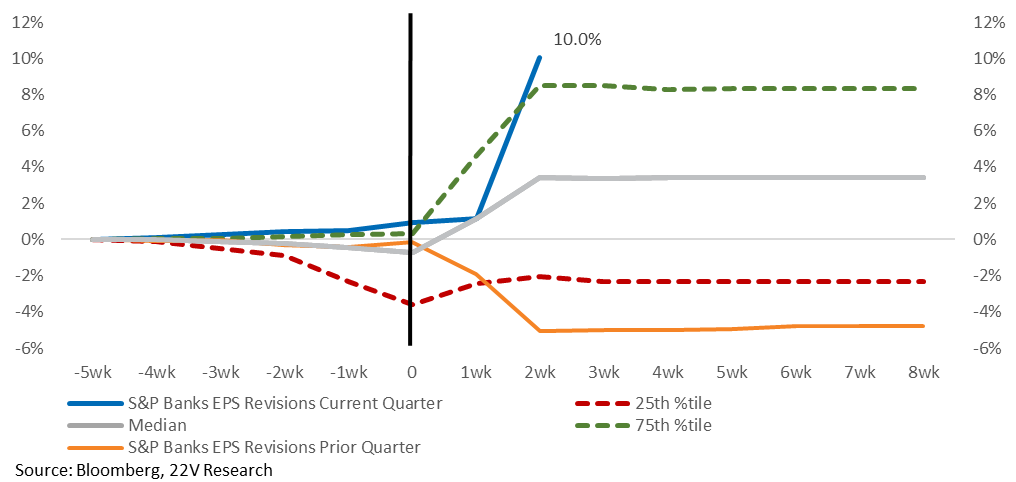
Ahead of the earnings season, Bill Hebel, Head of 22V Financials Research, highlighted (HERE) that positive earnings revisions, a steeper yield curve, and sector rotation are the three keys to banks’ solid performance this quarter. That has materialized. With 19 S&P 500 financials reporting in the first week of earnings releases, 95% of the names beat estimates with unusual strong revisions.

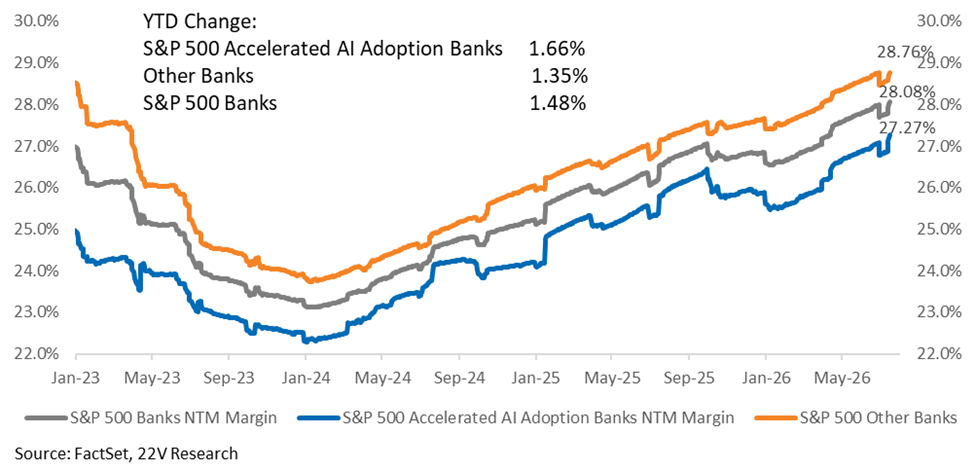
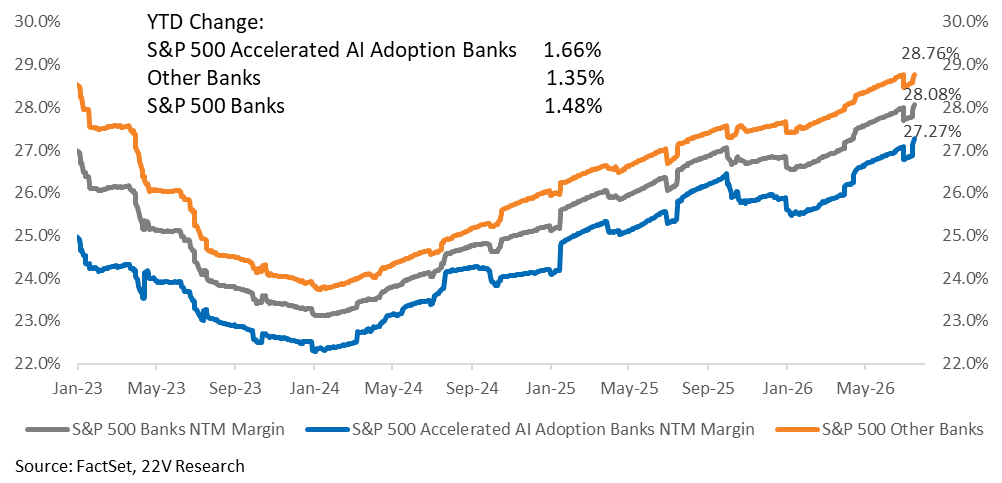
Banks Margins Remian Supportive. Forward looking and current margin sentiment expressed by Bank management remain at a high level, though the forward looking readings showed some weakness. Margins are trending higher across Bank, but names with higher AI adoption have seen margins improve more rapidly than those of other Banks this year. The absolute level of profitability for accelerating AI adoption banks is lower, but the strong margin trend is another sign that AI is moving from strategic narrative to operational reality. We list the current names in the AI adoption group in the report.
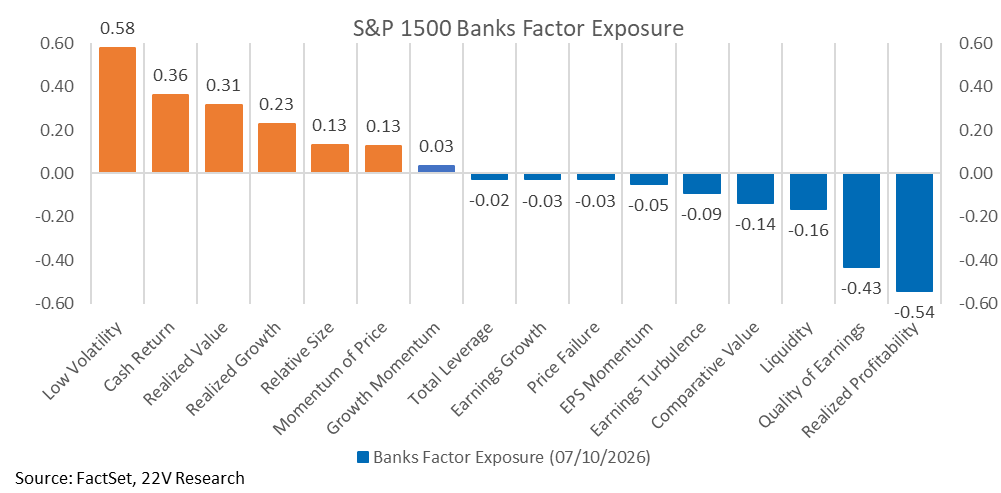
In addition to the fundamental tailwinds from margin sentiment and AI adoption, Banks’ factor exposure is a support for Bank performance. Currently, S&P 1500 Banks are most exposed to Low Volatility, Cash Return, and Realized Value, while carrying negative exposure to risk factors. This allows them to benefit from the significant rotations out of price momentum names.

There are 86 S&P 500 names reporting next week, the names with higher beat potential and higher miss risk are listed at the end of this report.

Banks Kick Off a Strong 2Q26 Earnings Season: Financial companies reporting in the first week of 2Q earnings season posted much higher EPS beat rates than normal. So far, 95% of Financials companies beat EPS estimates, well above the historical median of 72%, and positive surprises were skewed toward larger beat. As 22V Economist Peter Williams summarized in his early earnings season report (HERE), despite plenty of shocks, the early macro read from earnings season have been very strong.
A graph of blue and orange bars

AI-generated content may be incorrect.

In addition to the strong EPS beat rate, EPS revisions for S&P 500 Financials and Banks are unusually strong. The 13.3% and 10% EPS revisions for Financials and Banks respectively are both well above their historical 75th percentiles.
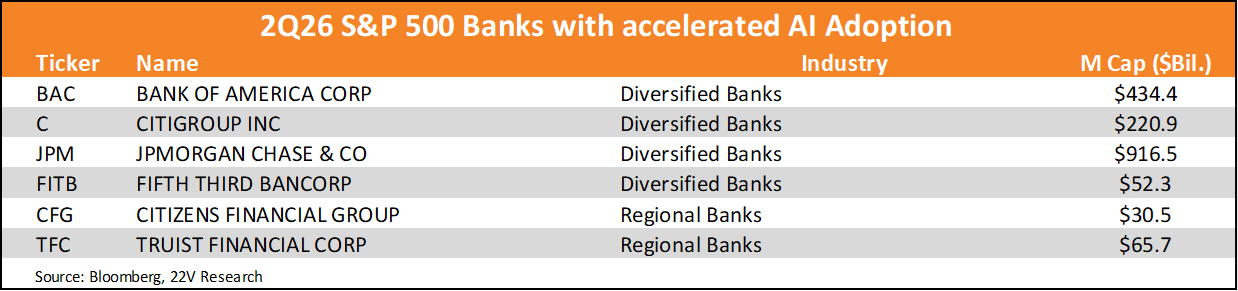
Beyond the strong headline numbers, a key focus within banks’ earnings transcripts this quarter is AI adoption. We used LLMs to identify bank names demonstrating accelerated AI adoption this quarter and list them below. Banks are flagged as “accelerating” based on their current quarter earnings transcripts and a prior two-quarter transcript trend review. A bank earns the acceleration tag when management commentary shifts from high-level AI references to quantified deployments, headcount productivity claims, or explicit cost-out timelines, and when analyst AI-related questions are rising in frequency, indicating AI is moving from strategic narrative to operational reality. For instance, Citi noted that nearly 9 out of 10 employees use AI tools, driving productivity, client experience and growth, bringing products to market faster; Bank of America says Over 200,000 teammates actively using AI-enabled capabilities across the company, ranging from productivity tools to agentic workflows and coding support.
A screen shot of a table

AI-generated content may be incorrect.

Accelerated AI adoption is also contributing to improving margin dynamics. Banks with accelerated AI adoption show a higher YTD change in NTM Margin compared to the broad S&P 500 Banks universe and their peers without accelerated AI adoption. The faster YTD margin improvement of the group has allowed them to narrow the margin gap with other Banks. JPMorgan CEO Jamie Dimon stated: “In a competitive capitalist world, we always use AI to do a better job for the customers, we can’t just say, oh, it’s going to increase our margins and going to keep that. If that were true, our margins would be 80% today, because of computerization over the last 20 years.” As Dimon notes, margin expansion is not a direct consequence of accelerated AI adoption, but it does help AI-adopting banks gradually close the NTM Margin gap relative to their peers.
A graph of a line graph

AI-generated content may be incorrect.

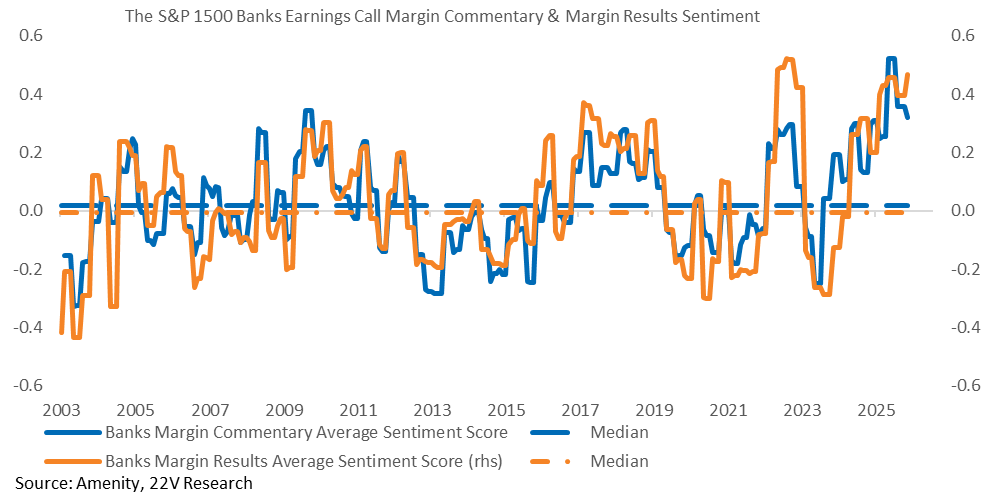
Currently, margin sentiment expressed by Bank management is supportive, reflecting strong bank confidence in current operating margins and the near-term outlook. While forward looking Margin Commentary Sentiment ticked down from its recent high, it remains above any level seen prior to 2025. Margin Results Sentiment ticked up, reaching its highest level since 2023.
A graph of a graph with blue and orange lines

AI-generated content may be incorrect.

Complementing the fundamental tailwinds from margin sentiment and AI adoption, the positive exposure to Risk-off and Value factors positions Banks well during current significant Price Momentum dispersion. Currently, S&P 1500 Banks are most exposed to Low Volatility, Cash Return, and Realized Value, while carrying negative exposure to risk factors, away from Earnings Turbulence risk two quarters ago (HERE). As we highlighted (HERE), Realized Value is an effective hedge against momentum risk. The factor exposure of S&P 1500 Banks therefore positions them to benefit from significant rotations out of price momentum names.
A graph of a graph showing the amount of banks in the banks factor exposure

AI-generated content may be incorrect.

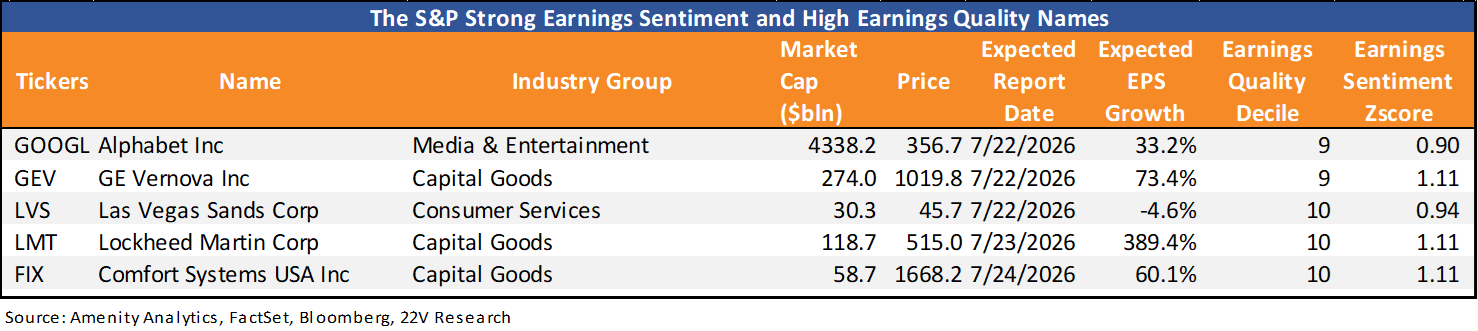
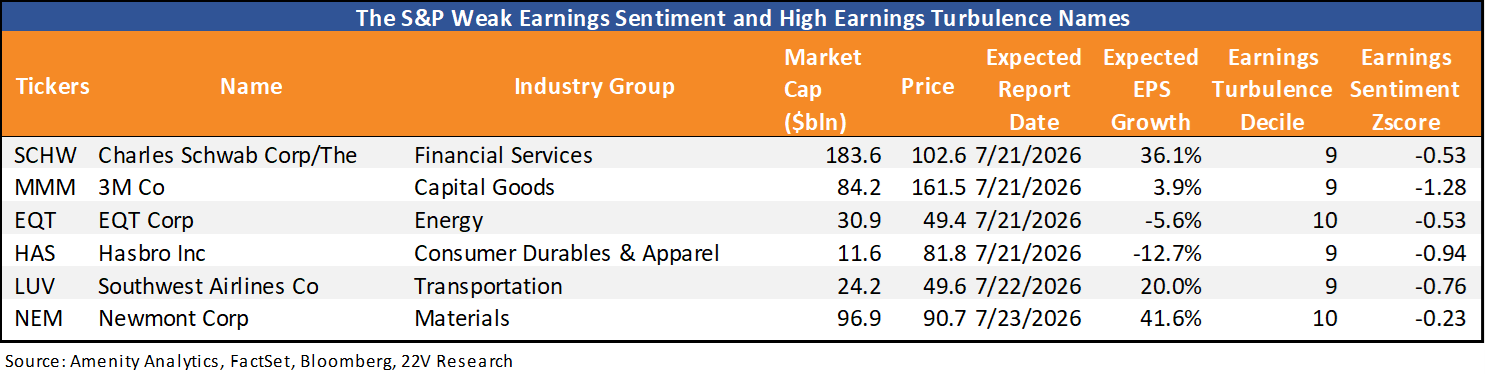
Week Ahead: 86 S&P 500 names are scheduled to report next week. Below we list the names falling into the higher beat potential basket. These names have high Earnings Quality and positive earnings sentiment scores. The higher miss risk basket contains names with high Earnings Turbulence and negative earnings sentiment score.
A screenshot of a computer screen

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.