Most early reporting Banks posted results that beat expectations. UCB, WAFD and RF were a few of the downside surprise outliers. The positive net surprise level suggests continued strong Financials earnings in 4Q. At the same time, earnings guidance by Banks dropped by -5.7% over past two weeks though, reducing the fundamental supports for the industry group.
As we discussed (HERE), Banks have one of the largest exposures to our Earnings Turbulence factor, and major Banks reporting earnings this week also have high Earnings Turbulence rankings based on our Earning Tracker (HERE). Since 2018, the returns of high Earnings Turbulence Banks have tracked changes in estimate for the group. Today, there is a growing divergence: Banks’ NTM EPS growth is slowing while high Earnings Turbulence Banks continue to outperform. That divergence signals a heightened risk of a short-term pullback
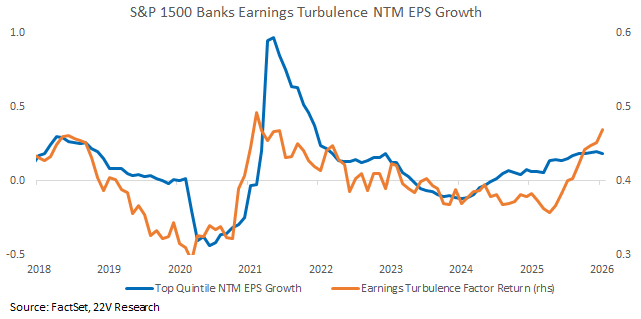
Based on current data, even slight earnings misses for stocks in the top quintile of Earnings Turbulence is likely to result in a growth rate that lags the factor’s return momentum. In this environment, investors are more likely to view even small beats as a disappointment relative to recent factor gains, increasing the likelihood of profit taking.
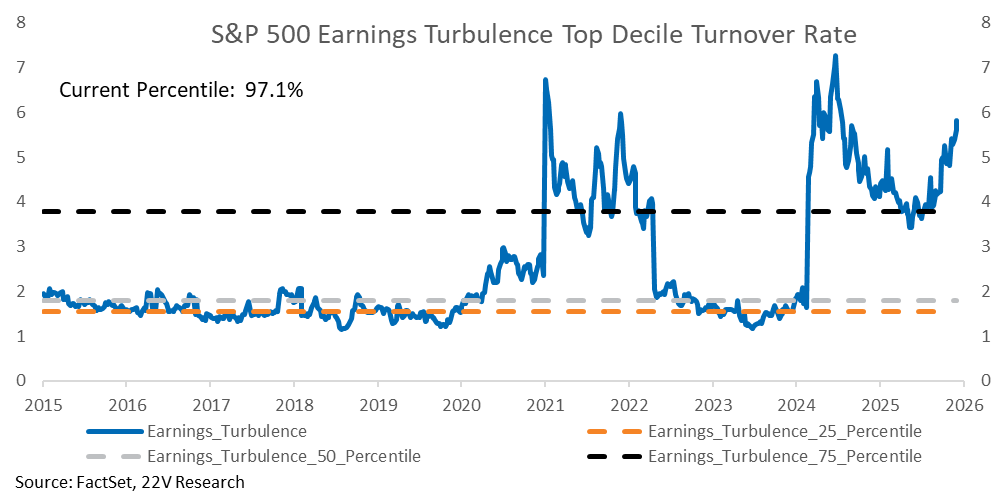
Currently, the top decile of the Earnings Turbulence factor basket is realizing a high turnover rate (97th %tile). The implication is that the highest-ranked names are being chased by investors. However, this high turnover signals also increase short-term risk, any drop in popularity could be accompanied by a sharp short-term sell-off. In short, High Turbulence is a crowded trade.
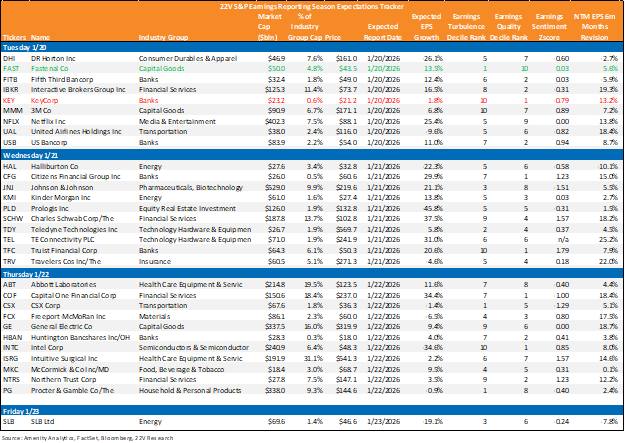
Longer-term we continue to like Banks and higher Earnings Turbulence names, but near-term risks are increasing. At the end of this report, we list the S&P 500 companies reporting earnings next week. We should pay particular attention to names in deciles 9 and 10 of the Earnings Turbulence Ranking. Banks and Financial Services remain the key components of the highest-ranked Earnings Turbulence names (including KEY, SCHW, TFC, NTRS). The risk of an “earnings beat followed by a sell-off” still exists for the second week of the earnings season.
Earnings Turbulence Risk Around Earnings: Most early reporting Banks posted results that beat expectations. UCB, WAFD and RF were a few of the downside surprise outliers. The positive net surprise level suggests continued strong Financials earnings in 4Q. Sentiment expressed by the management toward forward-looking earnings and current financials both moderated some but remain at firm levels. Earnings guidance by Banks dropped by -5.7% over past two weeks though, reducing the fundamental tailwinds that had been supporting the industry group.
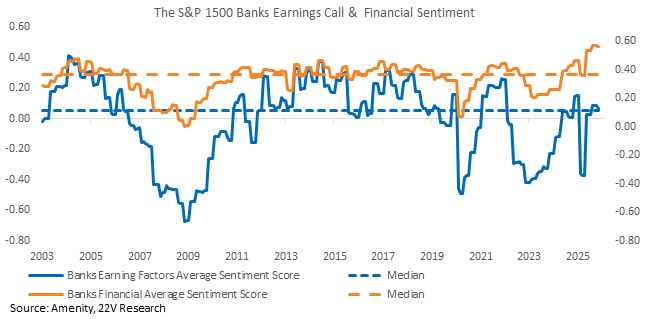
As we discussed (HERE), Banks have one of the largest exposures to our Earnings Turbulence factor, and major Banks reporting earnings this week also have high Earnings Turbulence rankings based on our Earning Tracker (HERE). Since 2018, the returns of high Earnings Turbulence Banks have tracked changes in estimate for the group. Today, there is a growing divergence: Banks’ NTM EPS growth is slowing while high Earnings Turbulence Banks continue to outperform. That divergence signals a heightened risk of a short-term pullback.
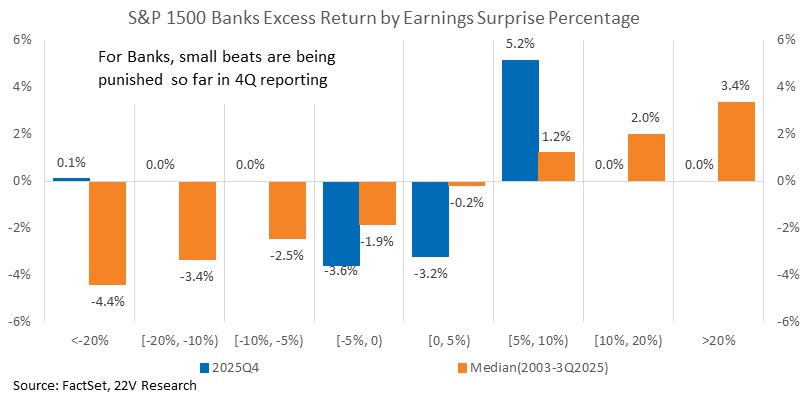
Based on current data, even slight earnings misses for stocks in the top quintile of Earnings Turbulence is likely to result in a growth rate that lags the factor’s return momentum. In this environment, investors are more likely to view even small beats as a disappointment relative to recent factor gains, increasing the likelihood of profit taking. For the early reported Banks, beats within 0-5% surprise led to negative excess returns. At the same time, beats above 5% saw much larger than normal excess returns. This is another sign of this being a stock pickers market.
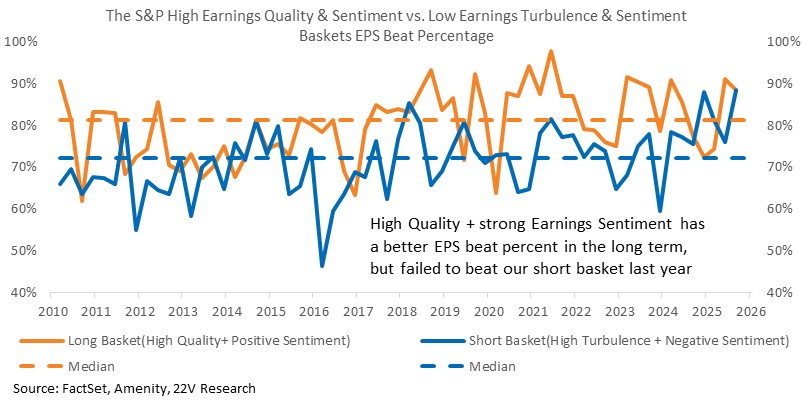
Historically, high Earnings Quality names with positive earnings sentiment have higher earnings beat rates high Earnings Turbulence names with negative earnings sentiment. Last quarter, the short basket reached a historically high beat rate of 88.6%, significantly above its long-term median of 72.3%. This spike partly drove last quarter’s Earnings Turbulence Rally. Since 2010, there has never been a period where the short basket’s beat percentage increased for three consecutive quarters. Consequently, companies with high Earnings Turbulence scores now face a greater risk of missing their EPS estimates.
Currently, the top decile of the Earnings Turbulence factor basket is realizing a high turnover rate (97th %tile). Increased turnover began in April of last year, lining up with the start of the Earnings Turbulence rally. The implication is that he highest-ranked names are being chased by investors. However, this high turnover signals also increase short-term risk, any drop in popularity could be accompanied by a sharp short-term sell-off. In short, High Turbulence is a crowded trade.
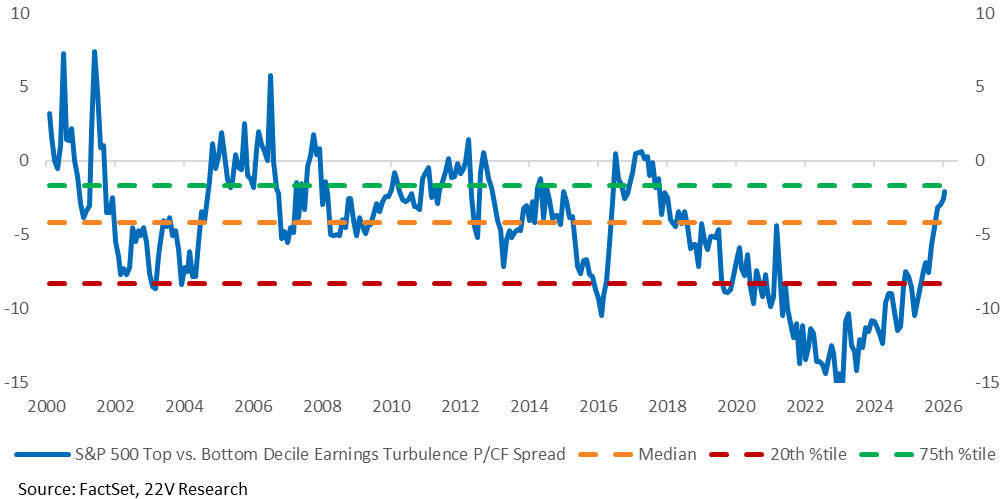
The valuation picture is also a growing concern. The premium that top decile Earnings Turbulence stocks command over the bottom decile, measured by their Price-to-Cash Flow spread, has surged to its ~75th %tile. Again, this suggests increased risk of a short-term pullback and greater headwinds around weak/negative earnings surprises for high Earnings Turbulence names.
Below are the S&P 500 companies scheduled to report earnings during the second week of 4Q25 earnings season, in addition to the beat/miss potential names indicated in the table. We should pay particular attention to names in deciles 9 and 10 of the Earnings Turbulence Ranking. Banks and Financial Services remain the key components of the highest-ranked Earnings Turbulence names (including KEY, SCHW, TFC, NTRS). The risk of an “earnings beat followed by a sell-off” still exists for the second week of the earnings season.