Bottom Line: Higher Yields
Higher yields will be more of a market headwind IF yields increase because of core inflation beats. We don’t expect higher than expected inflation readings in part because the labor market does not appear to be an inflationary impulse (HERE). Measures of slack have not tightened meaningfully (HERE). The standard inflation model would imply core inflation returning to target. The risk is that core inflation has been too hot without the inflationary impulse from the labor market. The bottom line is we need to following the data.
Relevant News: Inflation Data Risks
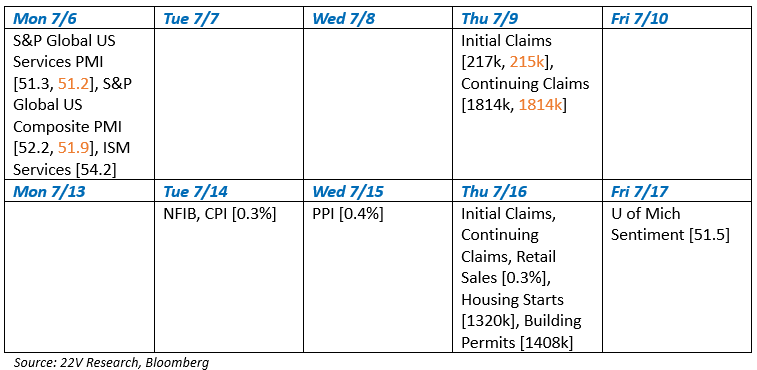
IF CPI and PPI releases next week imply >0.3% core PCE, yields are biased higher and there is downside risk to indices, Cyclicals, and risk-on factors (pure Momentum, high Earnings Vol, high Debt Risk, Unprofitable names). IF CPI and PPI imply <0.3% CPCE, it will reinforce our notion of a higher neutral rate, and there is upside to those factors even at current 10yr yield levels.
Things to Watch [Consensus, Results]:
Strategy:
Risks Ahead of Next Week’s Inflation Data – (HERE)
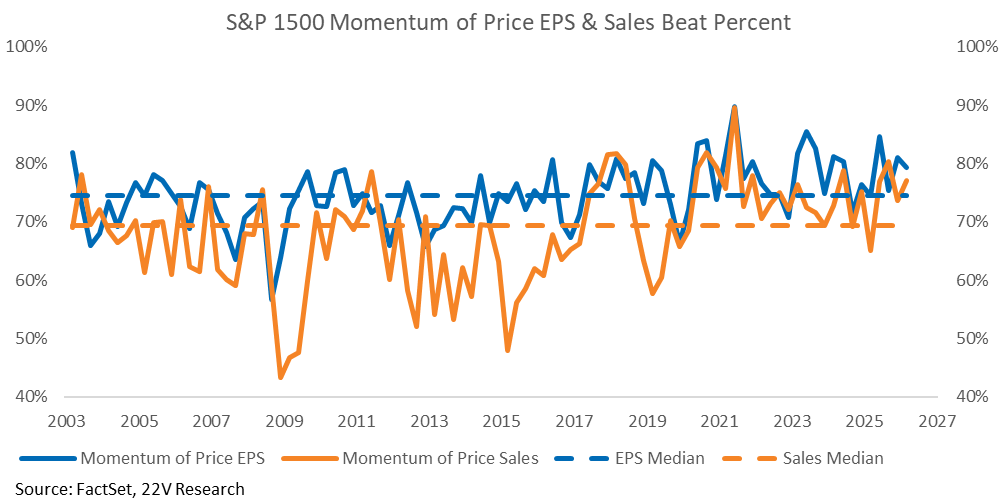
We prefer longs in fundamental factors (Growth, Earnings Momentum, Value, GARP) in the current economic backdrop (HERE). IF the inflation readings are benign, it may be interesting to look for longs in Momentum and high Earnings Vol heading into earnings though. The fundamentals for those groups, as a whole, have been extremely strong the past few earnings seasons. Sales and earnings beat rates have been well over the long-term median for the last four quarters. Strong results have been driven by the AI buildout (semis, in particular). We aren’t the experts in whether that will continue this quarter, but the macro will be more conducive to positive returns over earnings if inflation is benign.
Economics:
Warsh’s Task Forces are Full of Heavy Hitters– (HERE)
The leadership teams of each of Chair Warsh’s 5 task forces were announced yesterday. They feature well known economists, former policy makers, business leaders, and prominent investors. While there were some fears of politicization of the task forces, they are made up of subject matter experts with substantial credibility in the relevant areas and seem likely provide substantial input and debate fodder for the FOMC. The press release‘s summation of the broad mandates for each task force is clear enough, even if some of the specifics are still unclear: “they will operate independently, with a mandate to follow the evidence, provide candid feedback, and produce rigorous findings for the Federal Open Market Committee.” Peter provides thoughts on each task force HERE.
Financials:
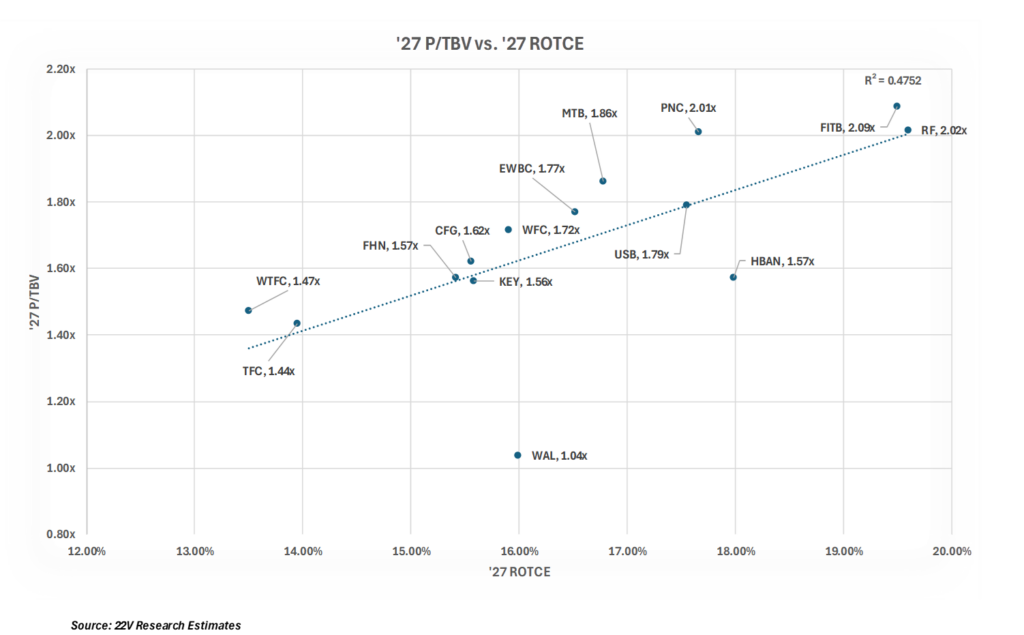
MidCap Regional Bank Preview – Continue to favor East West & Wintrust– (HERE)
Regional banks enter 2Q with strong momentum after investors gained confidence from resilient loan growth, benign credit trends, improving capital markets activity, a steeper yield curve, and stable deposit pricing, driving meaningful outperformance in the group. The constructive backdrop can continue, but sustained leadership will depend on positive earnings revisions, continued balance sheet growth, and a yield curve that remains supportive without forcing the Fed into an aggressive hiking cycle. Within the group, EWBC and WTFC remain preferred names given stronger loan growth and earnings outlooks, while FHN and WAL are viewed more neutrally as investors monitor funding costs, deposit trends, and execution on profitability initiatives.