2Q Preview
As we look at the mid-cap space, we feel like there is the opportunity for continued dispersion given the diversity of business models.
Our Sector Outperforms:
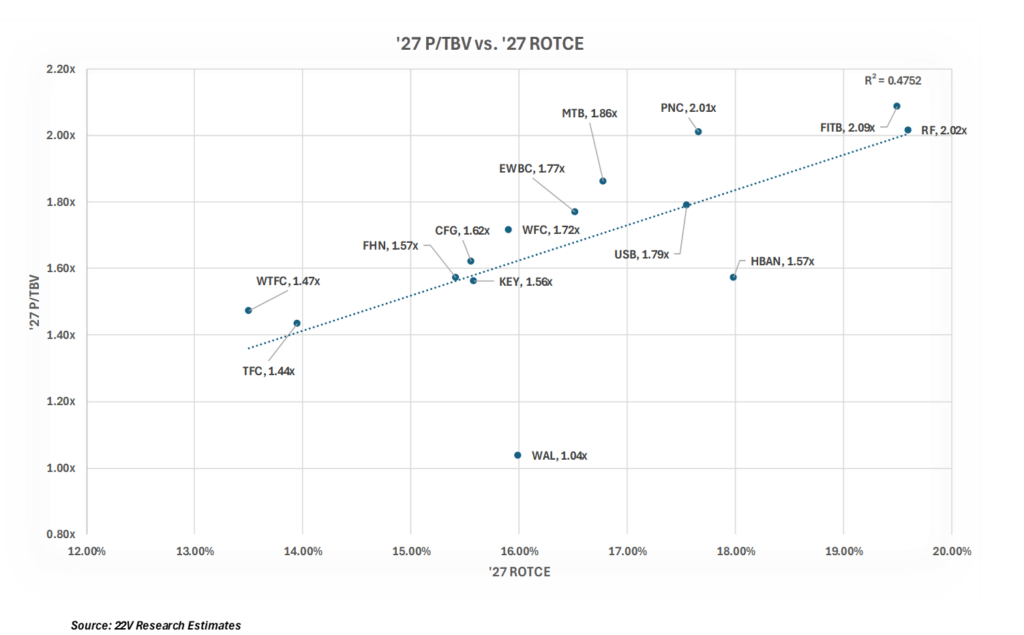
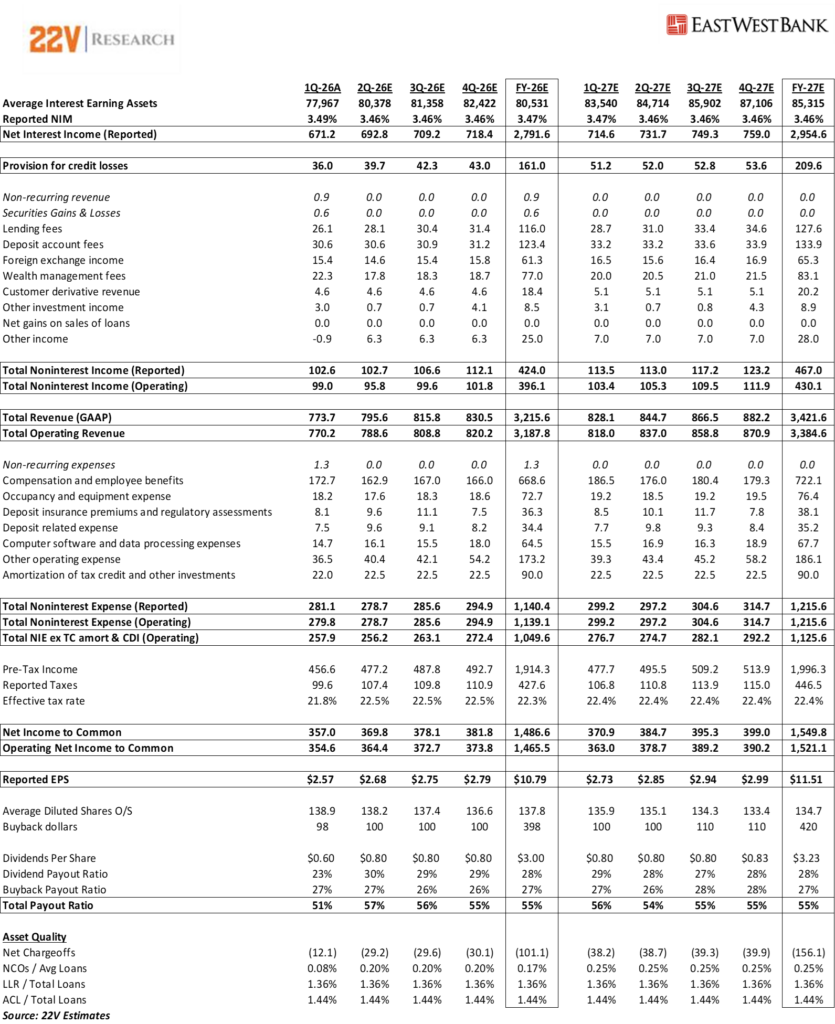
East West Bank (EWBC): On a PTPP/share basis, we’re 0.6% ahead for the Q, 0.2% for FY’26 and 1.5% for FY’27. We feel like there’s been some consternation around the NIM guide for 2Q with management reiterating the commentary around making the day count adjustment for the NIM before applying the “flat to slightly positive” guidance from last Q’s earning’s call. When we make that adjustment, we are reaching the consensus 3.46% NIM with better loan growth taking our NII above consensus expectations. We do take into account the fact that the CD roll on rate is ~3.60% and bring our deposit costs up accordingly for the remainder of the year. That said, we’re still exceeding consensus and the 6-8% NII guide for the full year (we’re at 9.4%) thanks to better earning asset growth. We leave our FY’26 estimate unchanged at $10.64 and trim FY’26 by $0.02 to $11.30 due to a higher stock price (fewer shares bought back for the same proceeds). We raise our target to $141 from $133 or ~12.5x our ’27 estimate. We continue to like EWBC for their strong asset growth, superior efficiency ratio and very strong capital ratios which continues to provide EWBC with significant optionality. We reiterate the Sector Outperform.
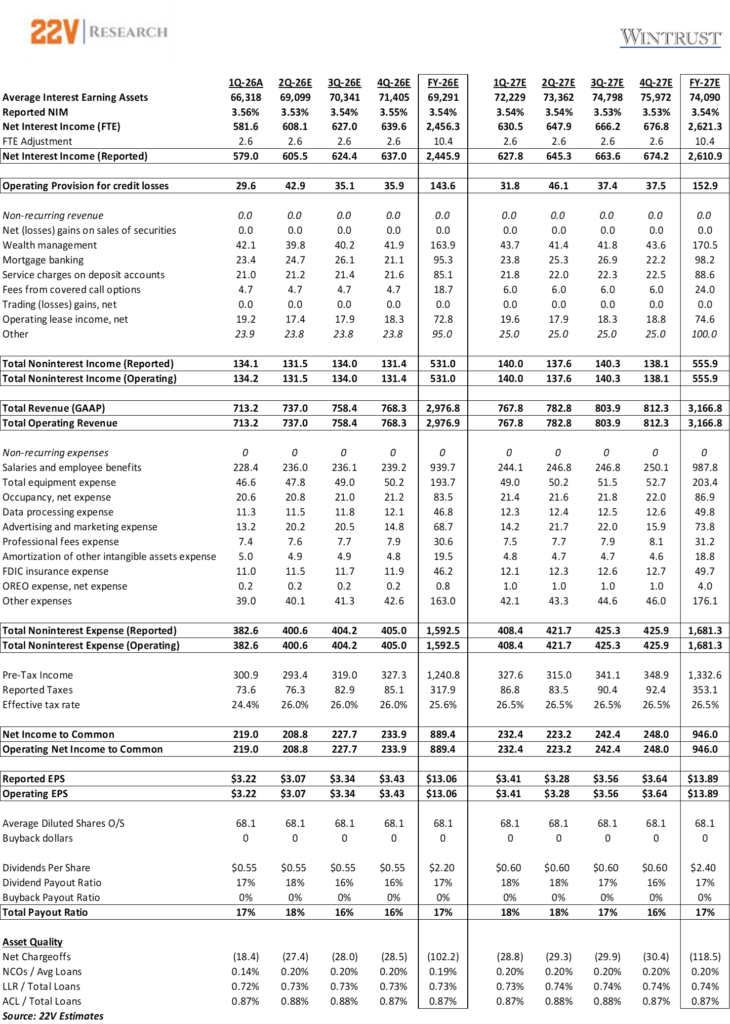
Wintrust Bank (WTFC): On a PTPP/share basis we are 0.5% ahead for 2Q, and 0.9% ahead for FY’26. We are in line for FY’27. Like EWBC, we see WTFC outperforming on balance sheet growth in both years helped by the insurance premium finance business which drives our NII above consensus. Our FY’26 & FY’27 estimates of $13.06 and $13.89 are unchanged. We’re raising our target from $167 to $174 or ~12.5x our FY’27 estimate. We reiterate the Sector Outperform.
Our Sector Performs:
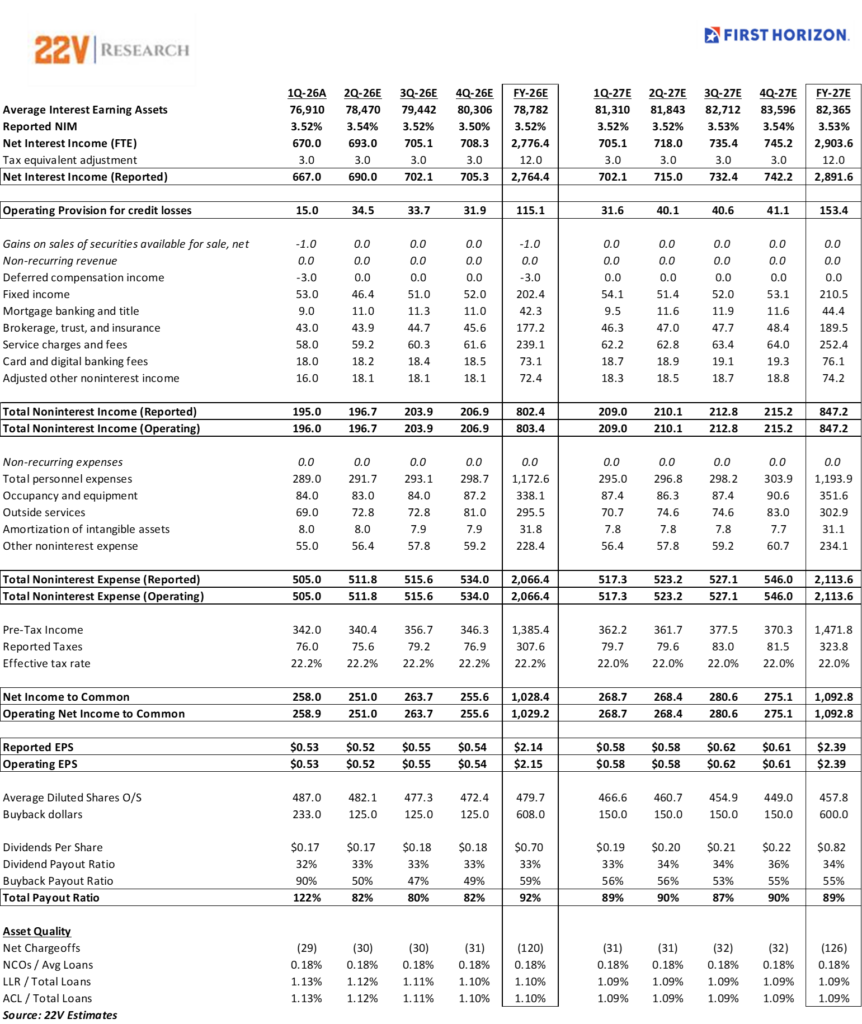
First Horizon (FHN): Given management’s commentary around a slower uptake in mortgage warehouse in Q2, we believe some of the wholesale funding will not be necessary to support the warehouse in 2Q before it begins to move up again in 2H’26. This should have a positive effect on the NII/NIM dynamic this Q. We’re actually modeling the NIM up a few bps which is decently above consensus which is more matching the flat to down guide the company gave after 1Q earnings but before the weaker mortgage originations were discussed at later conferences. Those weaker mortgage volumes/weaker fixed income markets are having the effect of depressing the average daily revenue trades at FHN which are running in the high $500k/day vs. $742k/day in 1Q. First Horizon often talks about the holistic approach they take to the balance sheet where they run a bit asset sensitive as a hedge to the fixed income businesses. As such, it would stand to reason that NIM/NII could outperform while our #’s did in fact come down for the fixed income business. In sum, we are ~1.9% ahead on PTPP/share this Q and roughly in line for 2H’26. We’re 1.4% ahead on PTPP/share in FY’27. We raise our FY’26/FY ’27 estimates from $2.14/$2.34 to $2.14/$2.39. We’re tweaking our target to ~11x our’ FY’27 estimate or $26.50 up from $26 and reiterate the Sector Perform.
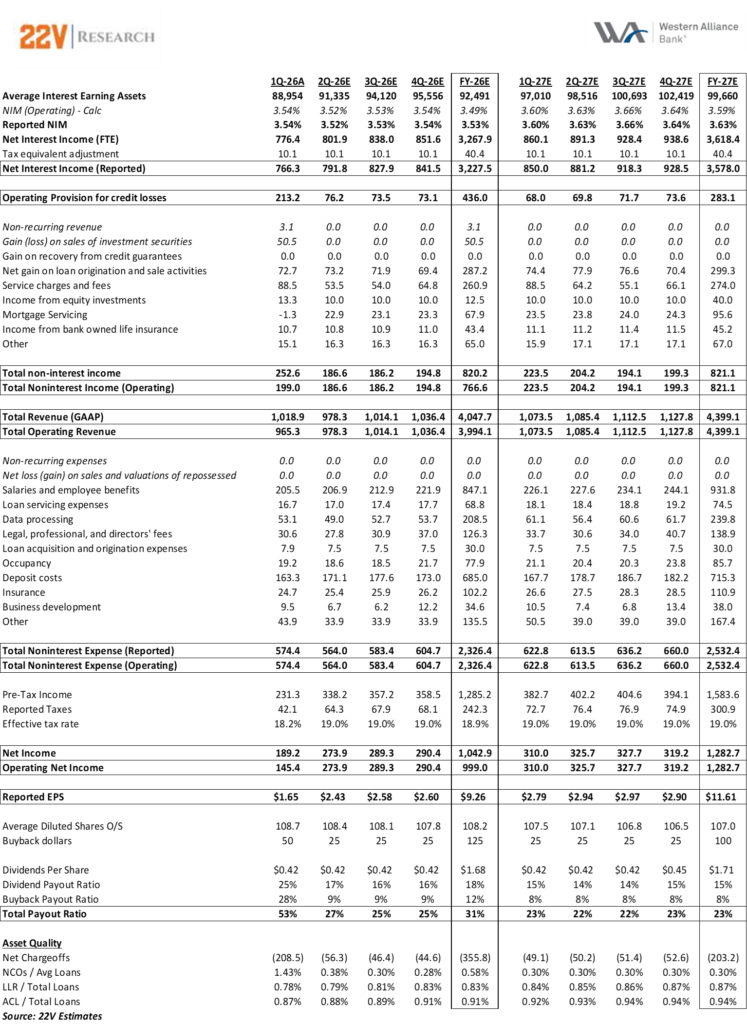
Western Alliance (WAL): Post investor day, we sense a renewed focus on deposit costs and the creation of new low cost deposit verticals. We believe that while the new initiatives will take time, in theory they will lessen the reliance on higher cost funding to fund the mortgage warehouse business. While we do have a 1.9% PTPP/share beat in 2Q on better fees/lower expense, our model confidence is low given the degree of moving parts. For FY’26/FY’27, we’re 1.6% and 1.1% below consensus PTPP/share. We bring our FY’26 & FY’27 estimates down from $9.65 & $11.77 to $9.26 and $11.61 respectively. We think WAL needs to continue to work on the deposit cost initiatives if they want to create a durable re-rate in the stock. Continue to rate a Sector Perform with a $96 target.