Back Shoot Around

22V Afternoon Shoot Around: YTD Winners, CNY Headwinds, and Banks Update

Published on June 24, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: Price Momentum Drawdown

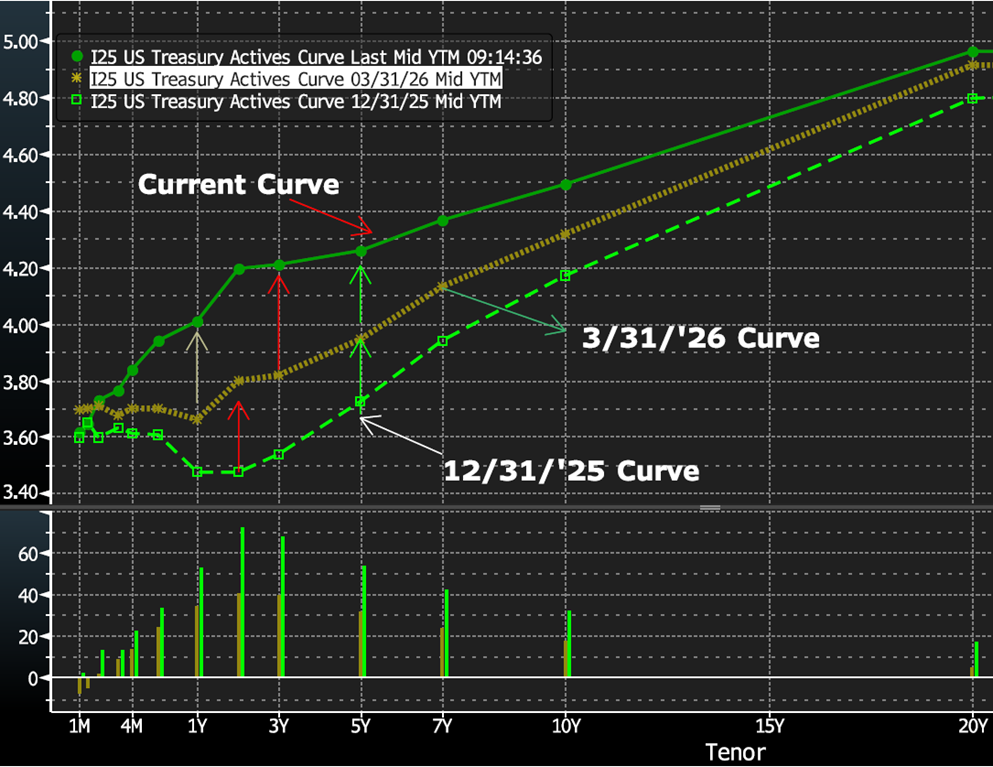
For those looking for direct MACRO signals on what would cause a larger and more sustained drawdown in the Price Momentum Factor and YTD S&P 500 winners, keep an eye on the 2yr yields. If the 2yr yield breaks meaningfully above the 4.2% level (so heading toward 4.3-4.5%) it would likely be associated with hawkish economic data that forces the Fed to hike rates. The drawdown could be severe given the unusually high level of volatility in the concentrated group of YTD S&P 500 winners and the Price momentum factor.

Relevant News: Index Return Stats

Just 16.9% of S&P stocks (by count) explain 80% of YTD index returns. That is the lowest reading since 1990 and below the Dot Com reading. Contributions from Price Momentum confirm the concentration of returns. The rolling 3mos average of Tech and Deep Cyclicals (Energy, Materials, and Industrials) account for roughly 40% of top decile Price Mo names.

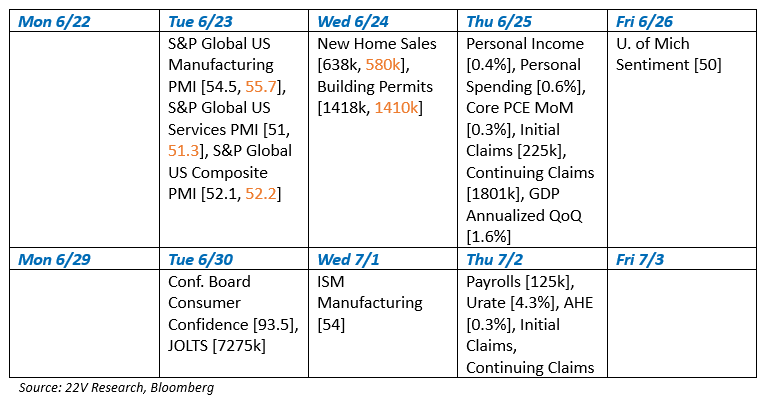
Things to Watch [Consensus, Results]:
A screenshot of a table

AI-generated content may be incorrect.

Strategy:

Extreme Volatility in YTD Winners Makes it Difficult to Manage Risk– (HERE)

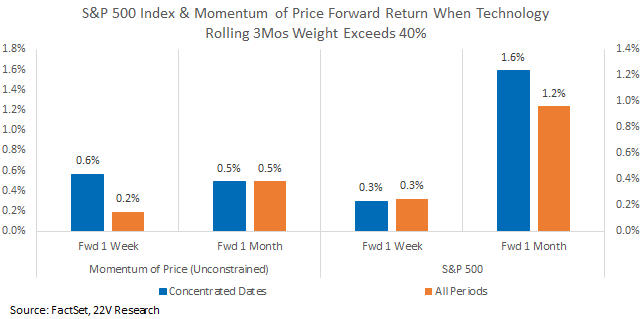
The S&P 500 names that have contributed the most to S&P appreciation this year have 1mo realized vol in the 99th%tile going back to 2010 and 97th%tile on a 3 mos basis back to 2010. The price momentum factor vol is above the 95th%tile and single name stock vol is at the highest level ever relative to S&P index vol. History suggests that such concentration does not necessarily signal an imminent reversal. When Price Momentum is being driven by a narrow set of names, forward 1 week and 1 month returns have been better or roughly in line with all periods for both the Price Mo factor and the S&P Index.
A graph of a graph showing the amount of a number of percent

AI-generated content may be incorrect.

China:

Headwinds for the CNY– (HERE)

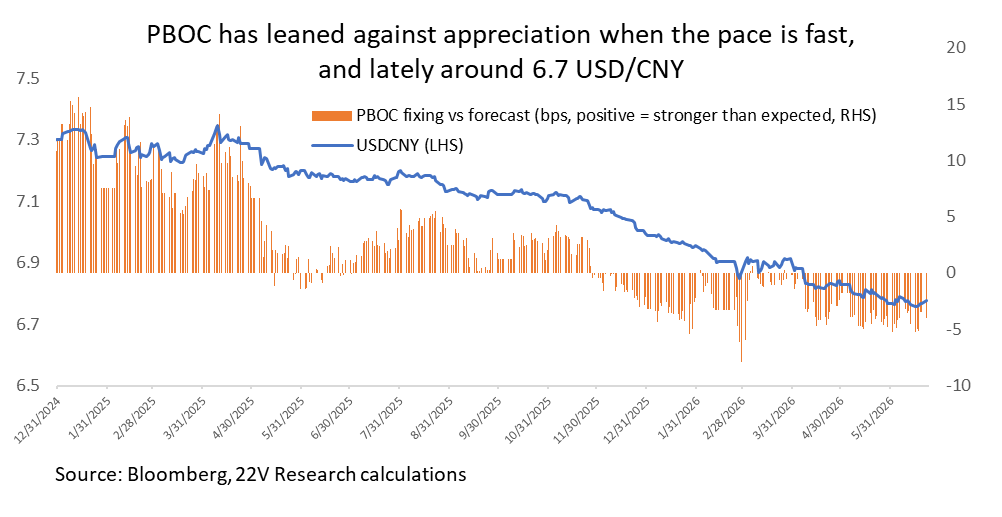
The recent 4% appreciation of the CNY has exceeded expectations, but the strengthening trend is likely to stall as China faces slowing domestic growth, likely monetary easing, and tighter controls on capital outflows, all of which weaken support for the currency. While China’s large trade surplus and concerns about CNY undervaluation have increased international pressure (particularly from Europe) meaningful policy action to force appreciation remains unlikely. Beijing is more inclined to address trade imbalances through measures such as reducing export tax rebates rather than allowing significant currency gains, and the prospect of a Plaza Accord-style agreement is remote given China’s distrust of such arrangements. As a result, there is a meaningful risk that USD/CNY ends the year above the market’s current expectation of 6.7.
A graph of a graph showing the difference between a graph and a graph

AI-generated content may be incorrect.

Financials:

Thoughts from the Road – Changing rate paths, deposit concerns and receiving clarity on Clarity – (HERE)

Banks are benefiting from a higher 2–5 year lending curve, which has improved loan yields faster than deposit costs have risen, supporting both NII growth and profitability. With loan growth accelerating, balance sheet expansion is becoming a more meaningful earnings driver than fixed-asset repricing alone. While potential Fed hikes and higher deposit costs remain risks, any tightening is expected to be gradual, giving banks time to manage deposit betas. The outlook for the Clarity Act remains uncertain and delays would likely be viewed positively by the industry. USB remains a preferred name given strong NII and fee growth trends, favorable curve exposure, improving deposit mix, and a path toward a 3% NIM by YE27.
A graph on a black background

AI-generated content may be incorrect.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.