DAILY STRATEGY: The readthrough from core CPI to core PCE, which is how CPI influences policy, was less friendly than CPI looked on the screen. Core PCE tracking estimates shifted a bit higher after the release (HERE). The single best measure of core PCE (excluding non-market prices and swapping out lagging government rents for private rents data) was running at 2.7% (ar) during May. As Gerard put it (HERE), “Another baddish month, but probably not something to force the Fed to go in, say, July.” More details will come after PPI this morning.
The framework for equities remains the same. The risk of higher implied real rates (rates – inflation expectations) is weighing on Price Momentum (HERE). Ultimately, if and how much financial conditions must tighten and growth needs to slow depends on the Strait of Hormuz (SOH). Without the supply shocks, inflation remains low enough that a significant tightener is not warranted (HERE). However, the SOH news flow this week is not allaying concerns. The US and Iran exchanged fire again overnight (HERE).
FYI, Jacob Kirkegaard, 22V’s geopolitical expert, believes these “tit-for-tat” strikes do not materially change the direction of travel towards resolution. As he puts it HERE, “The new situation of generally more frequent shooting with “larger caliber weapons”, while avoiding a complete breakdown of the ceasefire, is not uncommon during active peace negotiations conducted “while the shooting still goes on”.”
CPI did not change the influence of idio risk on returns, which is elevated right now (HERE). Dauvin Peterson, head of 22V Data Infrastructure/Commodities Research, noted the recent performance of AI baskets indicates more concern over AI cost pressure and timing of capacity coming online. There have been announcements about data center developers pausing projects (HERE), frontier models competing on price (HERE), while AI buildout baskets (power, memory, compute, neoclouds) are significantly underperforming week over week. AI buildout baskets do worse when there are concerns that AI ROI is under reconsideration.
ORCL reported after the close yesterday. ORCL’s higher-than-expected data center spending looks to be feeding into concerns over cost. Dauvin notes two relevant pieces: “First, spending numbers are moving higher and commentary or responses around cost inflation were squishy. And secondly, they expect margin pressure as they roll out large AI data centers.”
Charts…
Estimates for Core PCE shifted up to +29bps. These estimates will firm up and more details on the goods vs services split will be available after PPI this morning.

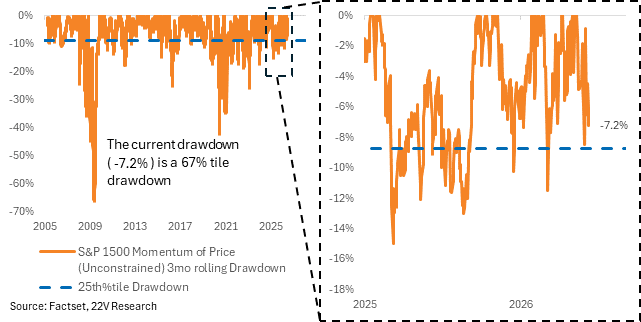
The drawdown in Price Momentum is now -7.2%, a 67th percentile drawdown.
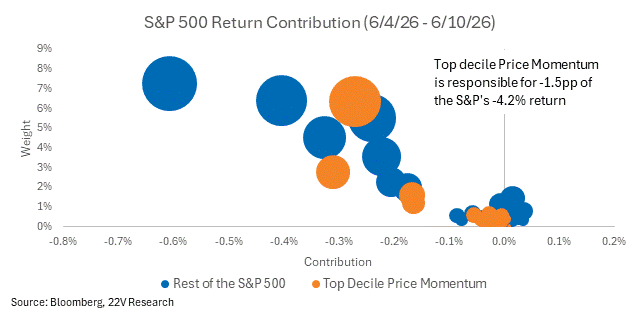
Price Momentum is contributing -1.5pp to the S&P 500’s -4.2% return since pre-Payrolls.