

The Emerging 2026 Growth Narrative and Refreshing the 2025 One
- Tariffs, those imposed and the uncertainty and volatility created by the whole process, remain a somehow underappreciated sources of drag on the economy this year.
- Many are willing to discount the AI boom’s contribution to growth but fail to account for the downside drags of tariffs this year, taking the realized toplines (still solid on their own) and netting out AI leaving an overly pessimistic view of the economy.
- The consumer continues to be healthy. Spending has accelerated and broadened out since in H2 as tariffs have faded off the front-page. Recent bank, card, and consumer names continue to support this view. Much more tentatively, some labor market trends look to be steadying themselves since the fall. It is important to remember that labor slack lags activity and hiring intentions.
- Given strong domestic demand trends and a lack of household and corporate financial vulnerabilities, combined with fading tariff impacts and fiscal stimulus, 2026 outlooks remain somewhat too pessimistic.
In recent weeks, market internals have moved towards a more growth positive and less purely AI-anchored view. The trough in Fed pricing has moved up appreciably too as left-tail labor market concerns have faded some.[1] This has been accentuated by a global shift toward rate cutting cycle pauses; a few high-beta curves now suggest possible hikes next year. Long-term rates have similarly been moving up globally as inflationary concerns, procyclical fiscal stimuli, and fading recessionary worries jointly pressure term premia and expected rates higher.
The recent inflections higher across many consumer names and very positive revisions guidance this fall, along with the macro data in hand so far, are starting to suggest a new narrative as left tail concerns fade (in line with my analysis of ADP and other alt labor data last week). Conversations with investors certainly have a different tone in recent weeks than they did for much of the fall.
In trying to tell a broad narrative of the data over the course of a very noisy 2025 one must necessarily be cautious. It has been an extremely volatile year for the macroeconomy and firms with the labor market easing even as consumption has surprised to the upside and consumer credit trends improved.
But missing in much of the discussion recently is the key driver of the year’s economic volatility: tariffs. Comments today from the head of JPM’s consumer business caught my attention and seemed to sum up the point quite well: “obviously, the tariff situation has panned out to be not as significant — certainly significant, please don’t get me wrong, but not as significant as initially worried. Various different businesses are adjusting in various ways… And on the whole, I think keeping themselves in pretty good shape so far.” The ebb and flow of tariff-driven caution and uncertainty is a/the key variable in this year’s macro story; given it’s impact and fundamentally exogenous cause it is essential to keep in mind when analyzing the data and projecting it forward.
In late 2024, despite the Sahm Rule scare, much of the economy seemed to be starting to exit its multi-year cyclical doldrums. After a partially artificial pop following the election, tariffs substantially weighed on sentiment, spending, and hiring intentions during the spring and early summer. It remains underappreciated ex post, particularly with markets at or near all-time highs, just how distortive and risky the tariffs themselves and their uncertainty were for normal business. However, with tariff tail risks decreasing, net tariffs impacts are likely peaking now or behind us, and anti-recessionary fundamentals[2] remaining in place, things have started to pick up since the early fall. This can be seen across card spending in Q3-on, much corporate commentary outside some restaurant and housing names[3], and the continued outperformance of topline growth measures and expectations revisions higher since Q2.
In this causal story of the economy, domestic momentum remains solid, around substantially slower labor supply growth and continued post-pandemic job churn whipsaws, with tariffs the primary driver of the year’s downsides and risks. Along with stimulative fiscal policy and easing credit and financial conditions, this means that growth expectations for 2026 remain broadly too sluggish (see more from a few weeks ago here).
The shutdown will weigh on 25Q4 and inflation poses a tactical risk to real growth in Q1 (even with very strong nominal growth above expectations inflation may dent real outcomes). However, these are noisy whipsaws around strong underlying domestic momentum.
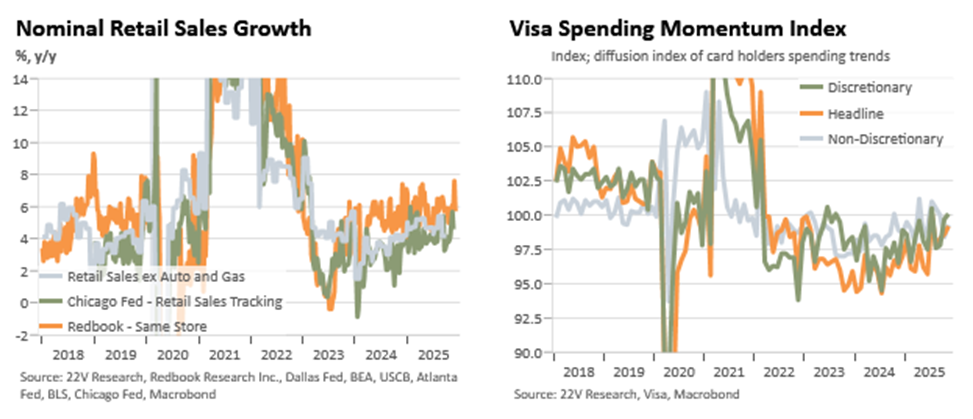
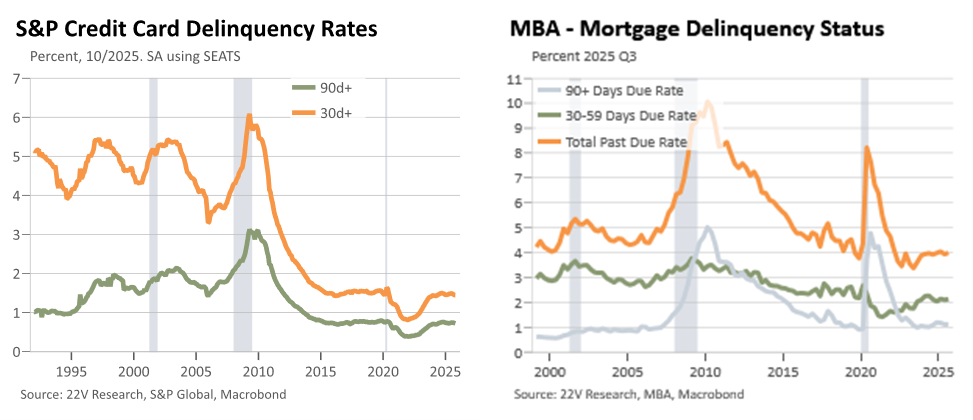
Commentary from a banking sector conference today, most helpfully from both SYF (lower-end) and JPM (higher-end), reinforces the point that strong consumer spending momentum has continued and even accelerated a bit into Q4. In data which is as timely as it gets, the spring-summer weakening in NFP growth does not seem to be driving broader consumer softness. SYF noted that “the momentum that we saw in the third quarter has continue” and “[spend and frequency is] improving across all credit segments.” JPM struck a similar tone; “spend in the 4th quarter improved a little year on year and relative to the first three quarters of the year.” As a reminder, JPM card spending growth was already at +9% y/y in Q3. Visa’s monthly spending momentum index, a diffusion index of card holders, has shown discretionary consumer spending growth broadening out this fall. On the credit side both reported good trends as they continue to see “both charge-off and delinquencies trend down” (JPM) and “”we’re really pleased with credit… better than seasonality” (SYF). While a sharp easing in the labor market would put these trends in jeopardy, it is worth remembering that baseline-like levels of a bit more labor market easing have been taking place for some time even as these trends has been improving.
Much like we saw in spring 2023 and fall 2024, there is fairly rapid decay on nonlinear risks in the economy after they rise to the forefront; either the risked or supposed nonlinearity triggers sufficient weakness to accelerate a worse move or the same more-linear trends continue apace. The issue may really just be the US private sector lacks the vulnerabilities to catalyze these usually sufficient shocks into something broader. This is particularly true when the central bank acts to head them off (the alphabet soup of post-SVB emergency facilities, risk management cuts in 2024 and 2025). ↑
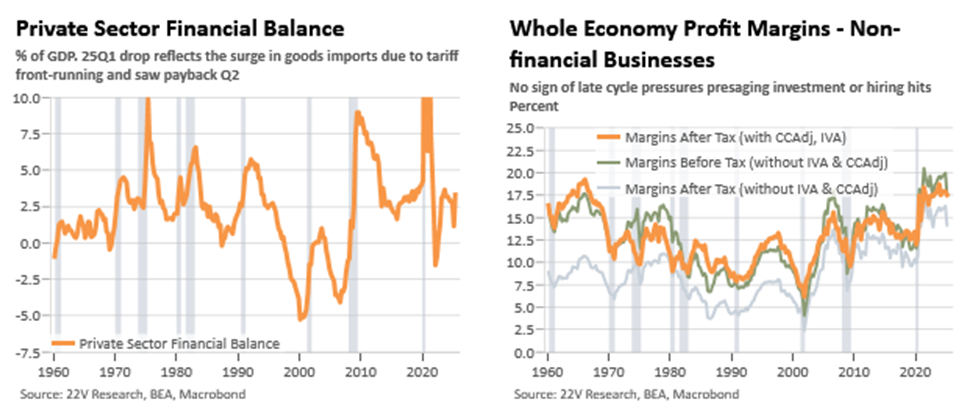
What I mean by this term is the health of household and non-financial corporate balance sheets, consumer and corporate delinquency trends being flat to down, the private sector financial balance is sharply positive and not deteriorating, and corp margins have shown no signs of the usual multi-year pre-recessionary deterioration. ↑
Even in the housing sector many names are suggesting that the second bottom for the sector is now in with comps expected to be flat or mildly up next year. ↑

