SUMMARY: Company earnings sentiment, measured using the Amenity language processing tool “listening to” and objectively scoring every earnings call, shows S&P 500 earnings sentiment has rebounded from its 2Q dip. Forward outlooks for margins are once again optimistic. What companies are saying fits with the strong productivity backdrop we highlighted over the weekend (HERE). Alternative labor market data and the Challenger job cuts released yesterday suggest ADP is overstating labor market weakness. We have no reason to suspect a weak earnings season at the index level, based on what management teams are saying about their own company trends.
Bottom line – Firm economic activity data and anchored long rates continue to drive market internals. Expect riskier factors (Momentum, EPS growth, Small size), and interest rate sensitives (Biotech, Housing, Debt Risk baskets) to benefit. Longer term, the interest rate sensitive group should be faded as the economy continues to expand and the labor market stabilizes (Momentum, AI, Consumer services still work). 10-year yields will move higher if that happens, but are not an issue for risk assets. Internals are where higher yields impact the market. Firmer labor market data is needed before we can monetize that theme. Stay long the Earnings Risk and Short Low Vol (Staples).
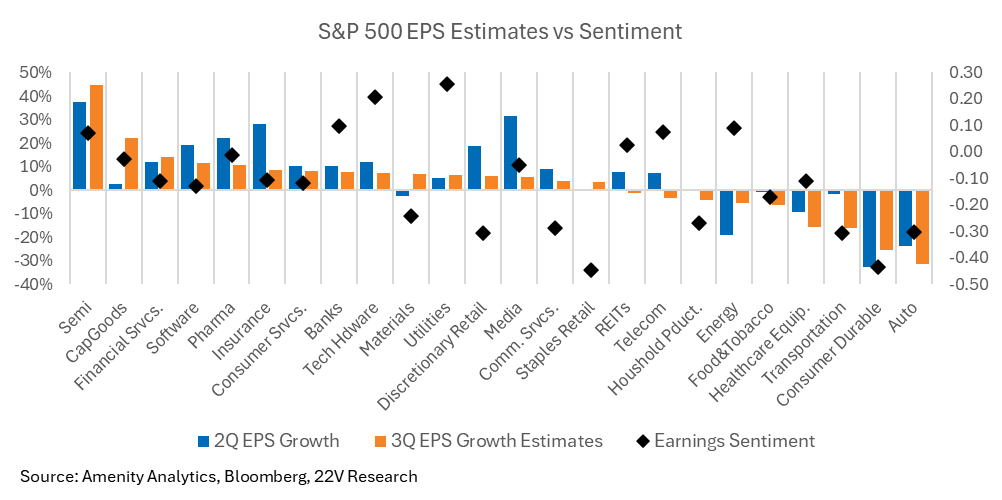
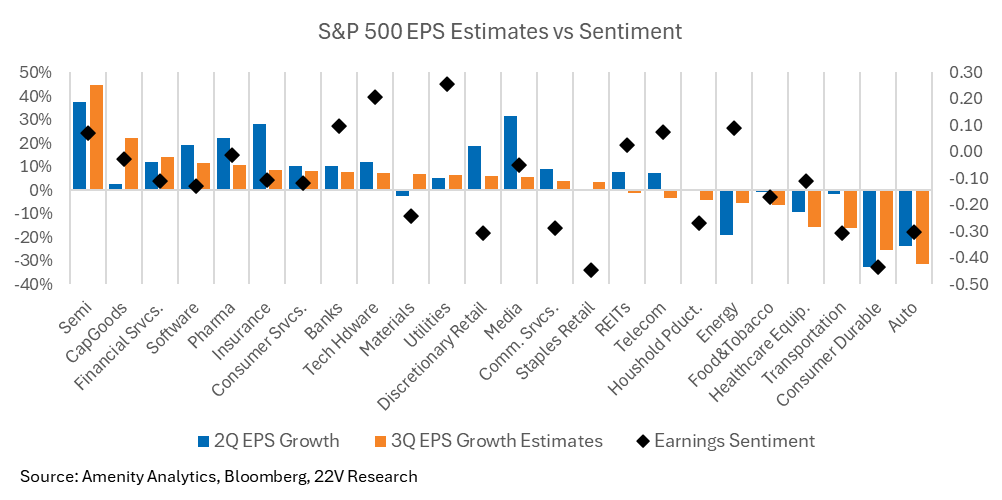
Some interesting sector observations popped up when we compared analyst expectations to corporate sentiment at the industry group level.
REITs, Telecom, and Energy are expected to have poor quarters, but sentiment is strong. These are industry groups that may surprise to the upside.
Materials are expected to see EPS rebound in 3Q, but sentiment is still pessimistic.
Semis, Banks, Tech Hardware, and Utilities have strong estimates, corroborated by high earnings sentiment.
Discretionary, Staples, and Autos are expected to have another bad quarter of earnings, and corporate sentiment is weak, too.
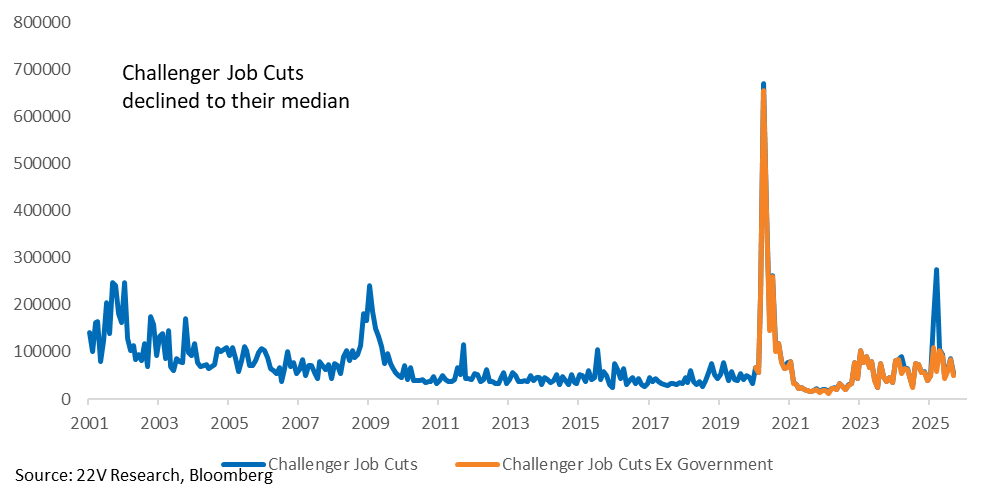
MARKET VIEWS: We don’t have much to offer on the data side, but some alternative labor market readings and the Challenge job cuts data point to a better picture than ADP. As Peter pointed out yesterday, Revelio Labs (a labor data platform that uses online professional platforms, HERE) posted a notably more optimistic view on employment in their just-released report. Given its novelty and limited history, it is hard to put much weight on this, but it is at least inconsistent with a dramatic deterioration in the labor market. Challenger job cuts moved lower.
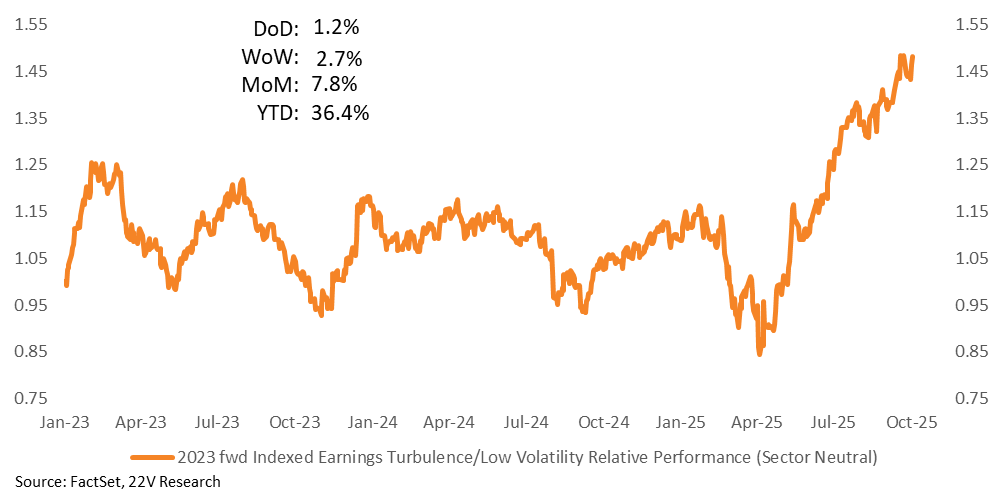
The firm economic activity data and anchored long rates backdrop will continue to drive market internals. Expect riskier factors (Momentum, EPS growth, Small size) and interest rate sensitives (Biotech, Housing, Debt Risk baskets) to benefit. Longer term, interest rate sensitive groups are fading as economic growth remains solid and the labor market stabilizes (Momentum, AI, Consumer services still work), but we will need firm labor market data before we can monetize that theme. Stay long the Earnings Risk and Short Low Vol (Staples).
Yesterday, the Quant team highlighted the strong outlook for 3Q EPS given the normal economic expansion, based on the aggregation of data throughout 3Q (HERE). Company earnings sentiment, measured using the Amenity language processing tool “listening to” and objectively scoring every earnings transcript, shows S&P 500 earnings sentiment has rebounded from the 2Q dip, while the forward outlook for margins is once again optimistic. No reasons to suspect a weak earnings season at the index level, based on what management teams are saying about their own company trends.
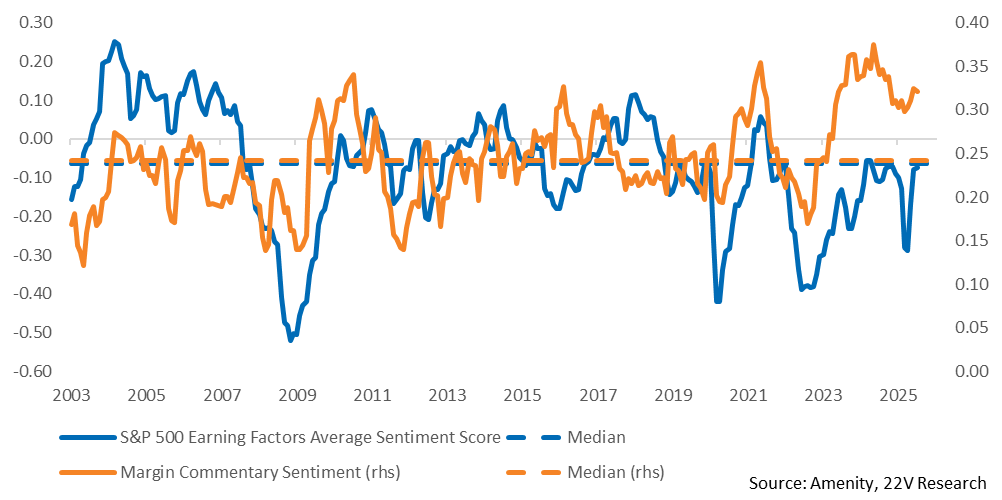
Earnings sentiment is an important tool in our risk management toolkit. Below, we compare analyst expectations to corporate sentiment at the industry group level.
REITs, Telecom, and Energy are expected to have poor quarters, but sentiment is strong. These are industry groups that may surprise to the upside.
Materials are expected to have an EPS rebound in 3Q, but sentiment is still pessimistic.
Semis, Banks, Tech Hardware, and Utilities have strong estimates, corroborated by high earnings sentiment.
Discretionary, Staples, and Autos are expected to have another bad quarter of earnings, and corporate sentiment is weak, too.
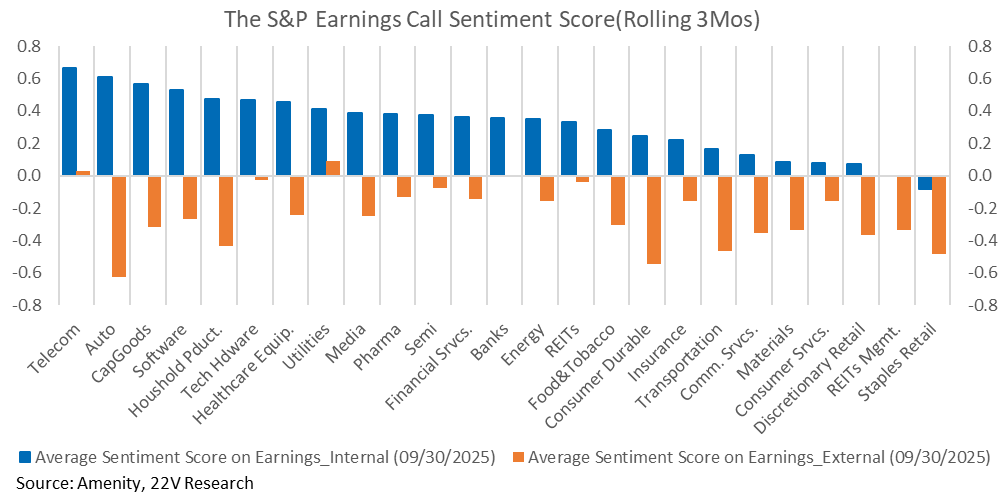
Sentiment in Autos is poor due to external sentiment – how management teams perceive the macro environment – while internal sentiment – how management teams view their own company outlooks – is one of the highest. This helps explain why Autos are one of the best performing industry groups YTD too, with the more onerous tariffs on the sector now reduced. Discretionary, Staples, and Transportation have weaker internal sentiment, highlighting the headwinds facing these groups.