Recent Inflation Data Will Force Hawkish Fed Revisions
- The Dot Plot likely sees an unchanged 2024 dot, but the distribution will have even more skew above the median than below. The 2025 and, likely but much less relevantly, 2026 dots will likely shift up by 25bps. The risk is live that the 2024 dot shifts up as well to show only 2 cuts.
- Over the course of the year the long-run dot is likely to shift up by at least 25bps. There has been some recent chatter to suggest this could happen in March but there’s little to force the issue at this particular meeting.
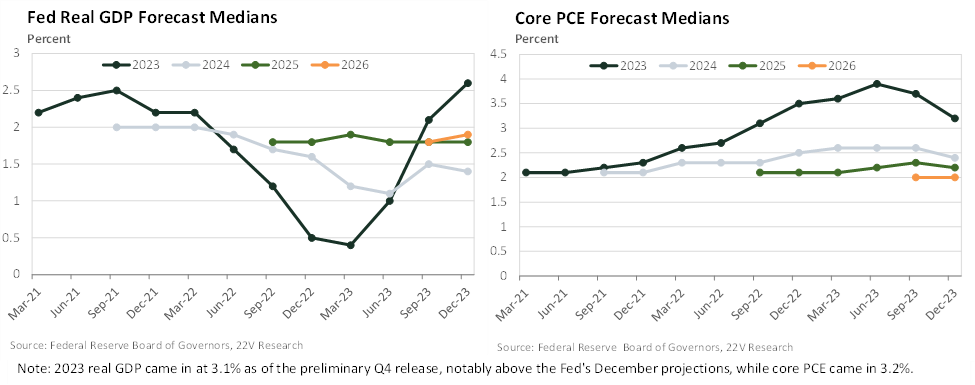
- The 2024 core PCE forecast is the hardest and most important part of the forecast to judge. The Fed likely will have anticipated some of the 24Q1 bounce in inflation but how much remains to be seen. Aiming to keep risks balanced around how I would have framed the implied monthly path in December, I think the 2024 core PCE forecast will be revised up 0.3p.p. to 2.7% (+0.3-0.4 seems plausible given different baseline assumptions but below that implies a quite dovish residual seasonality view of the recent data). 2025 possibly shifts up 0.1 to 2.3%. The 2024 shift would be largely mechanical, while 2025 reflects some extra caution and inflation inertia.
- The 2024 growth forecast likely moves up from 1.4% to 1.7%, with the Fed incorporating the above trend Q1 tracking but leaving some mildly below-potential growth on a 3-12m horizon, in keeping with this general but shrinking forecast pattern of the past few years.
- At the press conference, Powell will acknowledge that the recent inflation data hasn’t met the ‘more good data’ standard and will continue to emphasize cautious data dependence amidst a lot of noise, which skews medium-term hawkish given the asymmetry embedded in it.
- It seems unlikely, if possible, that the QT discussions which have been flagged for this meeting will result in a formal announcement to start slowing QT. My base case is that this meeting will be more of a presentation of options and discussions with a formal announcement coming in May or June. QT will be wound down slowly and in a market functioning dependent way, extending into at least late 2024, if not 2025.
- Market pricing is now roughly in-line or slightly above the Dot Plot (depending on horizon, markets seem to be pricing in a higher r* view in a way the Fed has not yet articulated openness to). In the near-term, we’ll have to see if after fading a large recessionary tail to start the year the market swings towards no-landing or if any slowdown in the data allows for the reemergence of a notable negative skew around the Fed base case.
Revising up Growth and Inflation
The Fed’s economic projections are likely to see some notable shifts, which vary from ‘somewhat hawkish’ to the more benign ‘not dovish’.
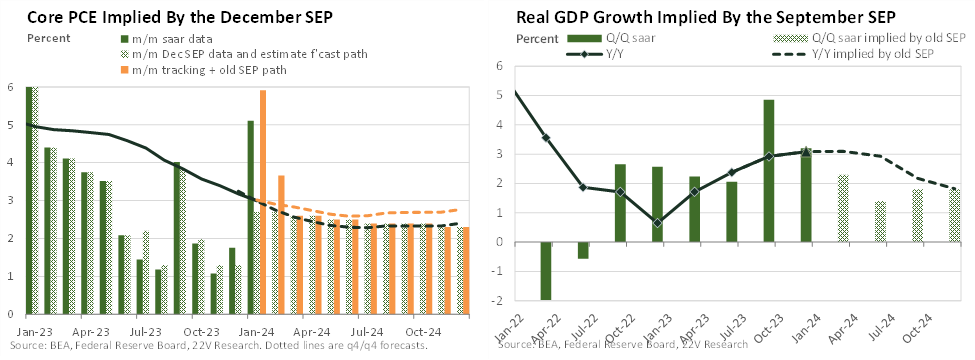
The 2024 core PCE forecast will likely shift up fairly substantially. Given the data in hand at the time and a reasonable path of m/m deceleration across 2024, the December SEP forecast likely assumed a roughly 2.7% m/m saar pace to start the year declining to 2.3%. This embedded some anticipated reacceleration in 24H1, including the possibility of some mild residual seasonality, from the at-or-below target pace seen in 23H2. Based off of the Jan PCE data and other revisions, the implications of the most recent PPI data for Jan and Feb PCE, and the Feb CPI, the Jan and Feb core PCE data, the cumulative inflation data has been well above most reasonable base cases from mid-December.
Combining the current data with an assumption of no shifts to my guesses of rest of the Dec SEP forecasts in Mar-Dec results in a 2.7-2.8% q4/q4 pace (if they just use the Jan PCE data in hand this is right around 2.7% but they have tended to update fully to PCE tracking). Given that the logic of residual seasonality suggests a possible mild lessening of pressures later in the year, I’d round this down to 2.7% as a base case. Given the old forecasts and surprises since, 2.6% or anything below suggests an ex post and highly convenient shift towards a stronger view of residual seasonality than they had held beforehand.
The Fed could interpret the hot start to the year, and less comforting recent inflation internals (after March CPI, my own views on core goods and housing inflation which may be being picked up internally by the Fed as well, and recent research from the FRBNY suggesting wage disinflation has stalled out), as slightly raising the outer months of the forecast as well; even a tenth or two higher average pace over a few months could push the forecasted q4/q4 pace up to 2.8%. The Board staff’s models will likely impart some additional short-term inertia to the data. Getting to 2.9% requires a more substantial lift to the Q2-Q4 forecasts and would almost surely come with at most 2, or even fewer, cuts.
Given all this, I suspect the additional inflation pressures likely raise the 2025 forecast by a tenth, but that’s a more tentative view. 2026 seems unlikely to change given the desire to be back at target; if it was revised up that would be a very meaningful shock reflecting additional inflation inertia in the Fed’s forecasts and seems too early in the bouncy normalization process for that.
The 2025 growth forecast is likely to come up notably as well; this is best thought of as removing a dovish case rather than adding to the hawkish one. In December the Fed projected 2023 real GDP at 2.6%; it is currently at 3.1%. Fed rhetoric on real rate restrictiveness and policy lags suggests to me that they’ll likely have a forecast with just below trend rather than right at trend or a bit above (which at potential growth for the rest of 2024 would imply), imply a Q2-Q3 growth in the mid-1s before the forecast returns to 1.8 for all the out years. Assuming 2.3% in 24Q1 and a similar just-below-trend rest-of-year path as was seen in the Dec SEP results in a 1.7-1.8% forecast for q4/q4 GDP growth in 2024. In the base case, the 2024 forecast will gradually creep up into the mid-2s as the year goes on but the data will have to lead the Fed there so long as its views on real rate restrictiveness, financial conditions tightness, and long lags remain what they currently are.
The unemployment rate forecast is likely to be little changed given the Fed’s growth path and differing signals from the household and employer surveys at this date early in the year.
A More Hawkish Dot Plot
The dot plot will see somewhat smaller shifts than these forecast revisions might otherwise suggest. Nevertheless, the incremental dovishness of Dec will be partially reversed.
The 2024 dot is unlikely to shift up, although it is, but the distribution will have even more skew above the median than below. The 2025 and, likely but much less relevantly, 2026 dots will likely shift up by 25bps reflecting the necessary but distant policy response to the hotter growth and inflation data.
To some extent not shifting up the 2024 dot given the plausible ranges for the 2024 core PCE forecast revisions seems a bit strange. I think the Fed will be hesitant to preemptively take away the dovish optionality in case the March and April inflation data come in better than expected. Even in a number of 2 cut paths, the Fed may still want to initiate cuts in June or July to start a very gradual easing cycle early; they may worry that if they put in only 2 in March it could overly hamstring their ability to gradually begin cuts over the summer if they decide they want to and not have another substantial communications challenge on their hands given default assumptions favoring quarterly cuts by most.
Instead of raising 2024 and taking away initiation optionality (optionality which now sells a dovish tail rather than a hawkish one), the Fed will respond to increased inflation forecast and the falling dovish risk management tail by raising the dots in 2025-26 by 25bps each showing a slower, more gradual and cautious, pace of descent towards neutral.
The lack of urgency in returning to the Fed’s current stated 2.5% neutral in the out years of the forecast shows a Fed which remains substantially inflation risk averse (policy is never neutral or stimulative but the economy is more or less at equilibrium by all the other measures in the last ~12-18m of the forecast) and an openness that short-run neutral, and perhaps long-run, is higher than it was pre-covid.
Over the course of the year the long-run dot is likely to shift up by at least 25bps. There has been some recent chatter to suggest this could happen in March but there’s little to force the issue either.