Back Portfolio Strategy

quick thoughts ahead of PCE + Deeper Look at Fair Value

Published on February 29, 2024

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

SUMMARY: There was a fair amount of Fedspeak yesterday reinforcing a few themes. 1) the Fed sees the path back to 2% inflation as bumpy but still expects inflation to continue trending in that direction. 2) They are not ready to declare victory. 3) Many at the Fed maintain a strongly held view that economic growth will be below trend this year (<1.8%-2%). If that doesn’t happen, there is less of a need to cut rates for risk management purposes. As yesterday’s GDP report highlighted and 1Q24 data has reinforced, final sales to domestic purchasers (analog to core GDP) is strong (HERE). The Fed cutting less because growth is firm is fine for risk assets. The Fed getting hawkish because growth is running above 2.75% (HERE) is a problem.

Few quick thoughts ahead of PCE today: Consensus has core at 0.4% and a small sample consensus for core services ex housing at ~0.6%. Generally, PCE is not far off from consensus as we get the inputs from CPI/PPI. Expect the focus to quickly turn to payroll on 3/8 and CPI on 3/12 unless the Core services ex housing PCE number is above 0.6.

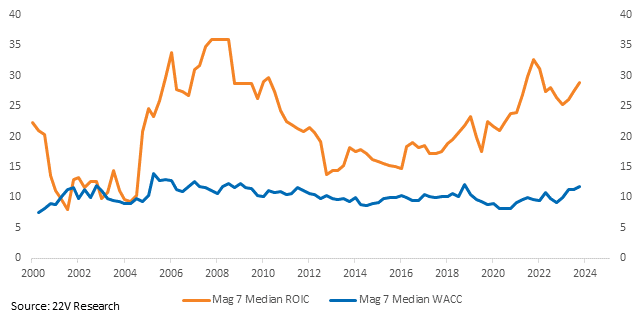
More on Fair Value: Yesterday we talked about upside to S&P fair value if the long-term cash return ratio stays elevated. Monopolies and platform effects may potentially keep cash return ratios elevated. Mature companies’ return on invested capital is supposed to gravitate toward their cost of capital. That assumption may not hold for monopolistic companies with network affects. Check out the ROIC vs WACC of the Mag 7 below. FYI Ben Thompson does great work on why network effects are so powerful – check out his stuff HERE. Worthwhile reading.

A graph of a line graph

Description automatically generated with medium confidence

As noted yesterday (HERE), buybacks rebounded in 4Q and the outlook for cash return is constructive. Buybacks are still a preferred use of capital, even with R&D and M&A expanding in 4Q.

The net net is ROIC vs WACC tells us the Mag 7 is likely to keep generating large amounts of cash, and use-of-cash data indicates returning some of that cash to shareholders is still popular. That has the potential to raise fair value significantly. More in the full report below…

MARKET VIEWS: There was a fair amount of Fedspeak yesterday and the comments reinforced a few themes. 1) the Fed expects the inflation path back to 2% to be a bit bumpy but expects inflation to continue its return journey to 2 percent. 2) They are not ready to declare victory. 3) Many at the Fed are also maintaining a strongly held view that econ growth will be below trend this year (below 1.8%-2%). If that doesn’t happen, there is less of a need to cut for risk management purposes. As the GDP report highlighted yesterday and 1Q24 data so far has reinforced, final sales to domestic purchasers (analog to core GDP) is strong (HERE). The Fed cutting less because growth is firm is fine for risk assets. The Fed getting hawkish because growth is running above 2.75% (HERE) is a problem.
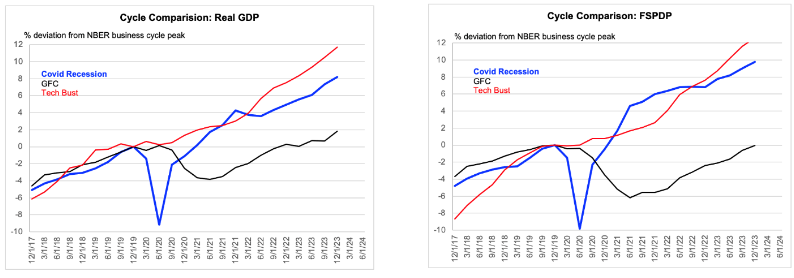
A graph of different colored lines

Description automatically generated with medium confidence

Source: BEA, NBER, FH calculations

Data are as revised to Q4.

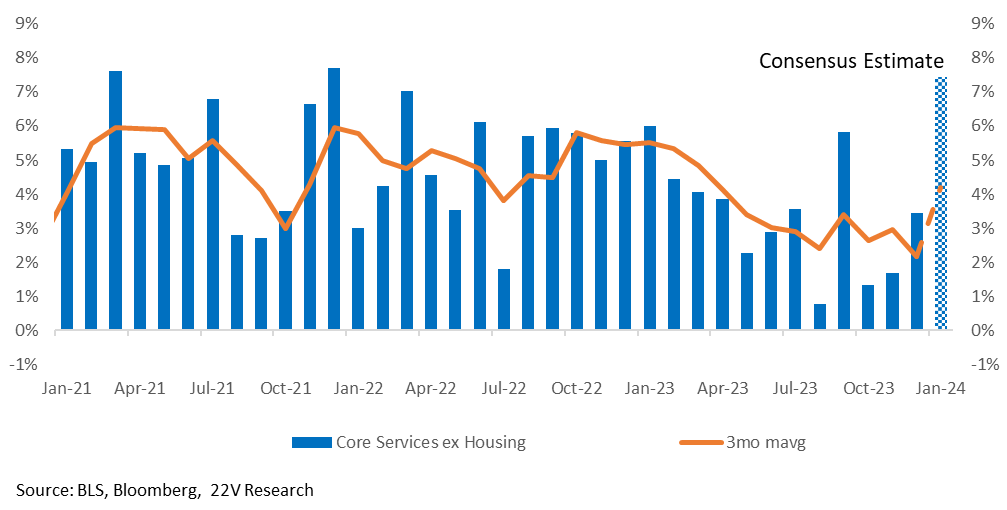
Few quick thoughts ahead of PCE today: Consensus has core at 0.4% and a small sample consensus for core services ex housing at ~0.6%. Peter Williams noted “there’s a risk that seeing something like those consensus numbers, if they happen, could spook markets a bit, especially those a bit less in the weeds.” Above point 0.6 on Core Services ex housing would be bad. 0.5 likely somewhat of a relief. Generally, PCE is not far off from consensus as we get the inputs from CPI/PPI. Expect the focus to quickly turn to payroll on 3/8 and CPI on 3/12 unless the Core services ex housing PCE number is above 0.6.
A graph with blue and orange lines

Description automatically generated

More on Fair Value: Yesterday we talked about upside to S&P 500 fair value if the long-term cash return ratio does not return to the ‘sustainable’ level implied by the ratio of earnings to book value to the risk-free rate. In our fair value calculations, we use the below calc to estimate the long-term cash return ratio, which is based on a classic stable growth model.

Monopolies and platform effects may potentially keep cash return ratios elevated. Mature companies’ return on invested capital is supposed to gravitate toward their cost of capital. That assumption may not hold for monopolistic companies with network affects. Check out the ROIC vs. WACC of the Mag 7 below. FYI Ben Thompson does great work on why network effects are so powerful – check out his stuff HERE. Worthwhile reading.
A drawback of the formula we use is that BVPS doesn’t include intangibles, and intangibles as a percent of book value have been increasing for the S&P.
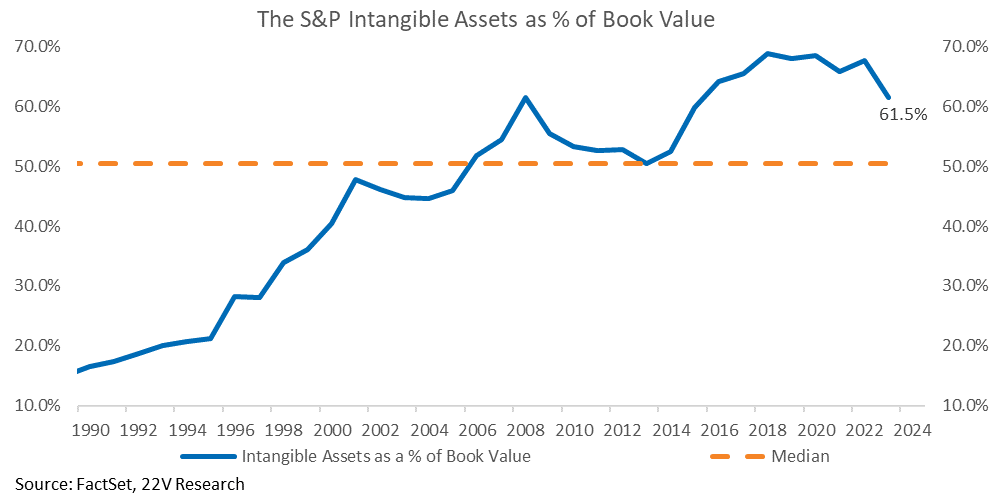
A line graph with orange lines and numbers

Description automatically generated

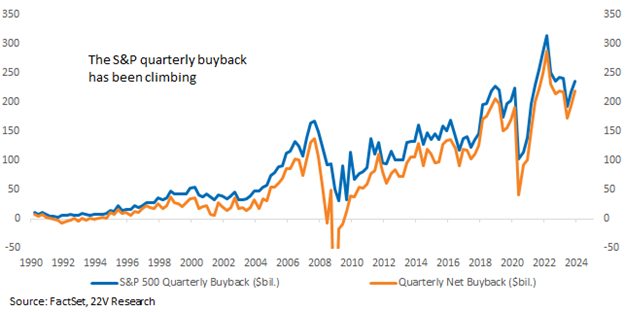
As noted yesterday (HERE), buybacks fell in 1H23 as earnings contracted and macro uncertainty peaked. In the second half, buybacks rebounded. S&P EPS is expected to expand 9-10% in 2024, setting the stage for a rebound in buybacks. Upward surprises on revenue, margins, and EPS + easing of economic tail risks suggest buybacks will continue to move higher throughout 2024.
A graph of a graph with numbers and lines

Description automatically generated with medium confidence

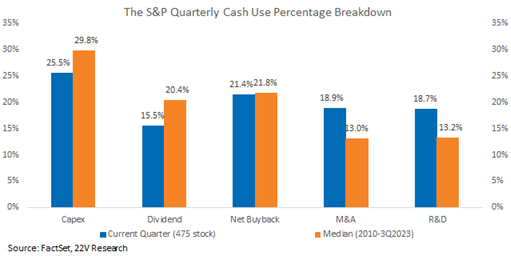
Buybacks are still a preferred use of capital, even with R&D and M&A expanding in 4Q. ROIC vs WACC tells us the Mag 7 is likely to keep generating large amounts of cash, and use-of-cash data indicates returning some of that cash to shareholders is still popular. That has the potential to raise fair value significantly.
A graph of blue and orange bars

Description automatically generated

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.