SUMMARY
- With the annual National People’s Congress (NPC) due to start on March 5, China’s leadership has reaffirmed a strategy of restrained stimulus and a focus on supply-side rather than demand-side policies; the potential re-election of Donald J. Trump as US president only adds to Xi Jinping’s inclination to concentrate on boosting supply chain resilience while preserving stimulus “ammunition” in case of a renewed trade war
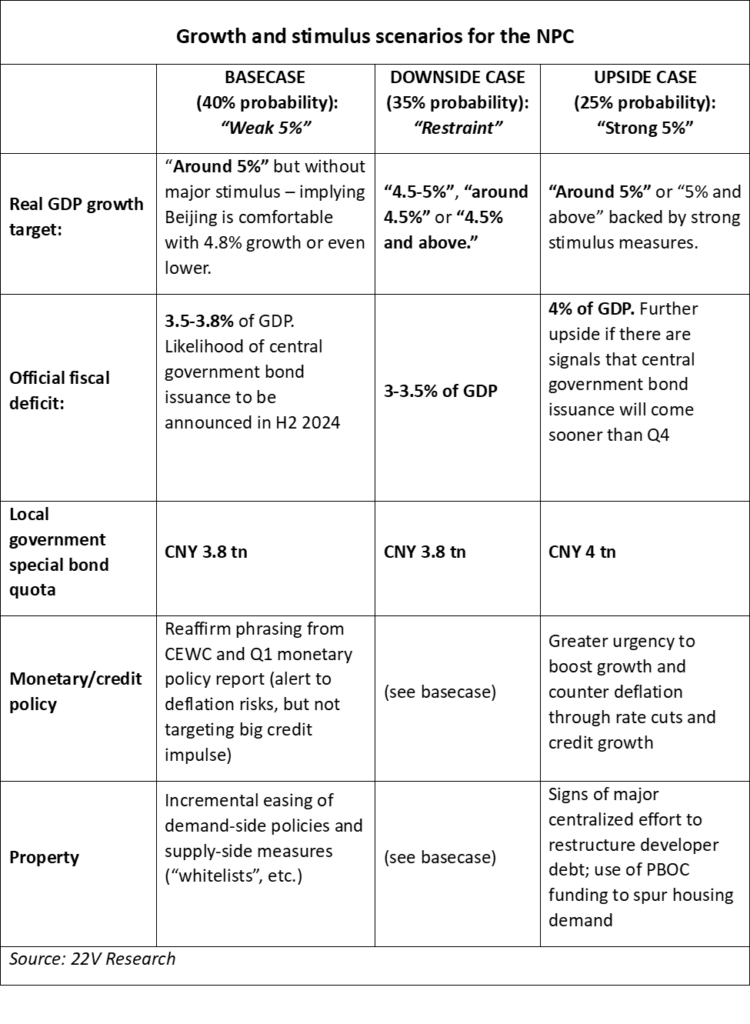
- Our basecase for the NPC (40% probability) is a “weak 5%” scenario in which Beijing sets a target for real GDP growth of “around 5%” but with only moderate stimulus; that means a risk of underperforming the growth target, and a likelihood that deflationary pressures persist given weak domestic demand
- The next most likely scenario (35% probability) is a downside case in which Beijing sets a conservative growth target of less than 5%; finally, there is a 25% probability of an upside scenario in which Beijing sets a growth target of 5% and pledges forceful stimulus to secure that goal and fight off deflation
The political elite come to meet
The annual meeting of China’s legislature, the National People’s Congress (NPC), is due to start on March 5. Officials and advisors from around the country will convene in Beijing for a week of meetings. This event is also called the “Two Sessions,” since the NPC meets alongside a political advisory body known as the Chinese People’s Political Consultative Conference.
The key event for markets at the NPC will come at the start of the opening day (likely late in the evening of March 4 EST) when Premier Li Qiang verbally delivers the annual government work report to the NPC. The report will announce the key economic targets for this year – including the annual GDP growth target, fiscal deficit, envelope for local government borrowing, and description of monetary policy – and outline Beijing’s major policy initiatives.
Other useful information for investors will trickle out over the course of the week. General Secretary Xi Jinping will signal his political priorities, including on geopolitical flashpoints such as US-China issues and Taiwan, in a closing address and in speeches to local government delegations. Personnel appointments and press conferences by economic officials may also be informative.
In this note we lay out expectations for the NPC and implications for investors, focusing on a central theme of the politics of growth and stimulus.
Another year of muddling through
In a note on Monday (link HERE), we took stock of political and economic dynamics ahead of the NPC. While Beijing is eager to revive growth and animal spirits, Xi Jinping continues to emphasize his mantra of “high quality development” – a message that China will stay disciplined in its stimulus and focus on promoting strategic priorities, such as by expanding investment in clean tech and other areas of advanced manufacturing.
The latest signals from Beijing reaffirm that message of restraint. On Thursday, Xi convened a meeting of China’s Politburo (the Party’s top 24 officials) to discuss preparations for the NPC. The wording and tone were very similar to the Central Economic Work Conference (CEWC) in December, which itself was underwhelming with respect to the urgency of boosting growth and signals of stimulus (see our report on the CEWC HERE).
This is a brushback against those calling for aggressive loosening measures – sharp interest rate cuts, large fiscal deficits, debt relief for property developers and local governments – to offset the housing downturn, deflationary dynamics, and weak confidence. China’s leadership is not deaf to those calls but believes that following such advice would endanger Xi’s long-term agenda by worsening financial risks (especially local government debt) and wasting resources on areas of the economy (especially real estate) that do not advance China’s drive towards self-reliance in critical technologies and supply chains.
In short, Beijing’s strategy is to muddle through this painful transition in its economic model until new growth drivers such as electric vehicles are large enough to replace real estate. So long as nothing “breaks” along the way – such as the financial system or social stability – Xi has a high tolerance for disruption. The rejoinder from Xi’s critics is that this parsimonious approach to stimulus risks turning a “transition” into a long-term, Japan-style malaise. The critical challenge for Premier Li and the rest of Xi’s economic team is how to walk this balance, providing enough support to keep growth afloat while heeding the boss’s directive on the need to stay disciplined.
As an additional wild card, the potential for Donald J. Trump to be reelected as US president only adds to Xi’s inclination to stay disciplined on stimulus this year. First, Xi will be even more determined to scale up supply-side measures to boost China’s resilience against intensifying US export controls and trade restrictions. Second, he likely wants to save stimulus “ammunition” in case Beijing needs to aggressively support domestic demand in coming years amid a renewed trade war.
How it will play out at the NPC
The tension between boosting confidence and maintaining discipline comes to a head in a significant ‘disconnect’ in expectations for China’s growth target for 2024. The disconnect is that domestic economists are virtually unanimous in expecting a growth target of “around 5%,” but securing this target likely require much more forceful stimulus than Beijing has signaled it is prepared to provide.
In 2023, China set a growth target of “around 5%” and exceeded it with full-year growth of 5.2% (with justified skepticism as to whether those official statistics overstate actual growth). But the headwinds this year are stiffer:
- Base effects are tougher than last year, which benefited from the easy comparison to the zero-Covid disaster of 2022
- The property sector shows no signs of bottoming, through the contraction in sales and investment will a bit smaller than last year
- Local government finances are under heavy strain from the loss of land sales revenues and mounting debt burdens. Beijing is taking a tough line with local governments, recently putting 12 (mostly poor) provinces under tight restrictions for borrowing and spending. These dynamics will constrain infrastructure investment, even as the central government steps up financing for key projects and leans on richer provinces to pick up the slack
- Consumption powered GDP growth last year but this came from pent up demand during Covid that is likely to peter out as households remain frugal (see our Monday note for more)
- Manufacturing investment has been another growth driver, but some of the key sectors favored by policymakers – in particular the clean tech complex (EVs, batteries, solar) – face overcapacity
Here are two other indications of the difficulty of hitting 5%:
- Sell-side forecasts (via Bloomberg), which are not known for being pessimistic, expect growth this year of only 4.6%. By contrast, heading into last year’s NPC, the consensus forecast for 2023 was 5.2%. This was above the target subsequently announced by the NPC (“above 5%”) and ended up in line with full growth for the year.
- Provincial governments’ GDP targets this year are consistent with a 5% national target but just barely. The average of provincial governments’ targets, weighted by their GDP, is 5.4%, 0.2 percentage points lower than last year’s average of 5.6%. Since actual growth last year was 5.2%, that 0.2 percentage point reduction could still put growth on track for 5%. But it doesn’t leave much wiggle room. Everbright Securities’ chief economist Gao Ruidong has observed that local targets in recent years have been 0.6-0.8 percentage points above the national target, which would imply a 2024 national target of only 4.6-4.8%. (He nonetheless expects Beijing to target “around 5%”).

There are three main ways that this disconnect – calls for a high growth target vs. signaling of restrained stimulus – can play out at the NPC:
- Our basecase (40%) probability is what we call “a weak 5%”: Beijing sets a target of “around 5%” but with only moderate stimulus. This outcome will be “weak” in two respects. The first is the risk of underperforming the target: Xi’s economic team will hope for the best (a turnaround in confidence, favorable global conditions) but be willing to tolerate growth of 4.8% and perhaps even a bit lower. The second factor is that even if China achieves the real GDP target, the economic reality for most firms and households – and for investors in Chinese equities – will feel worse than the headline figures represent. With stimulus focused on supply-side measures, production will continue to outpace demand. That will continue to mean an environment of significant excess capacity, deflationary pressures, and a drag on corporate revenue and profit growth. This “weak 5%” scenario will underwhelm investors reacting to the NPC, though some degree of pessimism is likely already priced in.
- The next most likely scenario (35% probability) is a downside case in which Beijing sets a growth target below 5%. We would expect the target to be framed as “4.5-5%” but “4.5 and above” or even “around 4.5%” are possible. A conservative growth target would provide policymakers with room to make progress on issues such as reining in local government debt but it would be a much less growth-affirming message than investors expect. The difference between 4.5% and 5% growth is more significant for firms and investors the headline numbers might suggest, given that slower growth would mean additional slack in the economy and thus a greater risk of deeper and more entrenched deflation.
- The upside scenario for markets – which we call a “strong 5%” – is the one that we see as the least likely (25% probability). Beijing sets a growth target of “around 5%” along with the forceful stimulus necessary to secure this goal. Particularly if it comes with stronger demand-side measures, this aggressive approach would be especially impactful by also reducing deflationary pressures and lifting nominal growth, a key concern of investors.
Even if one assumes that these three scenarios are equally likely, the distribution of probabilities is such that the NPC is more likely to underwhelm (either of the first two scenarios) than it is to surprise on the upside (last scenario). In the table further below, we lay out the stimulus announcements that would be broadly consistent with each scenario.
What will the pattern of growth look like over the course of the year?
Houze Song of the Paulson Institute’s MacroPolo think tank expects a conservative GDP growth target of 4.5% (the downside scenario above) as Beijing bows to the reality of the property downturn and pressure on local government finances (see his outlook for China’s first half HERE). He sees a U-shaped pattern to growth this year. Infrastructure funding already in the pipeline would be enough to get growth off to a decent start in Q1, but this would soon fade as policymakers withhold major stimulus. Beijing would be forced to ease more towards the end of the year, as was the case in late 2023.
In the basecase and upside scenarios we would expect a less pronounced version of this U-shaped pattern. Growth momentum is likely to slow a bit in Q2 and Q3, but policymakers will aim to avoid the sharp slowdown experienced in the middle of last year. PBOC, for example, has directed banks to smooth out lending activity rather than the huge customary surge to start the year.
Two key swing factors: property and local debt
In addition to the mostly quantitative targets laid out above, the outlook for growth and reviving private sector confidence will also depend on Beijing’s approach to the property sector and local government debt.
Our note on Monday (link again HERE) discussed one of the watchpoints on property: the extent to which Beijing uses its affordable housing initiatives, funded by the PBOC’s PSL facility, to also support the private residential market. One way it could do so would be purchasing unsold property from developers and converting this to affordable housing, which would reduce excess housing inventory and thus support prices. In the upside scenario of an ambitious growth target, we expect this approach to be less likely, since Beijing will be more inclined to build new affordable housing in order to generate the construction activity necessary to boost GDP.
The other way Beijing could support the private market would be generous use of the PSL to fund purchases of new homes for residents resettled under the urban village reconstruction program. That would be bullish for property demand in any of the scenarios above. We are skeptical of an aggressive push in this area – Beijing is not eager to repeat the flood of housing speculation that such an approach produced under the “shantytown redevelopment” scheme of 2015-2019 – but signals at the NPC will be worth monitoring.
However, the two most important steps that Beijing could take to revive property are (1) stimulus measures that directly or indirectly boost household income, the weakness of which is holding back willingness to take on new mortgages and buy property; and (2) a comprehensive effort to restructure private developers’ debt so that households and creditors are confident buying from and lending to them. There is very little prospect of #1 coming at the NPC. #2 is also unlikely, with Beijing instead likely to signal more programs to encourage banks to lend to specific projects but not to tackle the fundamental issue of widespread developer insolvency.
When it comes to local government debt, since mid-2023 Beijing has adopted a two-pronged muddle-through strategy: help local governments refinance their debts and those of their affiliated financing vehicles, but maintain pressure on them to reduce their debt burdens without bailouts from the central government. That strategy has lowered the near-term risk of local governments and LGFVs defaulting on bonds, but has left them in very tight financial circumstances, particularly with revenues from land sales to developers (typically around 40% of local government revenue) due to stay weak this year. The main watchpoint at the NPC is the degree to which Beijing signals a relaxation of these restrictions – which would be bullish for growth – or maintains a tough tone, which is our basecase.