XHB and Builders’ Earnings Season Say Housing Demand is Looking Up (and to Fade the January Housing Starts Number)
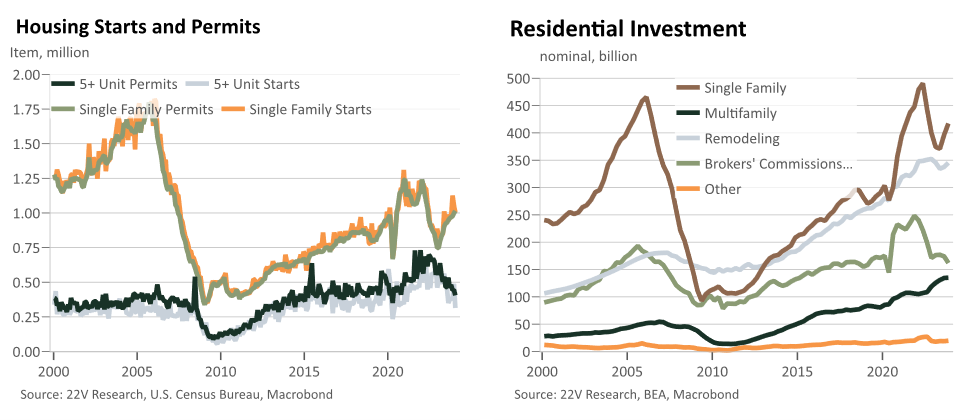
While markets took a fairly sanguine view of the weak January housing starts and permits numbers, which admittedly came with positively revised December data, the data did raise some questions about the possibility of the underlying momentum in the housing market rolling over again a bit to start the year.
Recent earnings announcements from several home builders lean against that view, with many pointing to normal or better than average sales and foot traffic through January and into February.
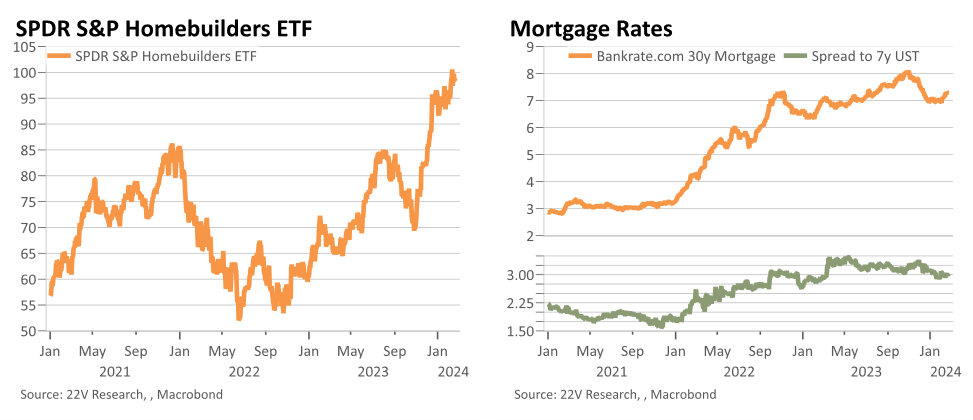
The rebound in housing starts since early 2023 suggests, and corporate commentary seems to confirm as well, that with robust income growth and household balance sheets, limited churn in existing homes, and positive demographics, the rates floor (i.e. the level of mortgage rates which below which activity seems to hold up if not boom) in the housing market has shifted up notably.
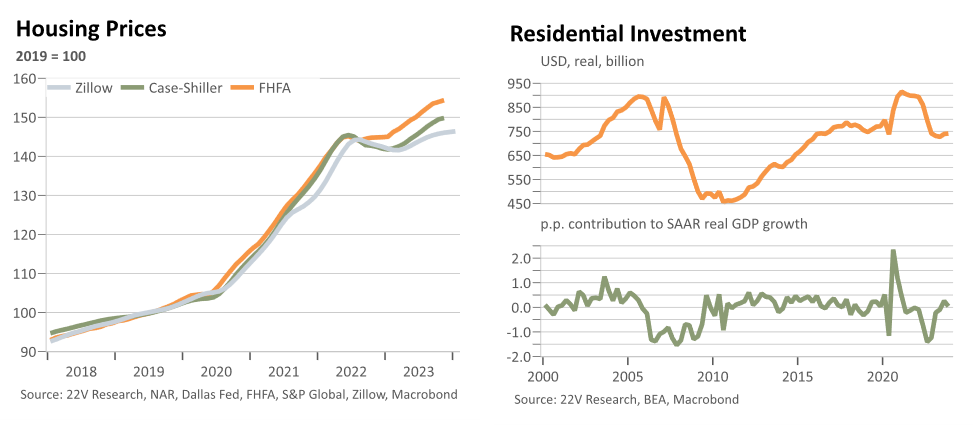
A slow continued upturn in the single family construction and, more gradually, existing home sales, with their associated commissions and moving costs, and remodeling demand, has been a key part of our general macroeconomic optimism for some time (see more here). Multifamily will remain continue to weaken some in level terms though given the surge in supply which began being built in 2021 and is now delivering, but this has a notably smaller impact on activity than the sectors mentioned above (MF is after all more efficient to build per unit than SF and sees a much smaller number of starts). Given that housing is the most impactfully cyclical part of the economy, this slow rebound will help put a floor under growth.
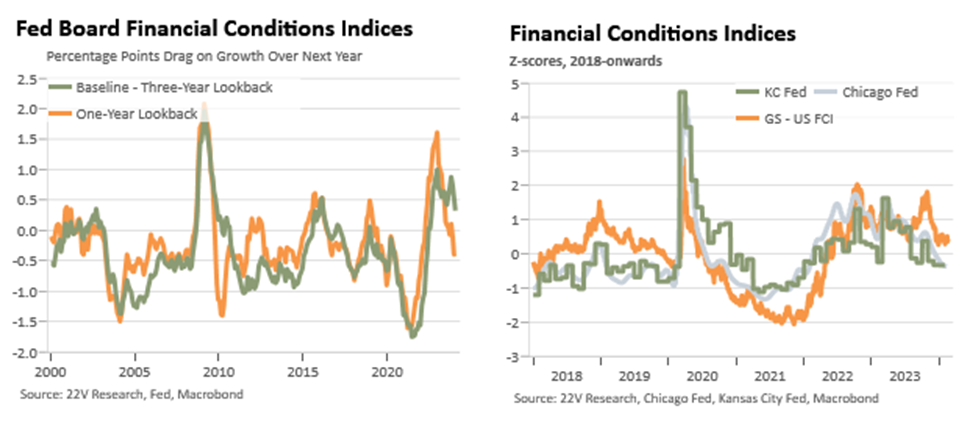
The better tone from homebuilders also leans against some forecasts for below potential growth in 2024-25 which are premised on a restrictive stance of policy and long lags. The recent January meeting Minutes from the Fed highlighted this issue (I focused on the hawkish rates risks stemming from the Fed’s base case having too slow of growth in my Minutes writeup here), with the Fed noting potential for upside growth surprises and that in its base case policy is restrictive and financial conditions apt to pull growth below potential. In level terms, relative to the counterfactual, there may be some truth to this but in terms of growth rates I struggle to see a persistent headwind coming from ‘tight’ monetary policy when it looks like housing is slowly, if a bit bumpily, starting to rebound and many measures of financial conditions have shifted to notably less tight levels than they had been at over various points in 2023.
Over the longer-term there is some risk that markets price in too much optimism for some of the builders and related stocks. However, at least in the near-term, that doesn’t seem prudent to try to act on as the data is generally bouncing and, as John Roque notes, the sector scores very well technically.
In the near-term, the most rate sensitive part of the economy seems to be weathering high rates surprisingly soundly, which bodes well for overall economic performance even if it raises the odds the Fed ends up underdelivering on expectations for rate cuts in a non-recessionary world.
A Few Lines that Jumped Out from Recent Earnings Calls and Other Events
- TOL
- “In addition, since the start of the spring selling season in mid-January, we have seen a meaningful uptick in demand that has continued through this past weekend.”
- “Demand in our first quarter steadily improved as the quarter progressed, following the normal seasonal pattern. December was stronger than November and January was significantly stronger than December. Based on both deposit and agreement activity, our January was better than normal seasonality. The strong demand has continued through the first three weeks of February.”
- TPH
- “As rates began descending in November, home buying activity increased with December ultimately exhibiting the strongest orders of the quarter. That end of year momentum has been sustained through January and into February.”
- “But like we said earlier, it will all depend on how demand – if demand continues the way it’s going right now, you could see some upside to margin as the year goes forward.”
- DHI
- “Early signs for the spring selling season have been encouraging.”
- “Coming out in January, does not make a quarter or a spring selling season, but we’re very encouraged by the early trends in January and are excited for what the spring is going to hold.”
- “I think we’ve been encouraged by the early spring selling season, the signs. We’re still just on the leading edge of it. But traffic has been consistent, and demand has been good and I think in line with our expectations thus far.” – 2/20/24 Citi event
- CCS
- “Homebuyers are exhibiting strong demand for affordable new homes. Our cycle times have returned to historical levels and further growth in our community count is anticipated.”