SUMMARY: A “leak” of Powell’s reaction to CPI – that the data were “consistent with what they had been anticipating” – helped risk-on equities extend their rally late yesterday. Per Peter, “It seems like this is an acknowledgement that they thought Jan might come in a bit hot and they’re ok with some m/m vol in the data and this doesn’t disrupt the disinflationary trends yet. But the ‘more good’ standard still binds over the medium-term because they aren’t marking policy for May/June/Onwards over just Jan data.”
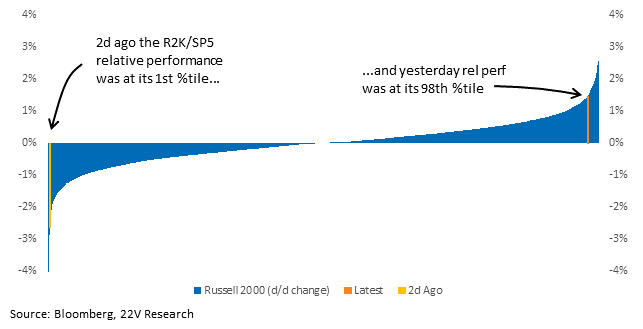
To us it reinforces the idea that the direction of travel remains the same; ~3 cuts are still on the table, and that’s good for risk assets if growth remains steady. Internals did not reverse Tuesday’s selloff. Risk-on factors are still over the past two days. But Tuesday’s 98th %tile declines were followed Wednesday by 99th %tile gains.
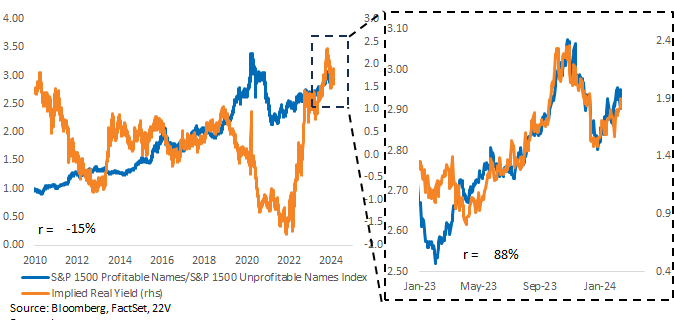
PROFITABLE VS. UNPROFITABLE: S&P 1500 unprofitable companies outperformed profitable companies in 4Q as real yields gapped lower. We’re looking for a lot of the 4Q leaders (the average stock, risk-on factors) to outperform over the course of 2024 as growth slows. IF growth continues to surprise to the upside, even with lower inflation, unprofitable companies should struggle. They would face headwinds in a higher neutral rate backdrop.
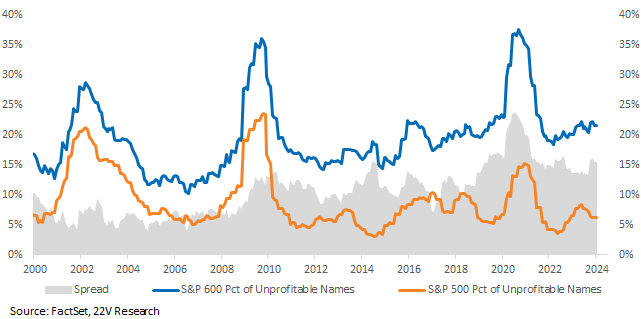
Clients have noted that small caps have a profitability problem. They have a point. The percent of unprofitable S&P 600 vs S&P 500 companies is in its 89th percentile. Strong economic growth should help this ratio normalize, but that path may not be immediate or smooth. We don’t think this changes the small cap catchup thesis given their steep valuation discount and the reduction in downside tail risks, but will do more work on it.
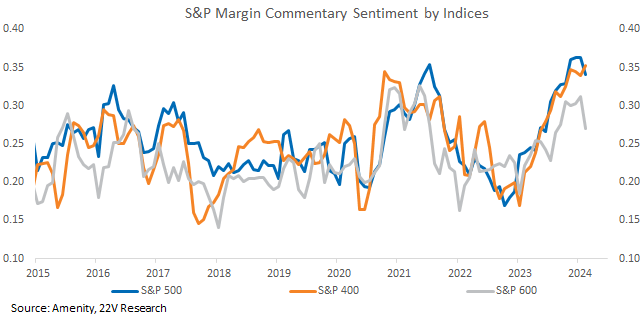
As the quant team wrote yesterday (HERE) small cap pricing power sentiment is poor. During 4Q reporting, S&P 600 margin sentiment diverged from S&P 500 and S&P 400 margin sentiment. Large cap profit margins should continue to be strong, but small cap companies are still signaling problems with their margin outlooks.
There are pockets within small caps that have less of a profitability headwind. Discretionary and Deep Cyclicals are better positioned than Health Care (Biotech) and Tech + Comm Svcs.

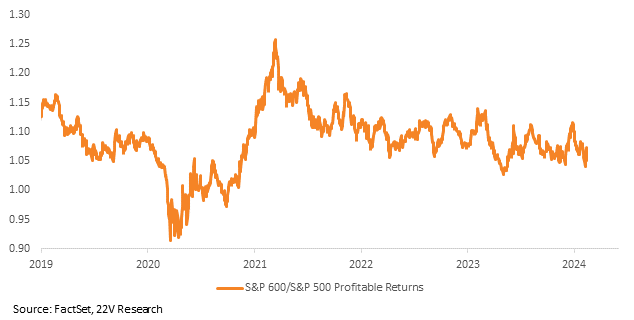
Profitable small caps are still lagging profitable large caps (though not as much as unprofitable), and would be a catchup trade less levered to lower real yields. An excel classifying S&P 600 constituents as profitable and unprofitable can be found (HERE).
MARKET VIEWS: A “leak” of Powell’s reaction to CPI – that the inflation data was “consistent with what they had been anticipating” – helped risk-on equities extend their rally late in the day. Per Peter, “It seems like this is an acknowledgement that they thought Jan might come in a bit hot and they’re ok with some m/m vol in the data and this doesn’t disrupt the disinflationary trends yet. But the ‘more good’ standard still binds over the medium-term because they aren’t marking policy for May/June/Onwards over just Jan data.” To us, that reinforces the idea that the direction of travel remains the same; ~3 cuts are still on the table, and that’s good for risk assets if growth hangs in with 3 cuts. Internals did not reverse Tuesday’s entire move, but there were 98th percentile moves following Wednesday’s 1st percentile moves.
PROFITABLE VS UNPROFITABLE: Normally, profitable companies outperform unprofitable companies pretty consistently, and normally, the return isn’t too sensitive to real yields. Right now though, that is NOT the case. Unprofitable had a nice leg of outperformance in 4Q. We’re looking for a lot of the 4Q leaders (the average stock, risk-on factors) to outperform in 2024 pending slower data, but if growth continues to surprise to the upside, even with lower inflation, unprofitable companies may not join the rally. They continue to face headwinds in a higher neutral rate backdrop. As Peter explains HERE, continual growth surprises are a potential sign of a higher neutral rate.
Investors have pointed out to us that small caps have a profitability problem. They have a point. The percent of unprofitable in the S&P 600 vs the S&P 500 is in its 89th percentile. Strong economic growth should help this ratio normalize, but that path may not be immediate or smooth. We don’t think this changes the small cap catchup thesis given their steep valuation discount and the reduction in downside tail risks but will do more work on it.
As the quant team wrote yesterday (HERE) small cap pricing power sentiment is poor. During 4Q reporting, S&P 600 margin sentiment diverged from S&P 500 and S&P 400 margin sentiment. Large cap profit margins should continue to be strong, but small cap companies are still signaling problems with their margin outlooks.
There are pockets within small caps that have less of a profitability headwind. Discretionary and Deep Cyclicals are better positioned than Health Care (Biotech) and Tech + Comm Svcs.
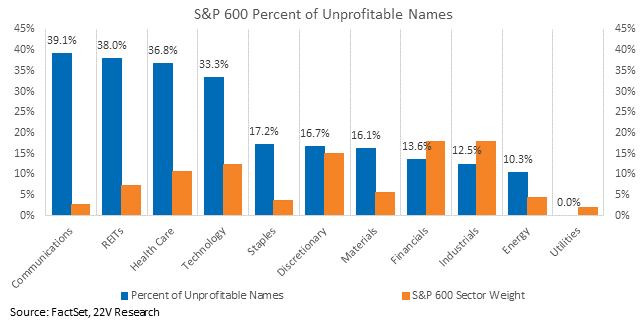
Profitable small caps are still lagging profitable large caps (though not as much as unprofitable), and would be a catchup trade less levered to lower real yields. An excel classifying S&P 600 constituents as profitable and unprofitable can be found (HERE).