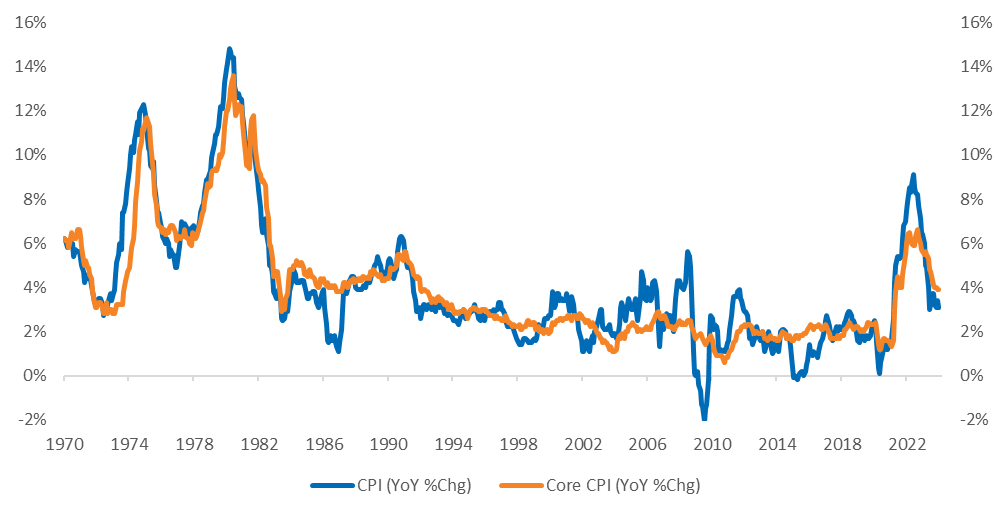
CPI data for January was much stronger than expected, leaving headline and core readings above 3% on a y/y basis. As is usual, there are some questions about seasonal adjustments and the volatility of line items. How those questions are answered has important macro implications. Today we focus on pricing power, which has remained strong, supporting margins and earnings. The strength in pricing power is consistent with the still high levels of inflation, which is 1) WELL off its highs and 2) still elevated.

Managers at S&P companies have grown more confident in their ability to command prices. Historically, periods of easing financial conditions have coincided with firming pricing power. Near-term, the easing of FCI over the past few months is a support for sales, margins, EPS for 1Q24. Longer-term, if FCI needs to be tightened again to lower inflation, that will be a headwind for earnings. But that is more likely a 2H24 issue.
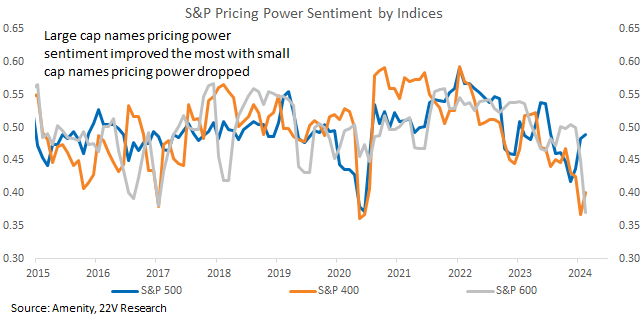
An important point to keep in mind is that pricing power sentiment has diverged sharply across market cap tranches. Large cap pricing power sentiment is by far the strongest and has rebounded the most over the past few quarters. Small cap pricing power sentiment has continued to move lower. This helps explain the wide divergence in estimate trends between large and small caps. Large cap profit margins should continue to be strong, supporting their earnings into at least 1Q. Mid cap pricing power sentiment is improving as well, suggesting some catchup to large caps.
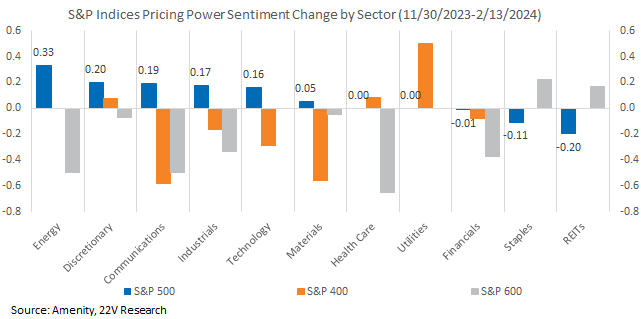
At the sector level, large cap pricing power sentiment improvement most within Energy, Discretionary and Communications. Defensives, especially REITs and Staples, saw declines in pricing power. Small cap names pricing power sentiment dropped for most sectors.
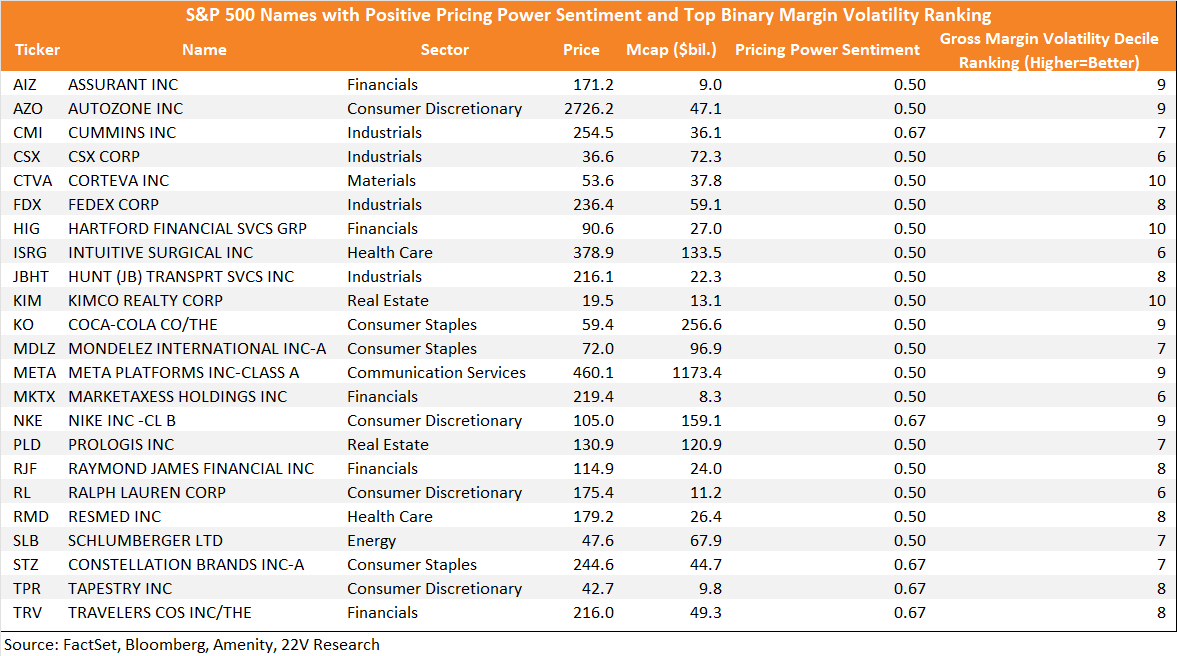
We list the S&P 500 names with positive pricing power sentiment and lower long-term gross margin volatility in the full report below…
Rebounding Pricing Power Supporting Margins: CPI data for January was much stronger than expected, leaving headline and core readings above 3% on a y/y basis. As is usual, there are some questions about seasonal adjustments and the volatility of line items. How those questions are answered has important macro implications. Today we focus on pricing power, which has remained strong, supporting margins and earnings. The strength in pricing power is consistent with the still high levels of inflation, which is 1) WELL off its highs and 2) still elevated.
Source: BLS, Bloomberg, 22V Research
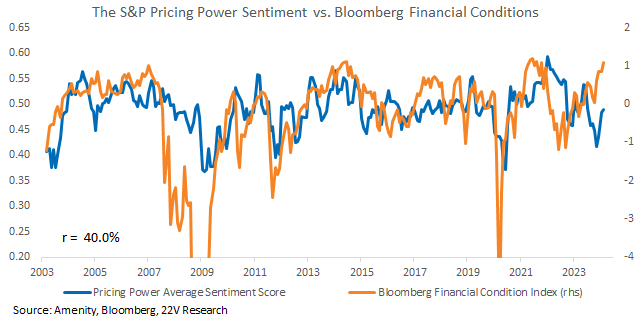
Our measure of S&P pricing power has rebound sharply since late last year with average positive mentions increasing more than negative pricing commentary. Managers at S&P companies have grown more confident in their ability to command prices. Historically, periods of easing financial conditions have coincided with firming pricing power. Near-term, the easing of FCI over the past few months is a support for sales, margins, EPS for 1Q24. Longer-term, if FCI needs to be tightened again to lower inflation, that will be a headwind for earnings. But that is more likely a 2H24 issue.
An important point to keep in mind is that pricing power sentiment has diverged sharply across market cap tranches. Large cap pricing power sentiment is by far the strongest and has rebounded the most over the past few quarters. Small cap pricing power sentiment has continued to move lower. This helps explain the wide divergence in estimate trends between large and small caps.
Profit margins of large and small cap names are roughly aligned with the sentiment changes recently. Large cap names profit margin rebounded from their relative low in mid-2023, while mid and small cap names profit margins have stagnated. That confirms the positive correlation between pricing power sentiment and actual margin trends. Large cap profit margins should continue to be strong, supporting their earnings into at least 1Q. Mid cap pricing power sentiment is improving as well, suggesting some catchup to large caps.
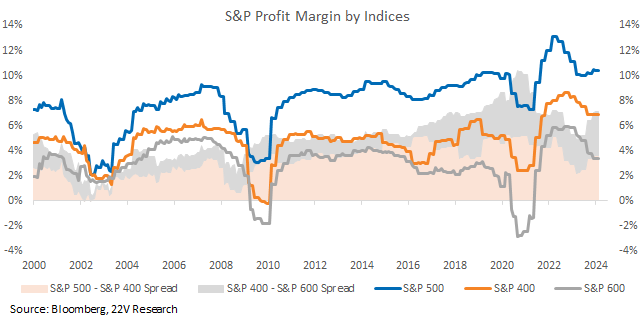
At the sector level, large cap pricing power sentiment improvement most within Energy, Discretionary and Communications. Defensives, especially REITs and Staples, saw declines in pricing power. Small cap names pricing power sentiment dropped for most sectors.
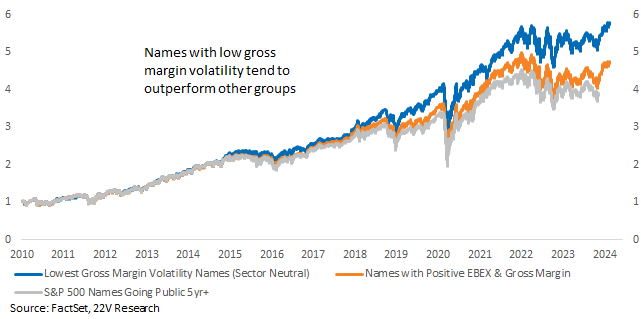
In addition to mentions of pricing power sentiment by corporate managers, margin stability also implies their pricing power. We track the performance of S&P names with positive pricing power sentiment and the lowest gross margin volatility in each sector. Those names have outperformed the broad market over the long run and the basket has posted a 0.7% excess return YTD as well.
Below, we list the S&P names with positive pricing power sentiment reading in their latest earnings release with lower long-term gross margin volatility (only positive gross margin and earnings names are selected to avoid companies in secular decline). These names tend to show strong pricing power in both sentiment and fundamental measures and are expected more likely to keep their profitability.