Back Portfolio Strategy

Echos of 3Q23 – Factor Positioning & Mean Reversal

Published on February 7, 2024

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

SUMMARY: Economic growth is much firmer than expected, increasing the RISK that financial conditions need to tighten plus, New York Community Bank is down almost 60% in 5 trading days, and investors are debating how far Chinese authorities will go in supporting equities. FYI: John Roque noted yesterday that the “price action suggests a tradable bottom is coming together in China”. Uncertainty is high near term, which lends itself to mean reversion. Most of what worked in December ‘23 (small caps, value, Deep Cyclicals) significantly underperformed in January ‘24.

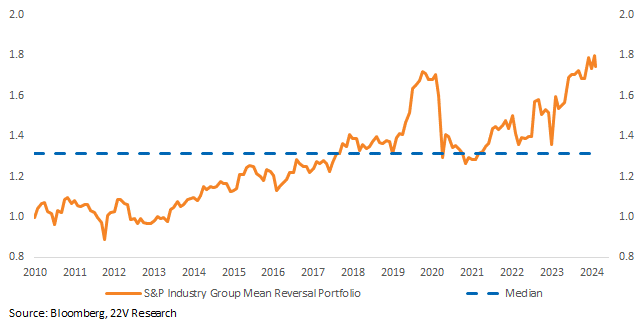
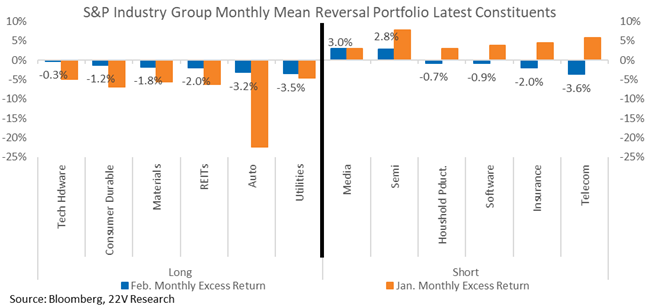
Simply going long the 6 worst-performing industry groups of the prior month and short the 6 best-performing groups has had positive returns consistently since 2021 (10.7% annualized l-s return). Another mean reversal in February would favor long Tech Hardware, Consumer Durables, Materials, REITs, Autos, and Utilities. Media, Semis, Household Products, Insurance, and Telecom would be fades on the month.

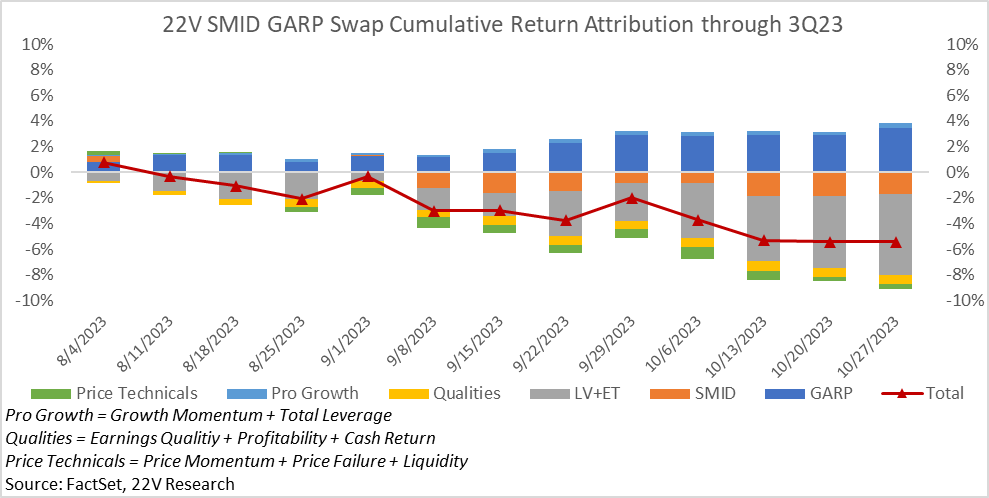
GARP IS “WORKING” – IF You Don’t Have Small Size or Earnings Risk Exposure: During 3Q23, which looks like a similar backdrop to today (for now at least), our SMID cap GARP portfolio was dragged lower by size and risk positioning. The GARP contribution was positive. Bottom Line: If you are confident that economic growth will cool, without a significant tightening in financial conditions, GARP exposure with small size and Earning Risk will benefit. I.e., the pain has already been felt. If you are unsure how the economy will play out or think financial conditions need to tighten materially, GARP + Quality exposure would be best. FYI: GARP + Quality had the best risk-adjusted return during 3Q. We are happy to send both stock lists along…

A graph of different colored bars

Description automatically generated with medium confidence

We close out today with a note on the record $42B 10yr auction and the supply of public debt. A continued rise of the federal debt is a tail risk, but a conventional look at fiscal sustainability does not indicate fiscal consolidation is necessary right now. Details in the full report below…

Full report below…

MARKET VIEWS: Investor focus is on economic growth that is too strong (increasing the risk the Fed needs to tighten FCI), the sharp decline in NYCB, and how far Chinese authorities will go in supporting equities. FYI: John Roque noted yesterday that the “price action suggests a tradable bottom is coming together in China”. Unfortunately, the current backdrop tends to lend itself to mean reversion. Our dummy portfolio that goes long the 6 worst-performing industry groups of the prior month and short the 6 best-performing groups has had positive returns consistently since 2021 (10.7% annualized l-s return). If US monetary policy uncertainty is elevated, which seems to be the case near term, mean reversion is a risk to portfolios.
A graph with orange lines and blue lines

Description automatically generated

If mean reversion trends persist, long Tech Hardware, Consumer Durables, Materials, REITs, Autos, and Utilities would benefit. Media, Semis, Household Products, Insurance, and Telecom would be fades on the month.
A graph of a group

Description automatically generated with medium confidence

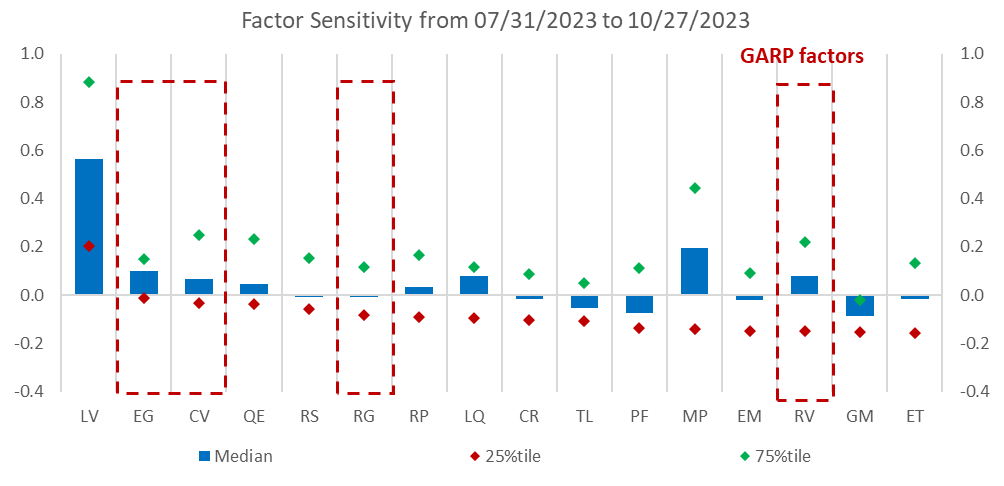
WE STILL LIKE GARP: Our favorite fundamental factor is GARP (see the 2024 Outlook for more details). During 3Q23, which looks like a similar backdrop with today, our SMID cap GARP portfolio was dragged lower by size and risk positioning. The GARP contribution was positive, but exposure to those risk factors hurt. If the market continues to trade like 3Q23, fundamentals will still deliver alpha, but risk exposures will need to be neutralized.
A graph of different colored bars

Description automatically generated with medium confidence

The factor allocation that would’ve generated the best return during 3Q23 was GARP + Low Vol. However, that would’ve required timing the runup in yields. Right now, similarly, Low Vol positioning would require confidence in the path of economic data. If you are confident that economic growth will cool, without a significant tightening in financial conditions, GARP exposure with small size and Earning Risk exposure will benefit. I.e., the pain has already been felt. If you are unsure how the economy will play out or think financial conditions have material risk to tighten more, GARP + Quality exposure would be best. FYI: GARP + Quality had the best risk-adjusted return during 3Q. We are happy to send this list of stocks along…
A graph with different colored squares and dots

Description automatically generated with medium confidence

PUBLIC DEBT: There is a record $42B 10yr auction today, so we thought it would be a good time to talk about UST supply concerns. As Gerard noted in a report yesterday (HERE), estimates of trend growth (g*) is still above estimates of the neutral rate of interest (r*), which would suggest a shortage of public debt. With a continued rise of the federal debt, there is a good chance that the forward path of r* will rise meaningfully above g*, which would be a signal that fiscal consolidation is in fact required. But right now, the conventional way of measuring fiscal sustainability downplays the tail risk. If inflation risk starts to increase again, estimates of r* would increase, and UST supply would be more difficult to absorb. Like we saw in 3Q23.
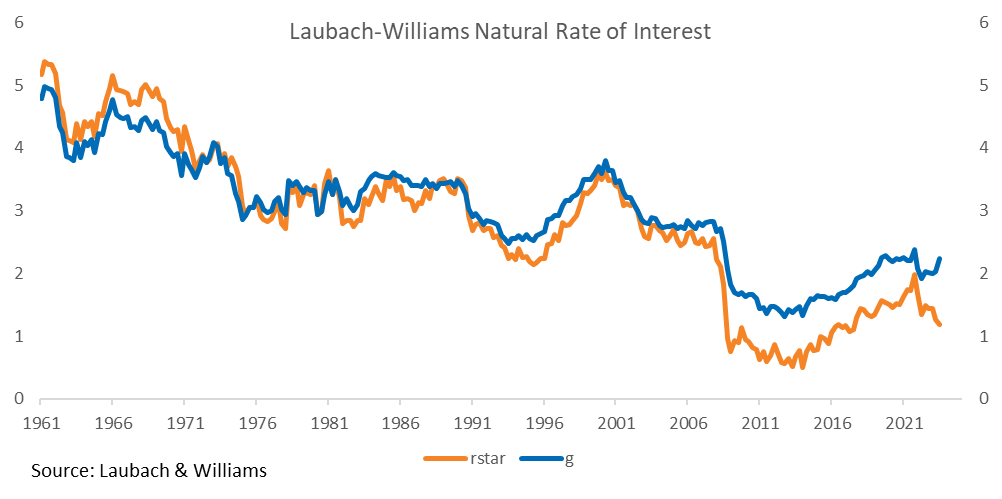
A graph of a graph showing the value of interest

Description automatically generated with medium confidence

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.