SUMMARY: Consumer credit was released a week ago and was significantly lower than expectations ($7.24B vs $20B estimates). Our takeaway is not that consumer credit is a headwind to spending, raising near-term recession risk. Rather, credit is a backward-looking metric that shows credit was not a crutch for consumer spending, which has remained strong.
Earnings season is underway and with it, anecdotal evidence about the health of current consumer trends. It makes sense to look for signs of weakness/change in the current backdrop, but conflicting anecdotal evidence (which we will get through EPS season) is why we rely on aggregated and objective sentiment metrics.
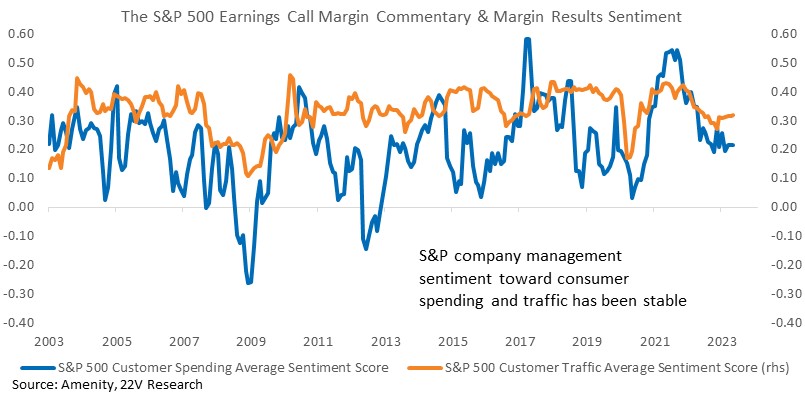
Management sentiment toward consumer traffic and spending, measured using the Amenity natural language processor, is well off its 2022 high but has been stable for the past few quarters. That reading is consistent with the still healthy level of consumer spending, low unemployment, earnings, etc. We will be monitoring sentiment shifts throughout reporting season.

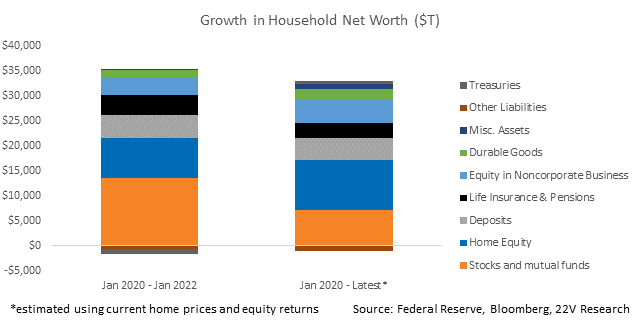
In terms of the outlook for consumer spending, we put more weight into the real labor income proxy and growth in household net worth (both economy-wide metrics). The real labor income proxy = real wages * hours worked * number of jobs, and is currently growing above 2% thanks to job growth and now fading inflation (HERE). Household net worth is still up ~$35T since pre-covid, despite a hit to equities during the bear market. Both economy-wide metrics suggest the consumer is ok. The threshold for risk-on internals is not extremely strong demand growth (that would be a problem for inflation/the Fed), but rather pushing near-term recession risk out.
Full report below…
MARKET VIEWS: We had a few clients flag Richemont earnings to us yesterday (HERE). The Swiss luxury brand missed because of weakness in China (a theme Michael Hirson has been all over, latest thoughts HERE) and weakness in the US, a theme we have been pushing back on. But BoFA this morning (and JPM last week) reported US consumer health remained strong (HERE). It makes sense to look for signs of weakness/change in the current backdrop, but conflicting anecdotal evidence is why we rely on aggregated objective sentiment metrics. Management sentiment toward consumer traffic and spending, measured using the Amenity natural language processor, is well off its 2022 high but has been stable for the past few quarters. That reading is consistent with the still healthy level of consumer spending, low unemployment, earnings, etc. We have limited data for this quarter, but macro data has not supported a fall off since last quarter. We will be monitoring sentiment shifts throughout reporting season.
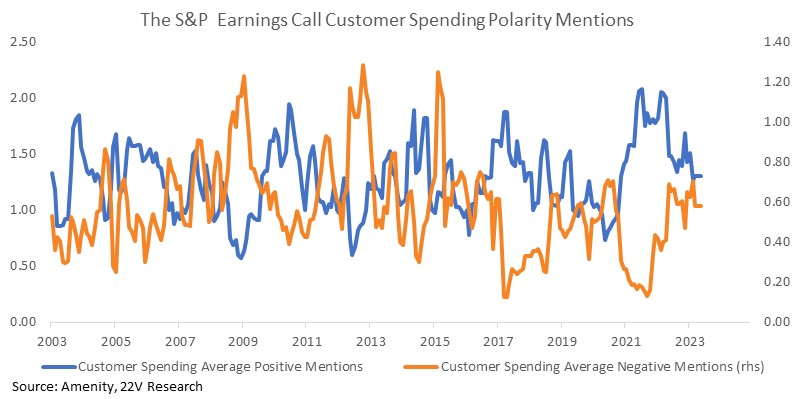
The moderation in sentiment towards customer spending has been driven by both a decline in positive mentions and an increase in negative mentions. Again, the overall level is consistent with a healthy level of spending. The moderation is also consistent with below-trend demand growth.
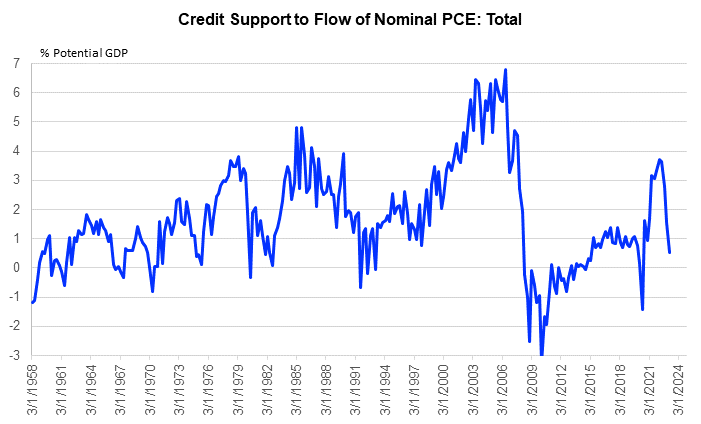
We’ve also had consumer credit flagged to us. Consumer credit was released a week ago, coming in significantly lower than expectations ($7.24B vs $20B estimates). Our takeaway is not that consumer credit is a headwind to consumer spending, raising near-term recession risk. Rather, credit is a backward-looking metric that shows credit was not a crutch for consumer spending, which has remained strong.
Source: Front Harbor, Federal Reserve, BEA
For the outlook for consumer spending, we put more weight into the real labor income proxy and growth in household net worth (both economy-wide metrics). The real labor income proxy = real wages * hours worked * number of jobs, currently growing above 2% thanks to job growth and now fading inflation (HERE). Household net worth is still up ~$35T since pre-covid, despite a hit to equities during the bear market. Both economy-wide metrics suggest the consumer is ok. The threshold for risk-on internals is not extremely strong demand growth (that would be a problem for inflation/the Fed), but rather pushing near-term recession risk out.