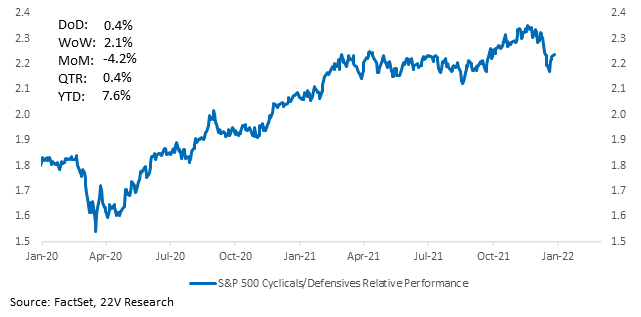
SUMMARY: The reversal in Cyclicals relative to Defensives will continue in part because it is tough to expect Defensives relative gains to continue after its 96th %tile move MoM, and in part because Omicron trends are improving (overnight a South African study suggested Omicron boosts immunity to older variants which is important if true) and 3 Fed rate hikes are priced in for 2022. Quickly on the Fed, do not expect a sharp increase in the Fed funds futures curve that would lead to lower growth expectations and Defensive outperformance, near term. An accelerated rate hike path is a risk if core inflation trends prove more intense than expected, but we won’t have enough information on that for at least 4-6 months.
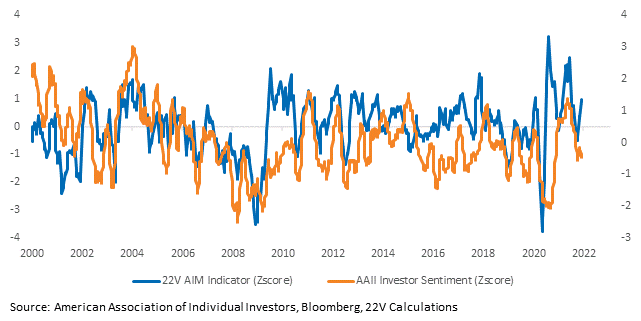
Sentiment: The spread between sentiment, measured by the AAII Bull Bear spread, and the breadth of economic data has reached unusually wide levels (currently its 8th percentile). As Omicron/Fed risk fears fade, negative sentiment should reverse and catch up to hard data. Stronger than normal equity returns on a 1 and 3 month basis typically follow periods where then spread between sentiment and economic data is extreme.

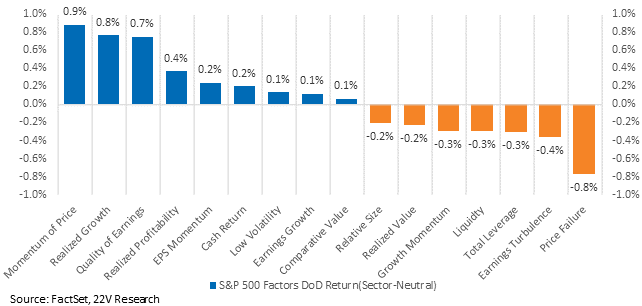
Factors: Despite a risk-on Sector backdrop, the factors that benefit from a higher real fed funds rate outperformed yesterday and those that don’t underperformed (high leverage, low liquidity and earnings turbulence underperformed). The Fed wants real rates higher and that is likely to be the case for a few years. Investors need to position for higher real yields.
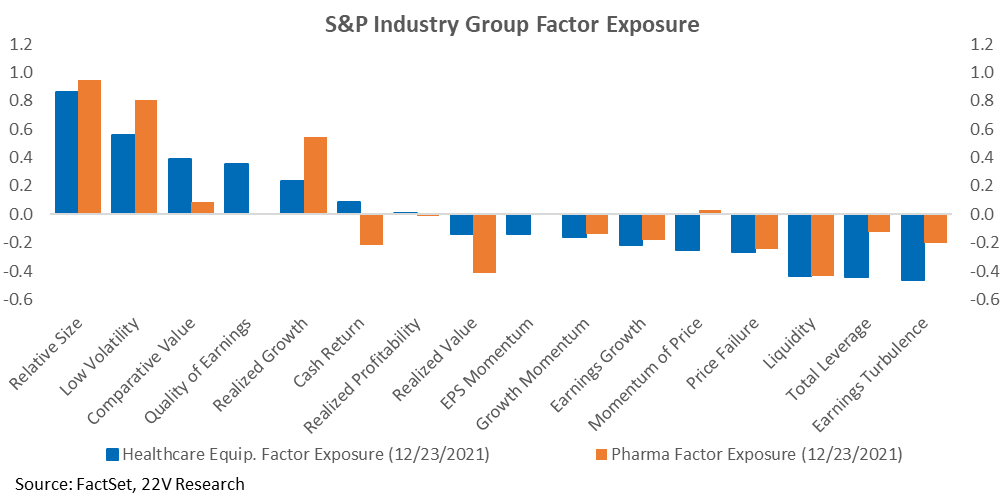
Healthcare Spotlight: Healthcare contains the lowest correlation, least macro influenced S&P industry groups, leaving more opportunities for outperformance through single stock selection. That is a major part of the reason we upgraded the sector on 12/7 (more on 12/6 too) At the factor level, Healthcare industries tend to be levered to Relative Size (large companies), lower volatility names. Healthcare Equipment is more exposed to Value and Cash Return, while Pharma tends to be more skewed toward Growth names. All of which should benefit from an increase in real yields. Which is highly likely to happen next year. Healthcare will suffer a bit in January as other Defensives lag, but should differentiate itself relative to Staples & Utilities given its relative lack of macro influence (Staples & Utilities have much more exposure to rates moves).
Full Report Below….
MARKET VIEWS: The sector reversals that started last week continued yesterday with Utilities, Staples and Communications underperforming and Energy, Tech and Materials outperforming. We think the reversal in Cyclicals relative to Defensives will continue after the 96%th tile MoM outperformance of Defensives. It’s tough to expect Defensives to outperform with Omicron trends improving (this was important overnight on the Omicron front, a South African study suggested Omicron boosts immunity to older variants. Important if true) and 3 Fed rate hikes priced for 2022. It’s tough to expect a sharp increase in the Fed funds futures curve, that would lead to much weaker growth expectations and Defensive outperformance, near term.
On the overall market, sentiment is unusually weak relative to the breadth of economic data. That typically leads to much stronger than normal forward returns. The spread between sentiment and data has been wide for a few weeks but was overwhelmed by Omicron/Fed fears. As those fears fade negative sentiment should reverse some and lead to stronger than normal support equities on a 1 and 3 month basis.
The risk-on move in Sectors is not translating into risk-on Factor moves. At least not yesterday. That fits with our longer-term view that the economy will be firm and real yields are headed higher. In short, the factors that benefit form a higher real fed funds outperformed yesterday and those that don’t underperformed. Yes, supply chains are improving at that will lead to lower input prices (see Dallas Fed yesterday. Also, Japan IP was much stronger than expected on stronger Auto production), but core inflation is still likely to be close to 3% to end 2022. The risk is more not less than 3 rate hikes in 2022.
Healthcare: We upgraded Healthcare on 12/6 and we wanted to update our views as john Roque sent us some Healthcare charts yesterday (at the end of this report). Over the past month Defensives have led market internals and Healthcare has been the best performing sector (S&P 500, eq weight).
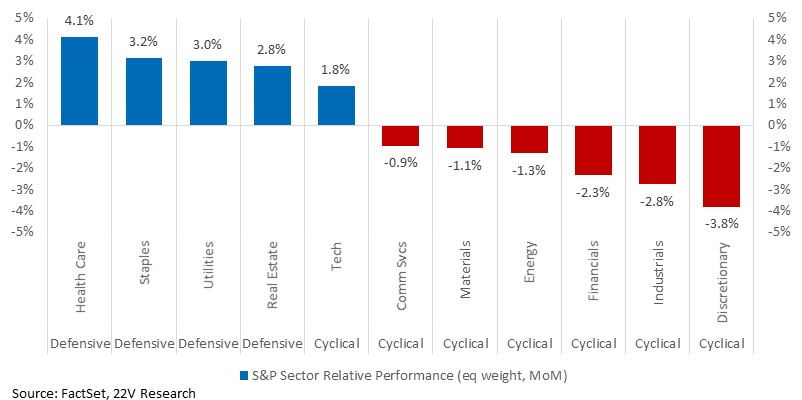
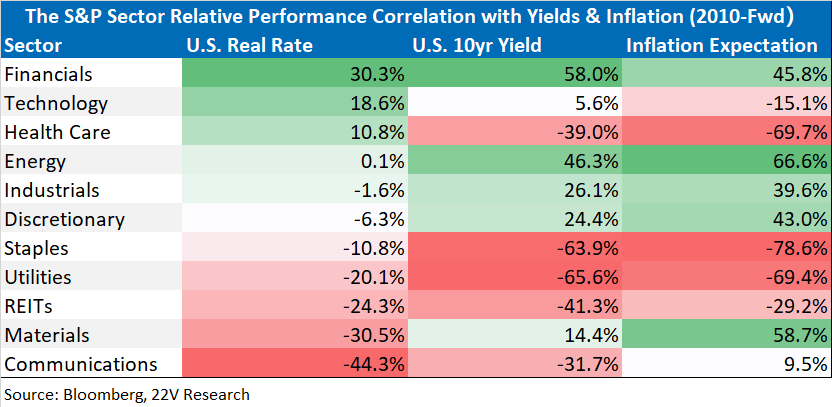
Defensive will face headwinds as Omicron risks ease and bond yields move higher, but Healthcare tends to be uncorrelated to rising real yields while benefitting from falling inflation expectations.
At the factor level, Healthcare industries tend to be levered to Relative Size (large companies), lower volatility names. Healthcare Equipment is more exposed to Value and Cash Return, while Pharma tends to be more skewed toward Growth names. Low Volatility faces headwinds in 1Q which should be considered when screening for Healthcare longs.
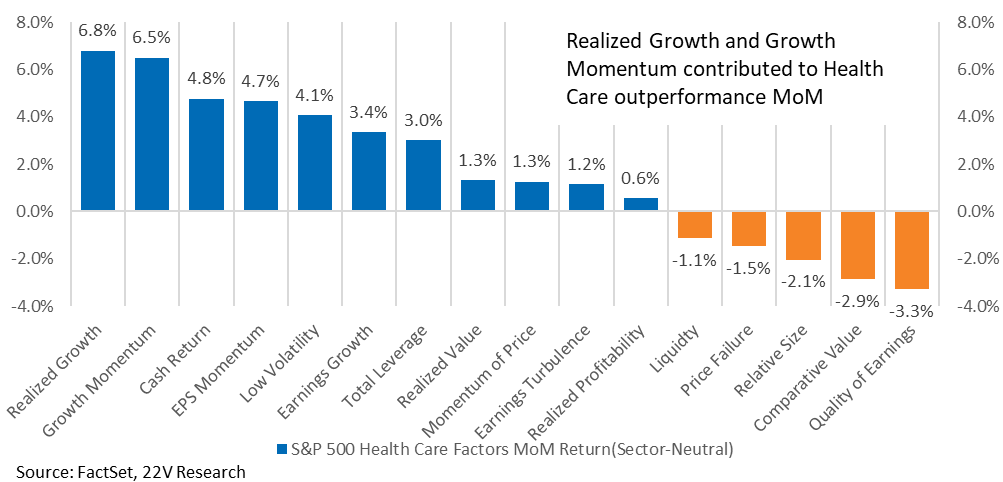
Over the past month, Healthcare stocks with higher Growth, Momentum and Cash Return scores have performed well. Value names within the sector have struggled, likely a result of the overall risk-off nature of the early December market rotation.
Healthcare contains the lowest correlation, least macro influenced S&P industry groups, leaving more opportunities for outperformance through single stock selection. At the industry group level total sentiment is weak within Healthcare Equipment and earnings sentiment is negative across Equipment and Pharma names. Weak sentiment also argues against taking positions in the group as whole and favors stock picking.
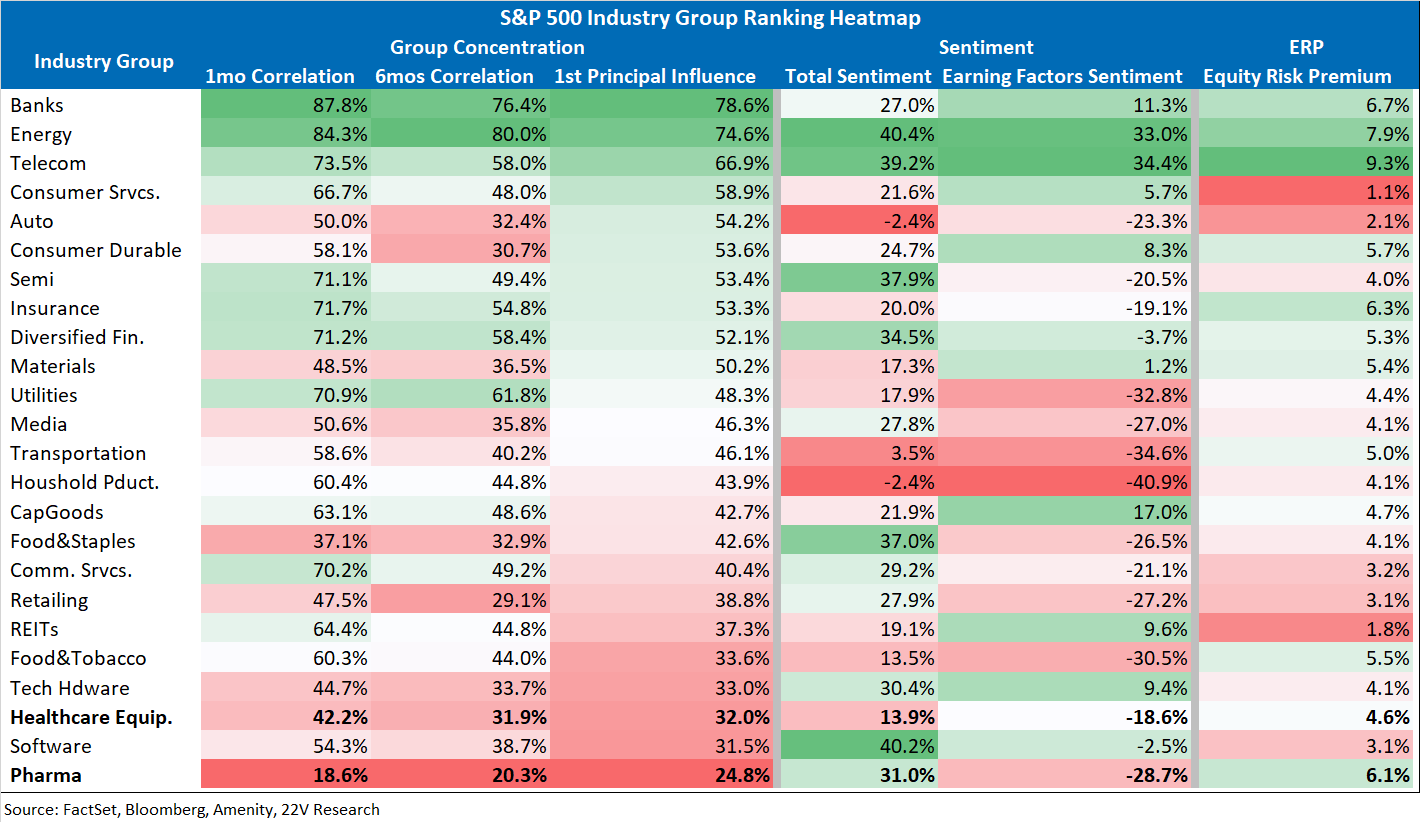
BELOW ARE SOME OF JOHN ROQUE’S FAVORITE HEALTHCARE CHARTS.
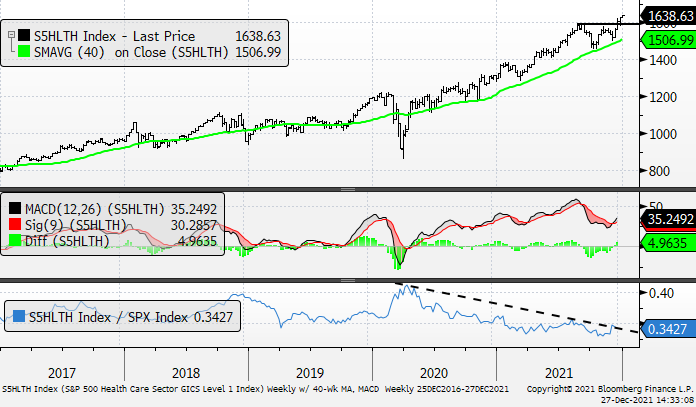
S&P Health Care Sector: Weekly chart with 40-Week MA (top), Weekly MACD (middle), and Weekly Rel. to S&P (bottom). Absolute action is strong, and the Sector has a Technical Score = 4, our highest absolute Technical Score. Weekly momentum is positive and has recently inflected upward within positive territory. Relative action vs. the S&P has improved a bit of late, too, as the Health Care Sector is up 6.3% in the last month far outpacing the S&P’s 1.7% gain.
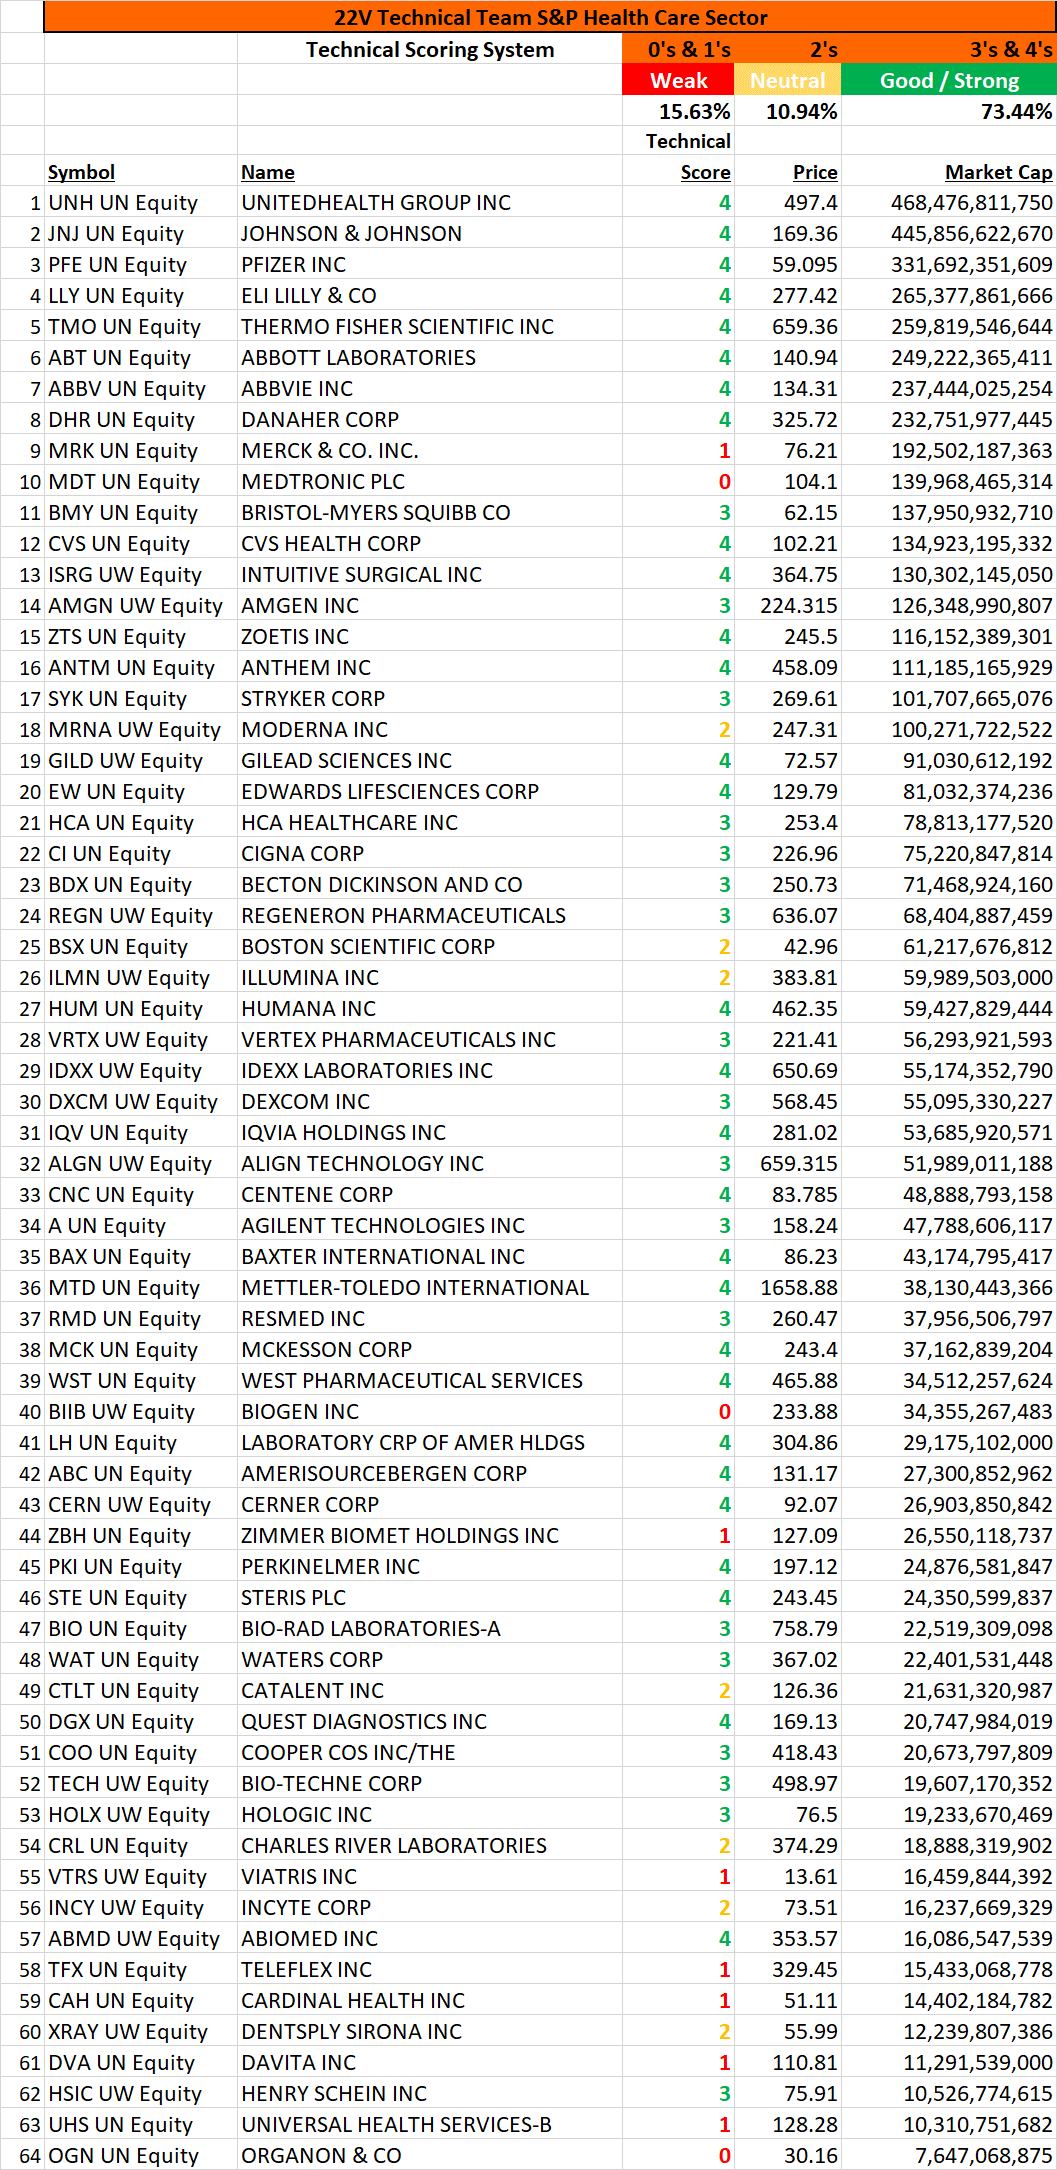
Technical Scores for the components of the Health Care Sector shake out as follows. Outside of the Utility and Real Estate Sectors, Health Care has the strongest internal scores. Please see below for some of our favorite stocks in the sector.
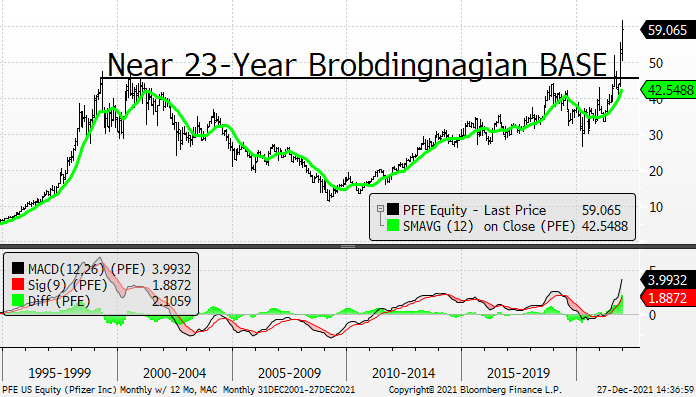
We continue to like Pfizer and realize that it is up sharply since completing its near 23-year Brobdingnagian BASE.
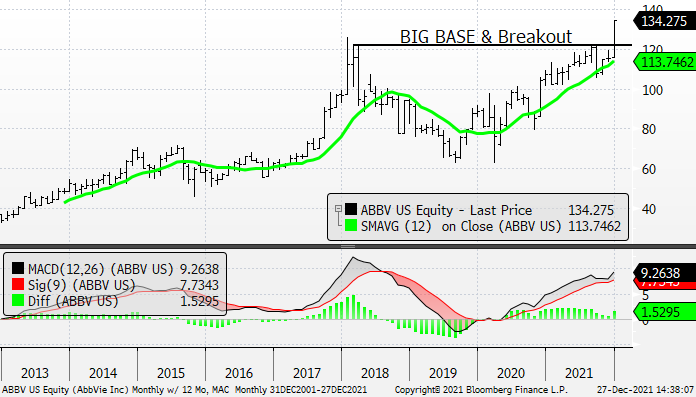
AbbVie is another of our favorites given its BIG BASE & Breakout style.
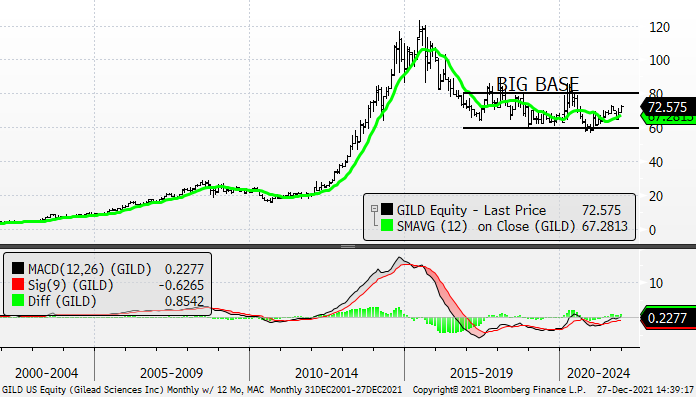
We also like Gilead which we believe is building a BIG BASE.
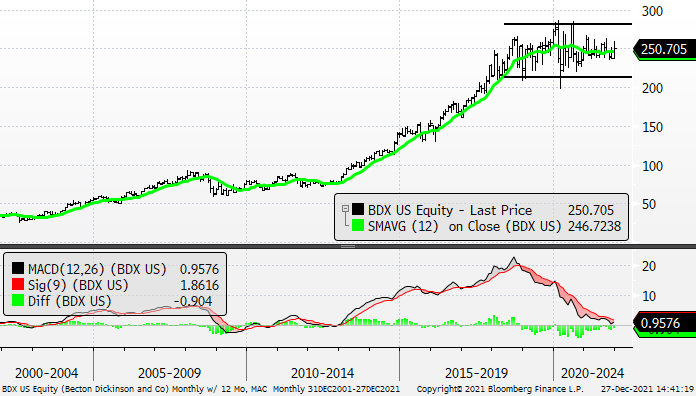
Becton Dickinson is also BASING and its monthly MACD (bottom) is trying to stabilize at the zero line.
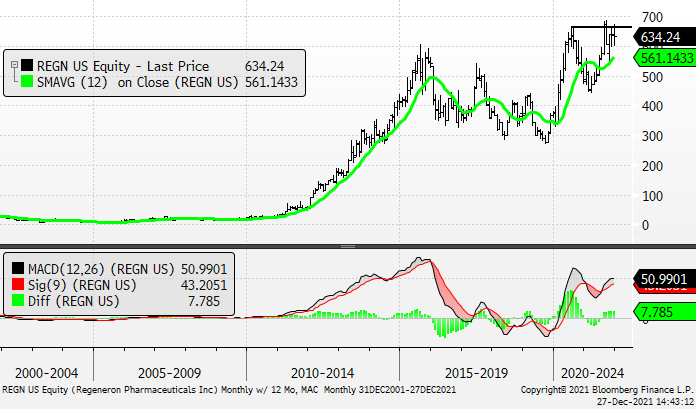
Regeneron is also in a good spot.