

Important news this week and thoughts:
- Anthropic’s IPO was confirmed this week to be live by Thanksgiving and most likely the week of Nov 9th. The S-1 should be forthcoming by mid-October given planned October 14th investor meetings. The S-1 and detailed review of the business and investor interaction with the management team will be a significant driver of AI-related names.
- Trump’s naming of an “SI” Czar this weekend will be notable to see the market’s reaction in a pro-SI and competitive angle. AI regulation continues to evolve. Trump renamed AI to Super Intelligence (SI) this week as well as naming Deputy of National Intelligence Jay Clayton as SI Czar. Critically, Trump is making the case, along with OpenAI’s Altman echoing similar calls, that regulation needs to be lighter and existential risks may not be as large as has been made out to be recently. Clayton’s recent commentary points to national security and sovereign competition around AI being a primary concern and focus.
- Space economy names were down, but critically this week we saw a positive Starship 3 test combined with Google’s first ODC reference TPU test. It remains early on ODCs, but what is clear is that SpaceX controls the pipeline to space, and the Falcon 9 retirement and timing for Starship 3 expansion are creating less supply for those that need rides to space to launch products.
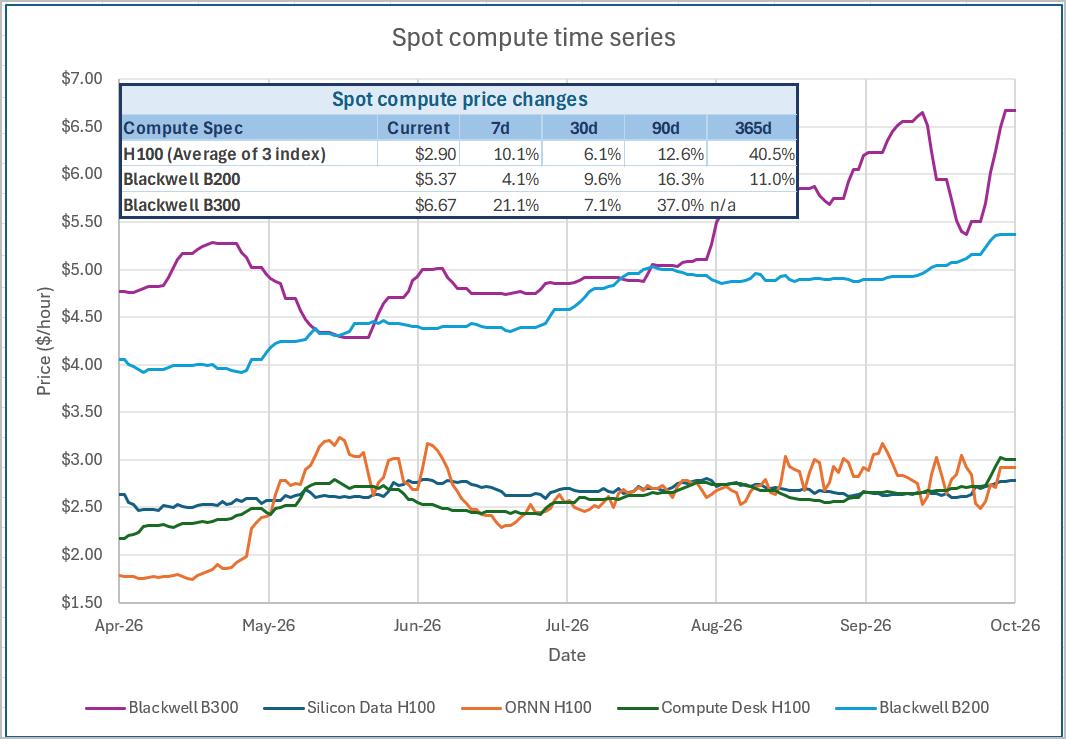
- Compute spot prices have risen across all genres over the past week, notably Blackwell 300, up 21% and back to prior highs. H100 is also back to prior highs and holding strong. While we wait for CFTC’s review and new futures products possibly late October / early November, it appears that the compute market remains very tight. Agentic demand for enterprise as well as consumer against a more challenging data center build backdrop is driving price.
Source: Bloomberg; 22V Research
Weekly Performance
Source: Bloomberg; 22V Research
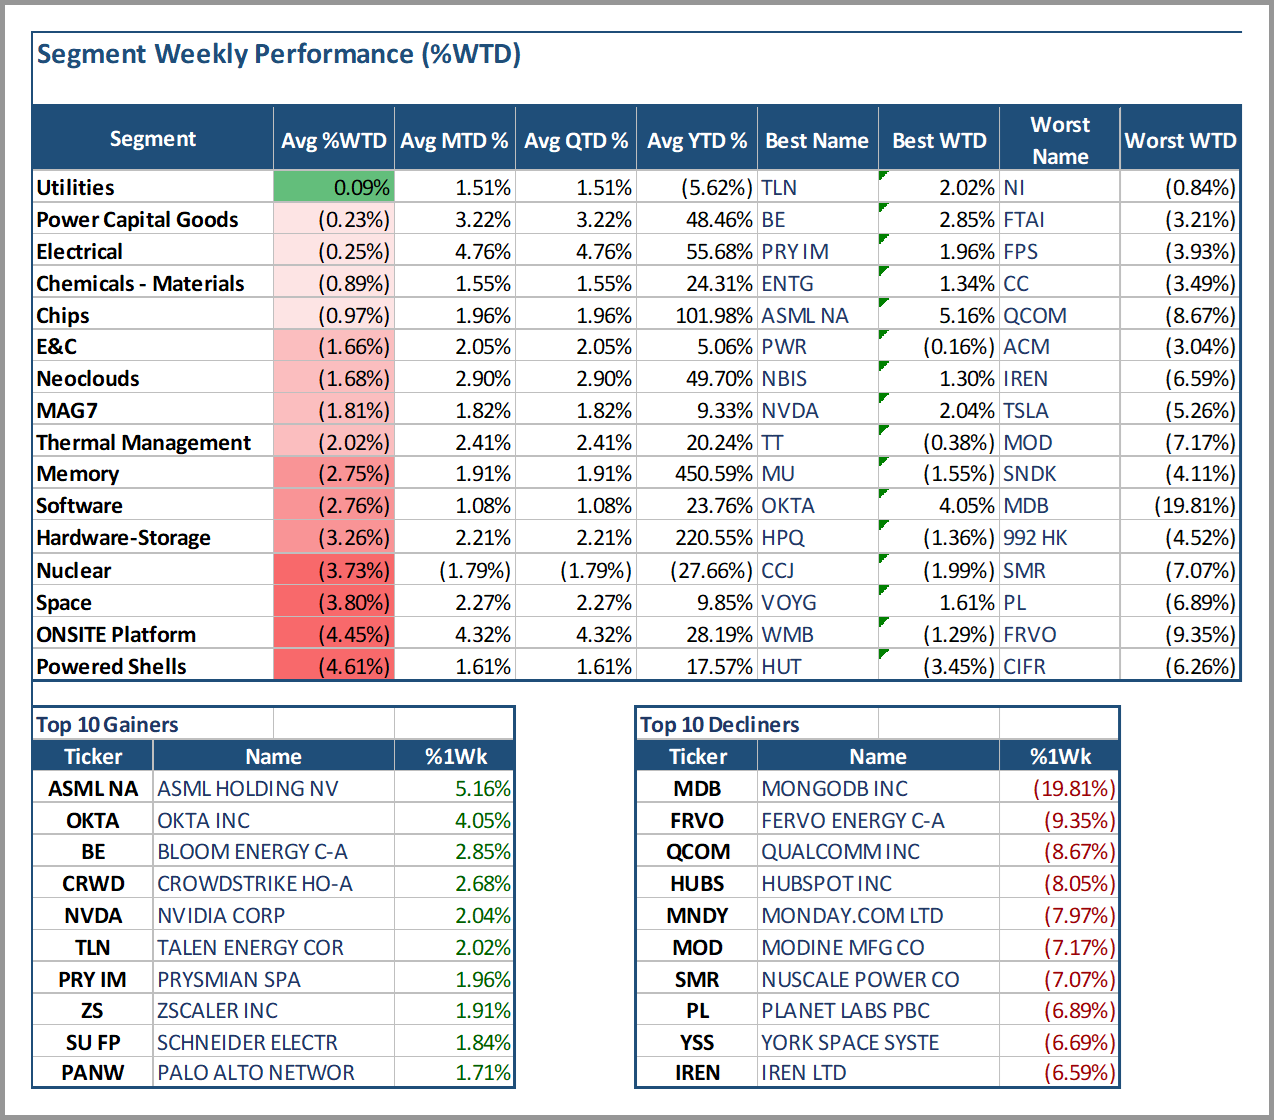
Notable points on performance:
- Weak performance across AI-related names connected in part to persistent concern over higher interest rates. Additionally, the week started out with OpenAI delaying a model release for security risks, putting pressure on sentiment for the buildout.
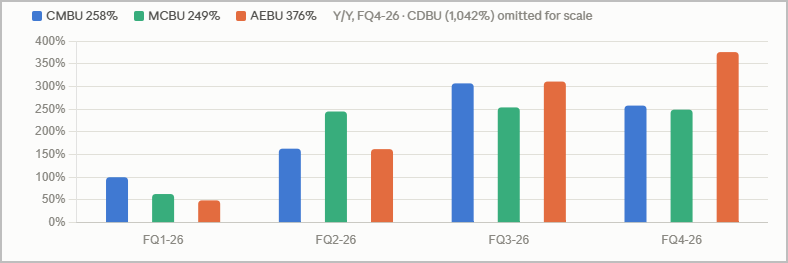
- MU reported a strong quarter with a solid outlook and traded roughly flat from its report. There is noticeable debate around rate of change going into 2028 for memory names. One aspect of the report that stood out was related to the growth of memory content for autonomous vehicles, which is showing in accelerating y/y growth in that division.
Source: Company reports; 22V Research
Recent Research:
The AI Trade: Updated “Coiled Spring” Report and Data, 10/2/26 — The coiled spring study is expanded to 91 names, with updated top and bottom composite ranks for current prices.
Midterms and the AI Buildout: Status, Moving Pieces, Shrinking Map, 10/1/26 — Data center pushback likely cuts supportive states from 27 to 15 post-midterms, tightening compute further and favoring scalers and powered shells with permitted sites.

