Back Economic Research

Gov. Waller Sees Inflation-centric Risks

Published on July 6, 2026

∙ Download the PDF Report

By

Peter Williams

  • Comments from Gov. Waller today echoed those he gave in late May, signaling an important hawkish swing from one of the higher-beta voices at the Fed.
  • He gave no explicit policy commentary but his tone around the risks to the Fed’s dual mandate is clear enough; the implications for the direction of policy depend then on the data and where his baseline view on the neutral rate is (something which may have also been shifting given the recent data flow).
  • There is the data itself but also the underlying slower moving risks from another round of inflation, now with a “stabilizing” labor market, as consumers and firms are now more used to higher inflation and passing-through costs and bargaining in a world when it is a part of economic life.
  • Waller defended forward guidance’s historic use, but suggested that in the present moment scenario analysis seems to be a far more helpful tool that averaging across a highly uncertain future and calling that a base case. The dot plot’s base case-centered communication strategy seems ever more at risk although it is unclear what, if anything, might replace it.

After being notable more concerned about labor markets for much of 2024-25 and being willing to tolerate a “longer movement back” of inflation towards the Fed’s 2% target as a result, the “risks have completely flipped around.” As is clear enough looking at all the data over the past 9 months, the “labor market seems to be stabilizing in the U.S., inflation’s been taking off. So then that changes how you might want to think about policy.”

In a set of comments which could apply to almost anything in the macroeconomy over the post-covid cycle, Waller noted the importance of unique initial conditions in assessing the likely impacts of monetary policy surprises. Particularly important to the current risks around inflation is concept of ‘rational inattention’, where households and firms pay little attention to small shifts in the economy but large enough shocks can jolt them into action. “If big shocks lead firms to increase the frequency of price changes, the Phillips curve steepens, which changes how monetary policy actions are transmitted to inflation and the real economy” and would potentially be a sharp reversal from the 20y before covid.

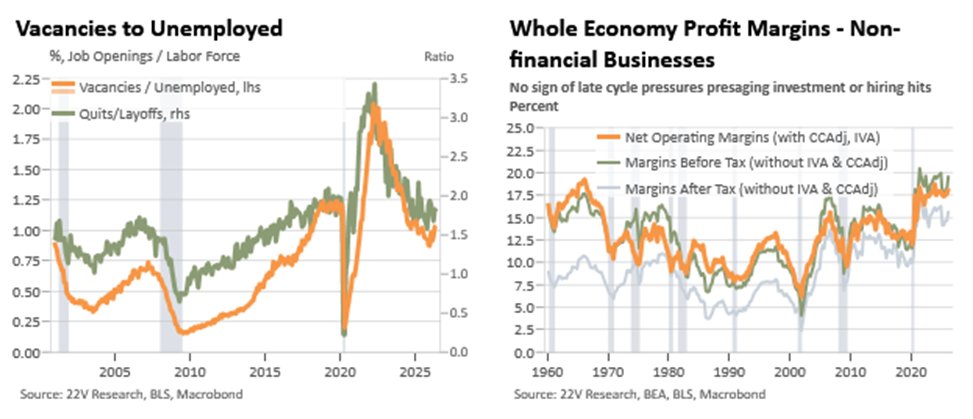
Given the recent move higher in inflation, years into a continuous overshoot of target, the mention of rational inattention dynamics is naturally a hawkish one. Waller’s comment about a steeper Phillips Curve could just as easily apply to the responses of surveyed inflation expectations to realized inflation or bargaining positions around price shocks and firms’ willingness to pass through cost shocks (something elevated margins suggest remains the case even with tariffs, the war, and AI boom). Research from the Boston Fed last year found exactly this result, with price shocks to flexible prices having many multiple times larger impacts on sticky prices than pre-covid, although this effect had shown some signs of normalization as inflation came back down in 2023-24.

Waller seems at least open to the idea of toning down the Fed’s explicit forward guidance. While noting that it can be a “valuable tool” that can help change economic conditions more quickly that policy rates alone, it “is more art than science, and there have been times when it has hindered, rather than helped, policymaking.” In certain circumstances the optimal choice may be to use scenario-based forward guidance, which is much clearer when different economic scenarios each with “a significant probability of occurring and requiring different policy paths.” Alternatively, it may be “best not to use it at all.”

Explicit forward guidance is relatively recent invention and Waller made was clear to note that even if it may not be helpful, it remains “important to communicate your reaction function — be clear about what your objectives are and how you would respond to the data.” When considering the dot plot, as a base case driven tool, this suggests he may be open to some tweaks or wholesale shifts in the Fed’s approach but seems unlikely he would fully jettison the current open communications regime and some sort of economic and policy outlook.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.