Back Economic Research

No Fireworks for the June Employment Report

Published on July 2, 2026

∙ Download the PDF Report

By

Peter Williams

No Fireworks for the June Employment Report

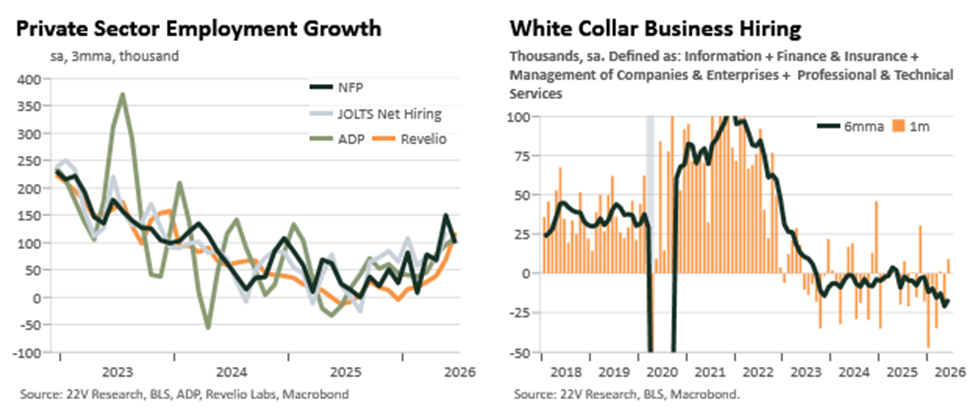
  • After accelerating through most of the spring, NFP growth sharply decelerated in June (+57k) and saw notable downward revisions to the prior months. The breadth of hiring still looks decent and we saw the best month (still soft) of white collar job gains since Nov.
  • Outside of health care, wage growth seems to gradually stabilizing or perhaps slowly reaccelerating across the economy.
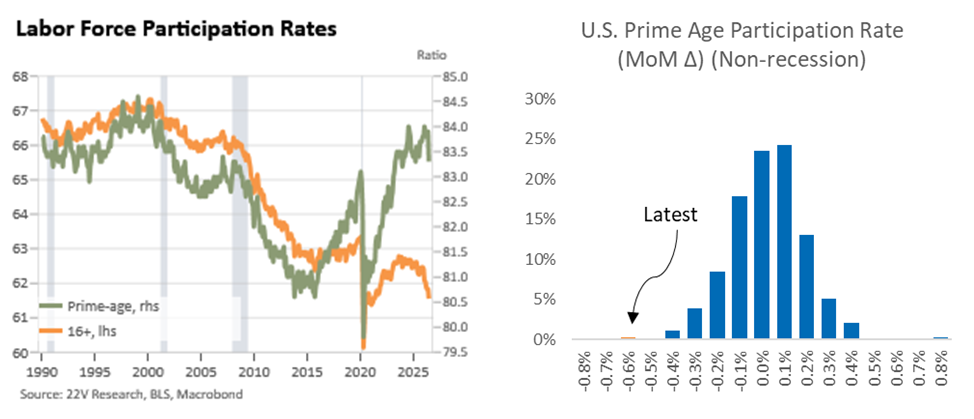
  • The household survey seems quite wonky. The urate dropped to 4.19% even as the prime-age employment to population rate sharply fell. LFPR surprised sharply to the downside (98th %ile move), largely due to 25-34yo, in what seems like statistical noise.
  • Given a 4.2% urate, NFP trend around 100k, and wage growth that seems steady enough those with more hawkish views seem unlikely to change them in response to this one release. The market was right to see this as making the economic case for July less likely (to me, July has always been much more about a choice to reestablish preemptive hawkish credibility more than the m/m data flow), but it does little to change the odds that we eventually start to hike.

Hiring trends have been quite volatile in recent months. The underlying pace now seems a bit more consistent, on a 3mma basis, with the signal from the ADP, Revelio, and JOLTS data all of which had been closer to 100k than the 188k 3mma that had been reported by NFP as of the prior release.

Sectorally, healthcare continues to lead but decelerated on the month. Leisure and hospitality’s strength in May whipped down to -61k in June, on what seems to be odd Memorial Day-related seasonals far more than World Cup related demand not being realized. I wouldn’t read much into this given the extreme strength related to travel demand we’ve heard from corporates through (write up from May here, with a bit more recent color here) and very strong OpenTable and TSA data. Spirit’s bankruptcy and war-related volume declines could be playing a bit of a role here as well, but nothing from corporates suggests soft or even softening travel demand, Broader cyclical hiring seems mildly positive in recent months, and breadth is above 50 but well below the usual pace during an expansion (as should be expected if breakeven payroll growth is quite close to 0). White collar hiring saw its best, and only second positive, month of the year. Softness there seems to have been worst around the turn of the year, which also lines up with what S&P1500 earnings call transcript show; on that front Q2 showed the fewest layoff mentions since mid-2022.
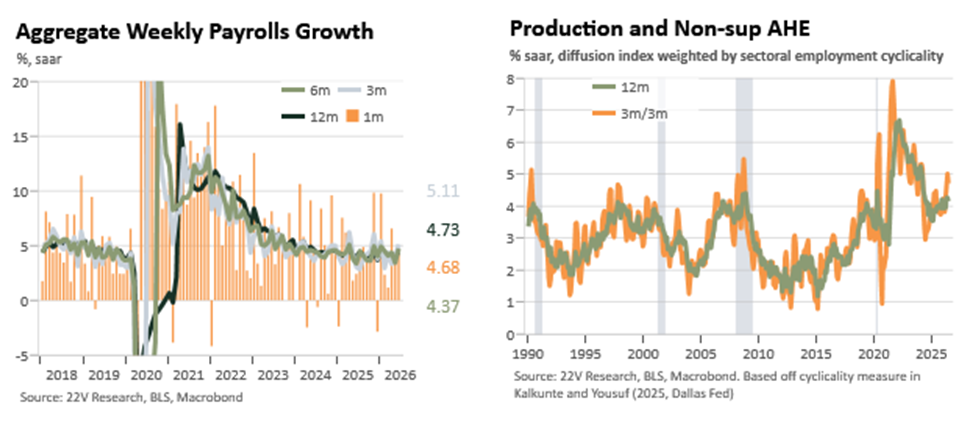
Wage growth has been decelerating a bit for much of this year on a topline basis that has overstated the degree of downside cyclicality there. Aggregate take home pay growth seems to have troughed and seems steady around 4.5-5% now. Much of the topline decline has been due to health care wages which are much more policy driven than cyclical. Our measure of cyclical wage growth, which is a diffusion index that weights sectors based on their employment cyclicality, has cooled a bit in recent months but shows a clear bottom and reacceleration over the past year.
The household survey told a messier and noisier seeming story. The unemployment rate dropped to 4.19%, from 4.30%. This was largely due to an oddly large drop in the labor force participation rate. The overall decline with in the 98th-%ile. This drop was largely concentrated in 25-34 year olds, which raises some quite obvious questions about sampling issues or just noise, as school related seasonal issues seem much less likely to apply. I am very skeptical that one of the largest ever drops in the prime-age employment to population ratio and participation rates took place in any real underlying cyclical sense; since the early 1960s, the 0.6% fall in the PALFPR ties for the largest ever monthly drop outside of covid and is by far the worst ever non-recessionary print.

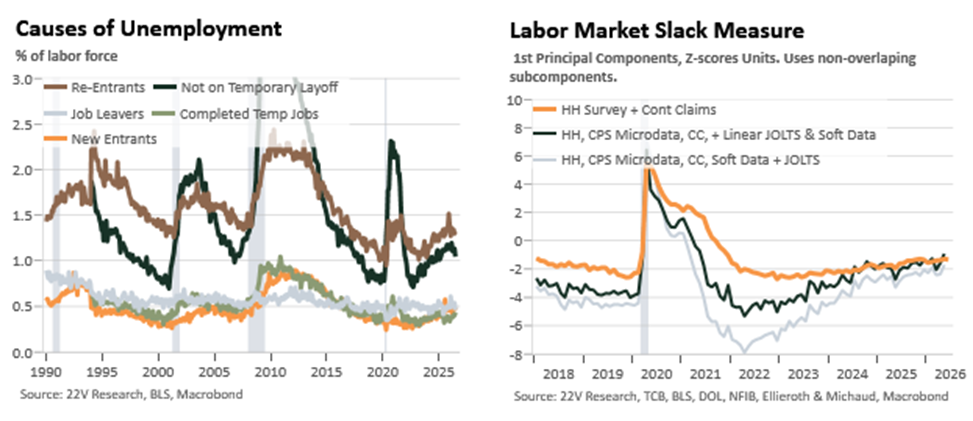
Other less obviously impacted measures of slack looked ok though. The unemployment rate was down but with the necessary caveats around participation rates and employment levels above. The composition of those unemployed has been improving across categories with the exception of workers on temp layoff; the largest drivers of the urate over the cycle are labor force reentrants and those on permanent layoff, both of which have seen improving dynamics recently. Part-time for economic reasons and durations of unemployment all improved on the month.

Overall, our composite measure of labor market slack that incorporates today’s data + jobless claims was slightly improved on the month.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.