Back Portfolio Strategy

Capex Commentary Leaves AI Idio Driving Factors and Themes

Published on January 29, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

DAILY STRATEGY: Capex commentary from Meta, TSLA, and MSFT suggests AI idio, which is driving current factors and themes (Earnings Mo, Earnings Growth and Price Momentum), will continue. The AI theme, and who benefits from the AI capex going forward, remains the largest driver of factor and market cap calls (we are long this theme). The macro backdrop is supportive of a broadening out of returns, but the main driver of returns has been related to AI themes.

By extension, IF 10yr yields were to increase to 4.5% or above, we would not necessarily fade small caps or riskier factors. The Integration of AI into physical products has favored industries in smaller caps and Deeper Cyclicals – power providers, semis, cap goods, and tech hardware. While that support remains, and capex plans indicate it does, we would not abandon the broadening out trade just because the 10yr yield moved up to 4.5% or above.

A few key points on this:

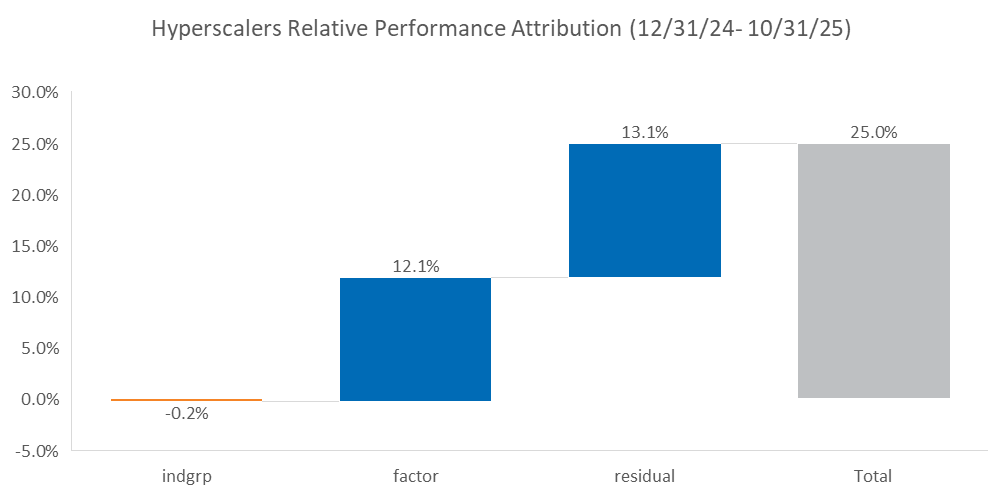
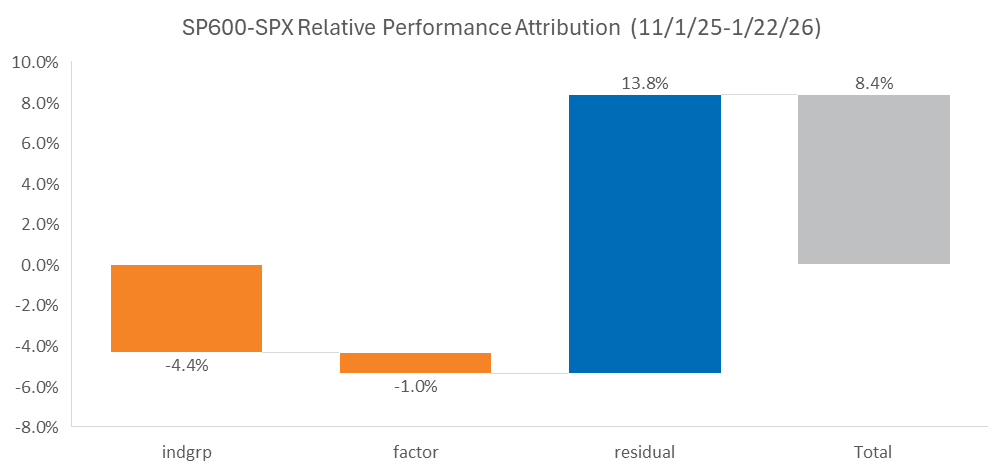
  1. From 1/1/2024 through 10/31/2025 the main driver of Hyperscale’s returns was the residual or idio. Not factor or industry group exposure. 10/31/2025 through yesterday, residuals have worked against the Hyperscalers (performance lagged). Within small caps, idiosyncratic risk, rather than industry group and factor exposures, is responsible for all outperformance.
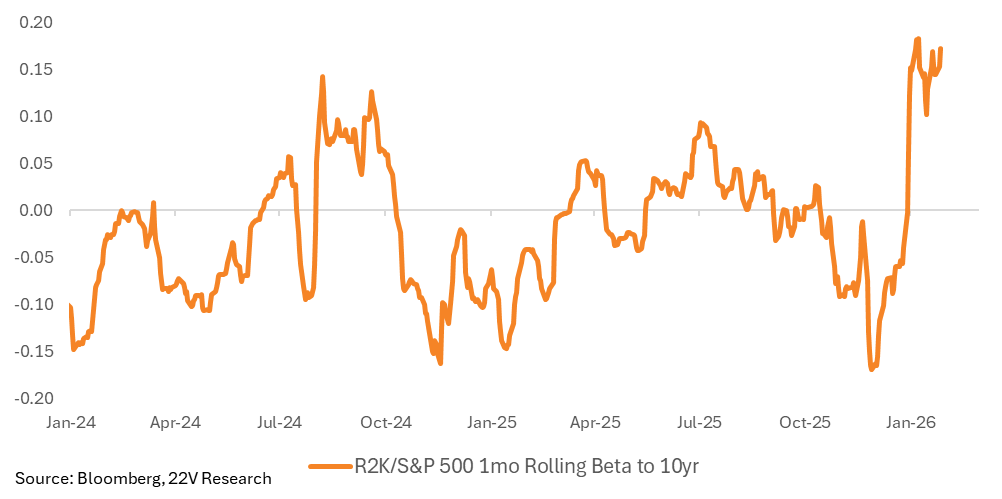
  2. Small cap beta to 10yr yields is very volatile; the lack of a stable relationship implies an uncertain impact from higher yields. The beta is positive right now (higher yields = small cap outperformance).
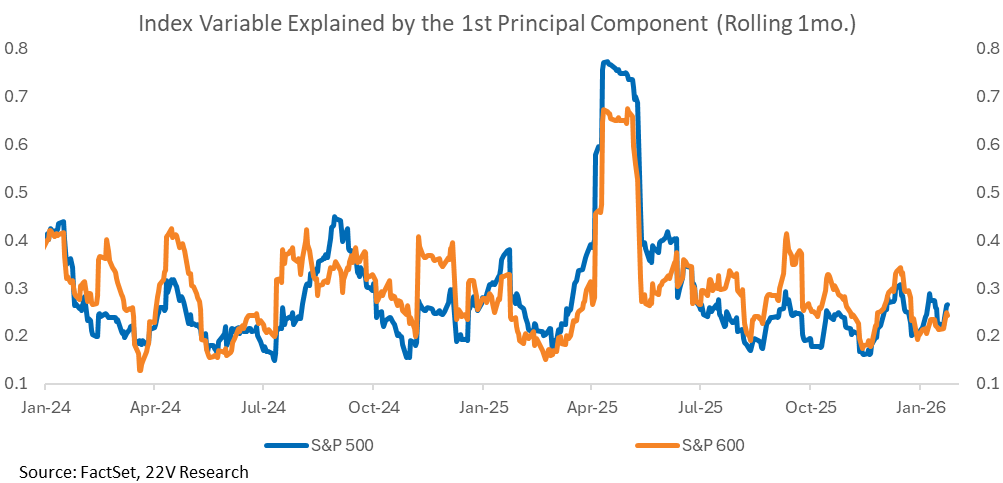
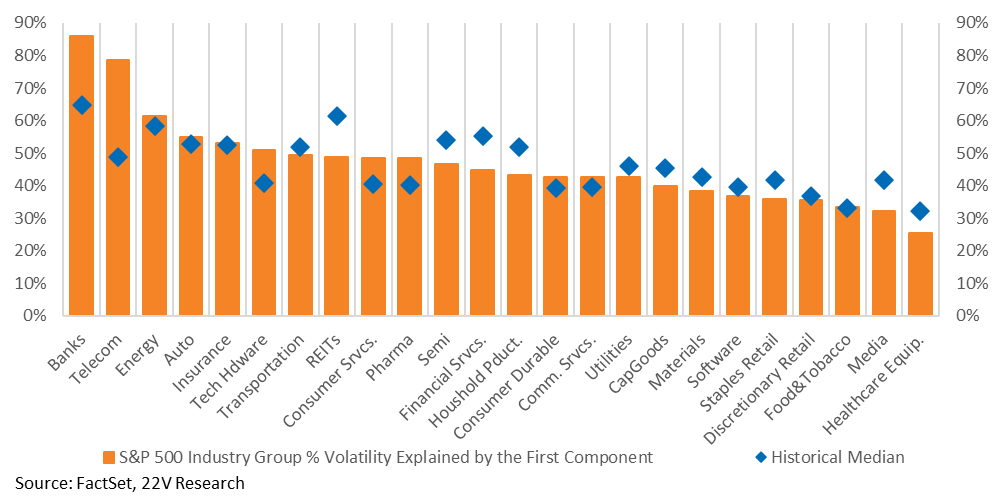
  3. The volatility in large AND small caps explained by the 1st principal component – our proxy for macro impact – is near recent lows. Macro doesn’t seem to explain the volatility.

If Mega cap stocks AND Capex related names outperform together, being long small caps should not work as well on a relative basis. If mega caps outperform, it would indicate that investors think that Hyperscaler earnings are more certainty, or that differentiating between winners and losers with-in Hyperscalers and other Tech related AI names is easier. If that happens Banks/Retail (we are long both) would likely suffer SOME relative.

Investors have highlighted to us the desire to diversify away from Hyperscalers and broader tech AI names as picking winners and losers has become more difficult. It is reasonable to assume Retail, Banks, and Staples benefit from that diversification at the start the year. We would stay long Retail and Banks but remain relatively short Staples. The fundamental case for Banks and Retail is still compelling (see HERE and HERE)

Charts…

Small cap beta to yields is very volatile; the lack of a stable relationship implies limited impact. And the beta is positive right now (higher yields = small cap outperformance).
A graph with numbers and a line

AI-generated content may be incorrect.

Macro influence on index returns is low right now. The volatility in large AND small caps explained by the 1st principal component – our proxy for macro impact – is far off levels hit over the tariff announcements and aftermath, for reference.
A graph of a graph showing the same graph

AI-generated content may be incorrect.

Idiosyncratic risk, rather than industry group and factor exposures, is responsible for all of the small cap outperformance of large caps since the AI hyperscaler trade started diversifying in the fall. From 2024 through 10/31/2025 idio was the major driver of Hyperscaler outperformance.
A graph of a bar

AI-generated content may be incorrect.

Source: FactSet, 22V Research

Source: FactSet, 22V Research

For macro trades, generally, focus on the industries with the highest PCA. Banks have a high PCA and the macro backdrop supports banks.
A graph of a group of volatility

AI-generated content may be incorrect.

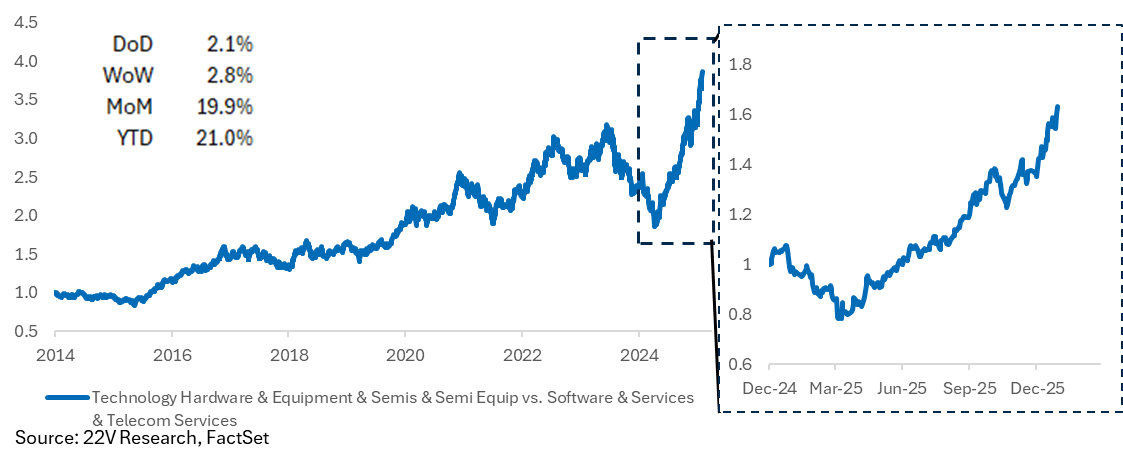
Hardware and Semis are crushing Software and Telecom services YTD.
A graph showing the growth of a stock market

AI-generated content may be incorrect.

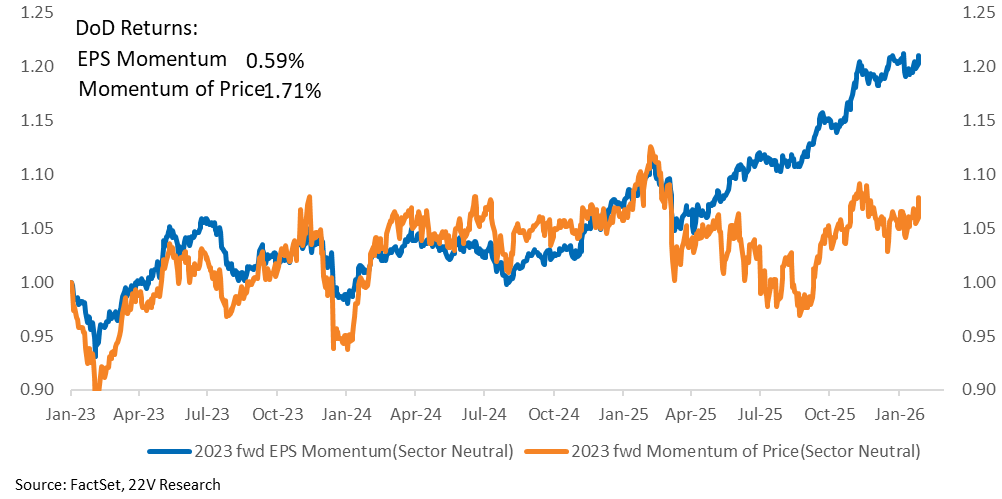
We like EPS Momentum vs Price Momentum longer term
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.