Back Economic Research

November Employment Report Has Something for Everyone

Published on December 16, 2025

∙ Download the PDF Report

By

Peter Williams

November Employment Report Has Something for Everyone

  • Slack continued to increase slightly in November but the internals of the data make strong conclusions a challenge, heightened by the noisiness of the household survey this month. Hiring has looked better in the fall. More and more data seems to suggest that the tariff-drag on the labor market and economy is starting to fade, but whether that is enough to stabilize the labor market as expected remains to be seen.
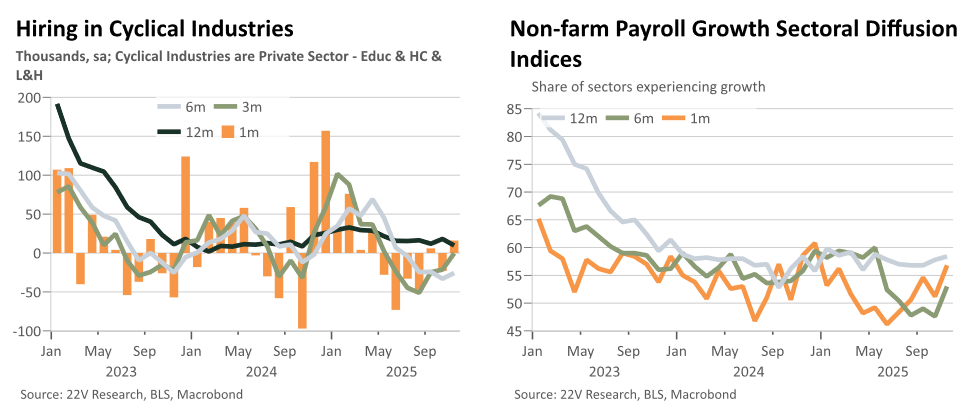
  • Private sector hiring seems to be stabilizing after its spring and summer deceleration. Private sector payrolls added 52k in October and 69k in November, with hiring breadth looking a bit better as well in recent months. ADP’s weekly data, while we are a bit skeptical of the level, suggests that momentum has bounced back some after the shutdown. This at least seems consistent with my view that tariffs remain a key and underappreciated drag.
  • Overall wages were soft (0.1%) but production workers hours were notably stronger (0.347%). Aggregate weekly take home pay growth has rebounded since the spring and summer too (5-6% depending on lookback).
  • The report seems fairly consistent with our read of the signals from ADP and jobless claims.
  • The household survey bounce saw the unemployment rate move higher again, partly due to higher labor force participation. The unemployment rate is now likely just a bit above what the Fed would have penciled in. Worth noting the shutdown’s hit to the household survey’s data quality though.

The internals of the household survey were a quite mixed bag despite the move higher in the topline unemployment rate. The urate moved higher but much of the move has been a result of labor supply gains this year with labor force new and re-entrants accounting for a large share of the unemployed. Somewhat inconsistent with the urate move, the average and median durations of unemployment have been falling after peaking in summer ’25 and fall ’24 respectively. Our overall measure of labor market slack was only slightly up on the month.
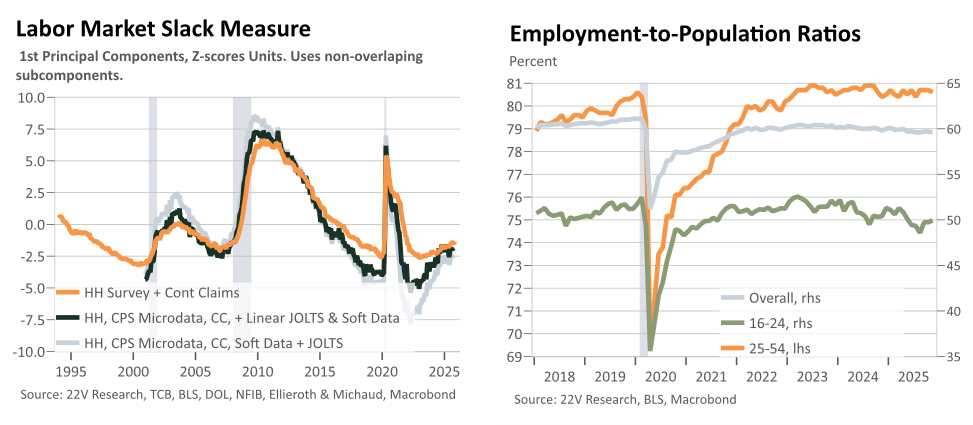
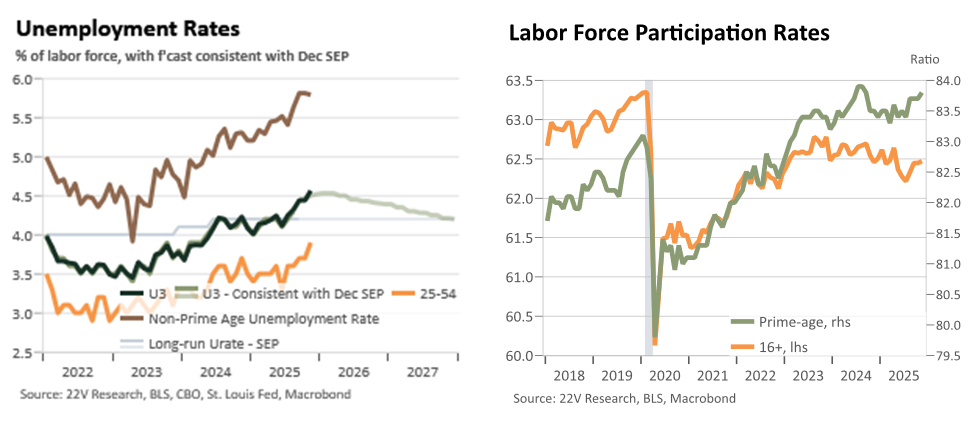
When looking across the internals of the household story, particularly taking into account the NFP data and what we can surmise about aggregate labor supply growth, a tentative conclusion came to mind today. Somewhat surprisingly given still softening wage growth and low levels of job churn, the labor market seems to be seeing some positive hysteresis effects with (ex immigration effects) labor supply looking better. Examples of this include: the rebound in hires from those not-in-the-labor-force (through Sept only so far), overall and prime-age participation rates which troughed in the summer and spring, and the declining durations of unemployment despite low jobless claims. That this has taken place even with hiring flows so sluggish and slack gradually easing, in contrast to usual cyclical dynamics, is strange but it is a strange moment in the economy.
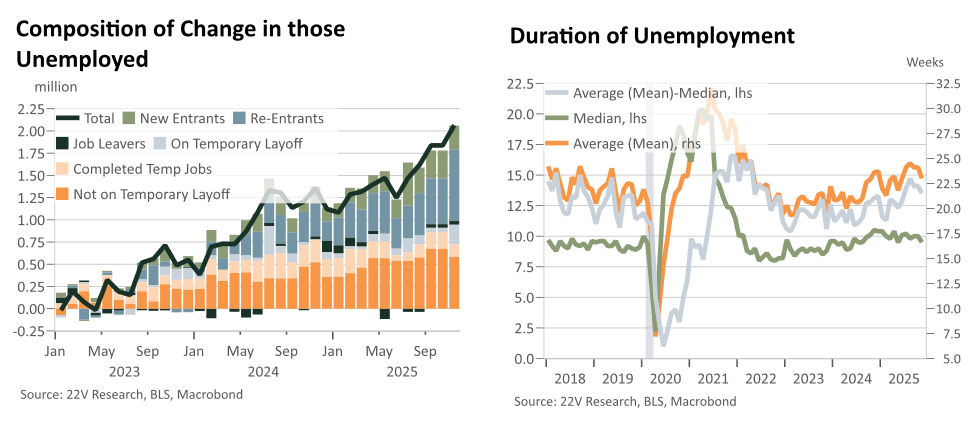
It is also important to flag that due to shutdown-related surveying complications, that the household survey is appreciably noisier than normal this month and that will carry through Q1 data to a lesser extent as well before it stops being an issue. The BLS noted this in their writeup of the release itself. This also has a directional impact on the data as respondents tend to be slightly less likely in to be employed in their initial months of response to the HH survey (see more here); as a result the data was likely biased somewhat more pessimistically this month than usual as the BLS had to include 2x more initial survey respondents to make up for the absence of any new ones in October.

The DOGE resignations were the source of acyclical drag to the Nov topline NFP numbers coming in slightly larger than expected with a 162k hit to federal employment. Many of these workers would have begun job search previously given the long runway which came with the deferred resignation program so the actual direct in terms of number of unemployed would be somewhat smaller but there was likely still at least some direct DOGE impact on the household survey, in addition to the NFP drag.

The employer survey paints a fairly optimistic picture with hiring seemingly having started to stabilize since the spring and summer’s move down. This is consistent with our read of the jobless claims data as having been showing a decreasing pace of softening in recent months, especially cont. claims pace of increase being just barely larger than employment growth, and the underlying signal from ADP’s data, including the evidence for a fade of the shutdown-era drag in today’s weekly data.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.