Back Derivatives Strategy

SPY Put Spread Hedges for May Still Look Attractive and Why I am Doubling Down on a New Bond (TLT) Repair Trade for June

Published on April 20, 2025

∙ Download the PDF Report

By

Jeff Jacobson

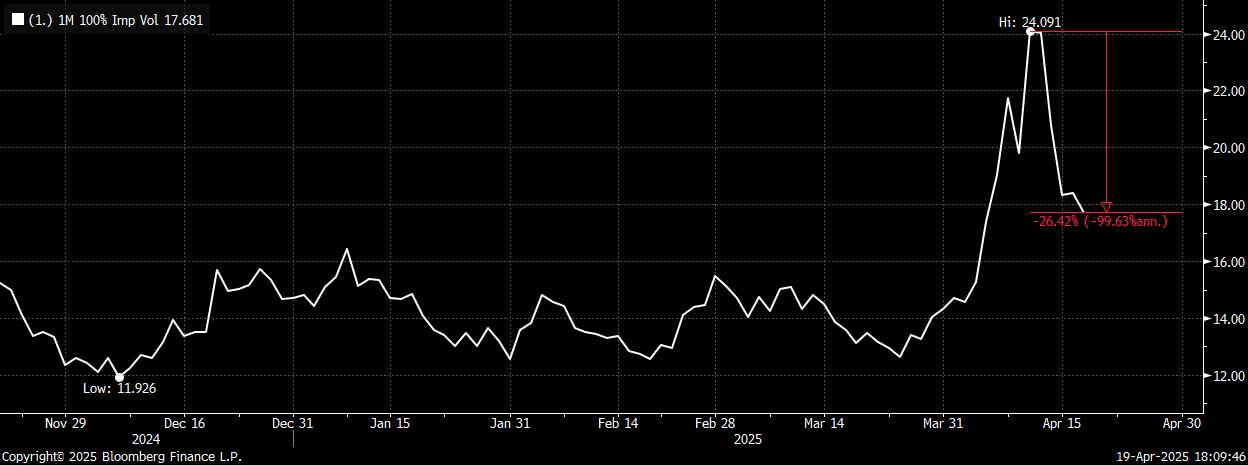
With both stocks and bonds finally having relatively “muted” moves last week, we saw large declines in volatility for both. VIX saw a decline of more than 20% (from ~ 37.5 to 29.5) while TLT 1-month implied vol declined by ~ 25% (from 24 to 18). It was exactly this type of action I was expecting in both stock and bond volatility that made me suggest short vol strategies last week (here).

VIX dropped from ~ 37.5 to below 30 as equity markets closed the week down small after initially opening higher

Bond (TLT) 1-month implied volatility also had a large decline as bonds managed to post a small gain after their huge selloff the week before
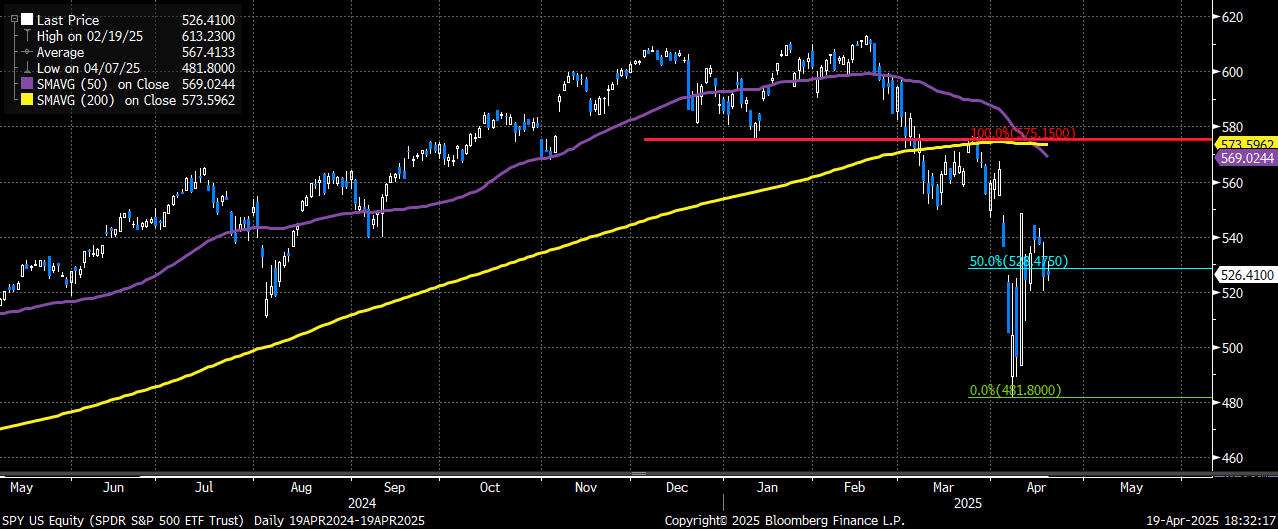
Looking at stocks (SPY) now, I still think downside risks still outweigh upside gains in the short to medium term (especially given how poorly the Mag7 names continue to trade). However, with the index now right in the middle of the “new” 480-570 range, and upside call vol having come in very sharply, I now favor owning put spreads once again over put spread collars like I suggested last week (when SPY was ~ 3-4% higher and upside call vol was still closer to 30 vs a current 22). The fact is, SPY remains ~ 10% above the recent lows, 1-month 40-delta implied vol is now a more “reasonable” 26 (while 30-day realized vol is ~ 45) and put skew is still elevated. Especially as we head into the heart of earnings season, with the Mag7 continue to underperform the overall tape, I still believe owning May hedges at this time makes a lot of sense. Here is a limited-risk hedge trade I would consider owning now:

Trade:
Buy SPY May 510 put (32d, 28.9 IV)
Sell SPY May 470 put (11d, 35.9 IV)
Costs ~ $6.10 (SPY 526.41 Thus close ref)

  • Buying the 40-point wide 1-month protective put spread that starts ~ 3% below spot
  • Hedge structure has a 5.5x to 1 max payoff at May expiry and is capped to the downside below the recent lows
  • Trade captures 7 points of vol skew
  • While I continue to believe mkt upside is capped at the 570 area for now, I don’t like the risk/reward as much of selling upside calls given move lower in index and in upside call volatility/premium
  • May hedge will capture earnings from all of the Mag7 names (besides NVDA)

SPY closed last week at EXACLTY the 50% retracement from the late March and the early April lows. Wouldn’t be a huge surprise to see a re-test of the lows
Bond (TLT) repair trades still look very attractive

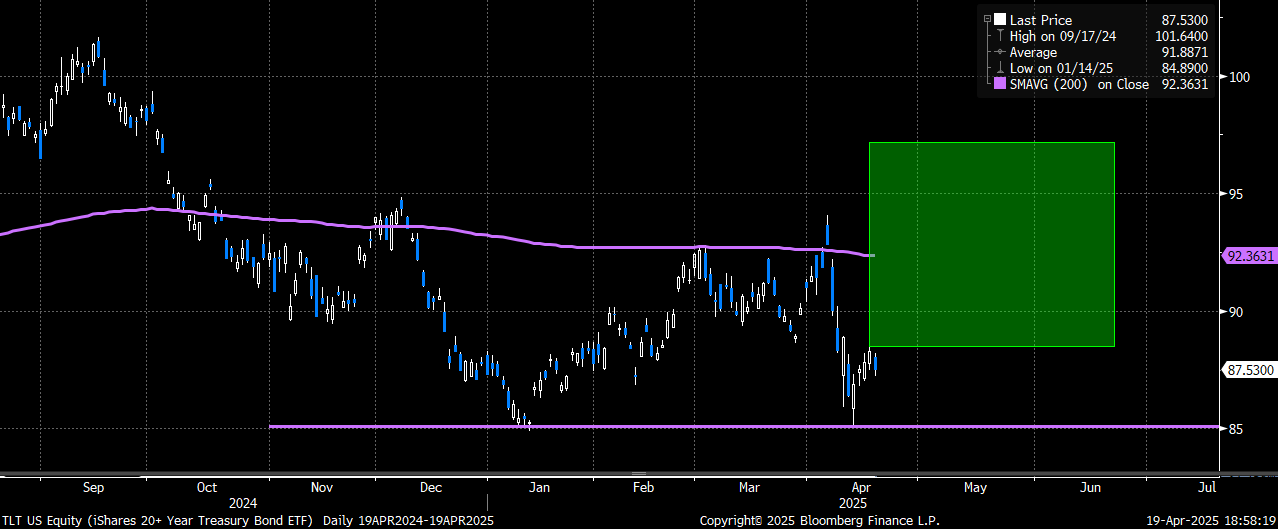
Last week I suggested buying the TLT June 88/94 1×2 call spread as an overlay “repair” trade for bonds following their sharp decline. With bonds up small, and implied vol down sharply, the trade has performed very well thus far. Perhaps the most interesting aspect of the trade is all of the gains have come from the short calls portion (even though TLT was up last week). So even with vol in June down from ~ 22 to 18, I still think this trade should continue to work well as an overlay trade to an existing long bond/duration position. However, with vol now lower, and the initial trade now decidedly more expensive, I would now suggest a “tighter” 1×2 June overlay trade that is also slightly long notional and costs ~ same as the original trade I suggested last week.

Trade:
Buy TLT June 88 calls 1x
Sell TLT June 93 calls 2x
Costs ~ $0.85 (TLT 87.53 price ref as of Thurs close)

  • Buying the at the money June 1×2 call spread as a repair/overlay trade following sharp decline in bonds
  • Trade will outperform between 88.85 and 97.15 by June expiry (+1.5% to +11%)
  • Trade is slightly long delta notional to start as well as theta positive
  • Essentially the same trade I suggested last week, but tightening the spread by $1 to keep cost same
  • Still think TLT vol should continue to come down as long as long-end yields stay below 5%

TLT June 1×2 call spread overlay trades continue to look very attractive as a way to play for a move back higher in the range it has traded between since October
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.