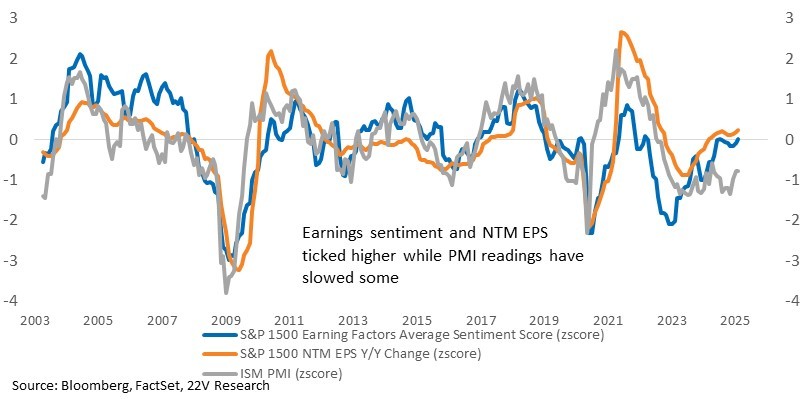
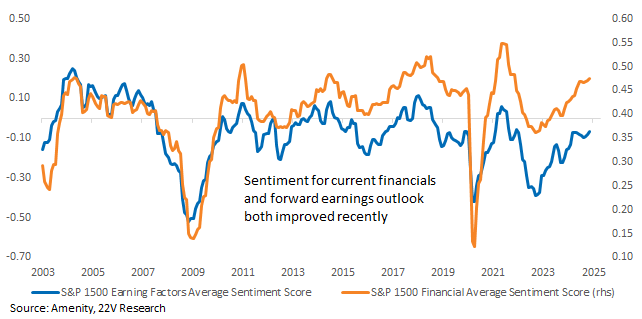
As expected, given the growth impulse in late-’24, reported 4Q earnings continue to be strong. S&P 1500 rolling sentiment readings for current financial conditions and forward earnings outlooks both improved. There is a positive correlation between sentiment and NTM EPS readings, and with broad measures of the macro backdrop (such as PMIs). These indicators are pointing to a strong earnings season as more companies reporting.
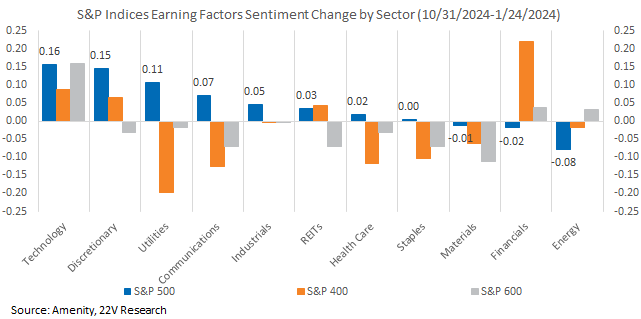
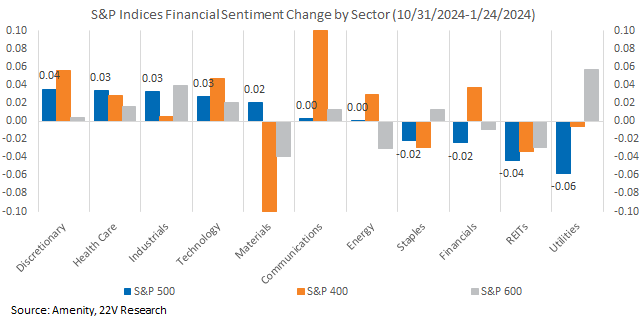
At the sector level, Technology has seen the most fundamental sentiment improvement across all market caps, especially for large cap Tech names. That is consistent with their still strong profitability trends. Materials sentiment has weakened, reflecting their poor earnings, which have been a drag on the sector.
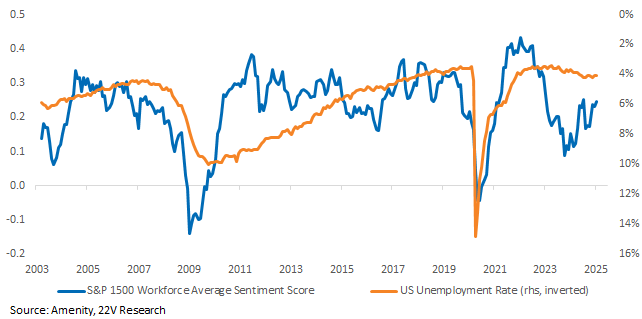
Employment trends continue to exert large influence over market internals (HERE). Management sentiment readings toward “workforce” has improved since 3Q earnings. As a leading indicator correlated with unemployment, improved workforce sentiment reduces, at the margin, the risk of employment deteriorating organically from here.
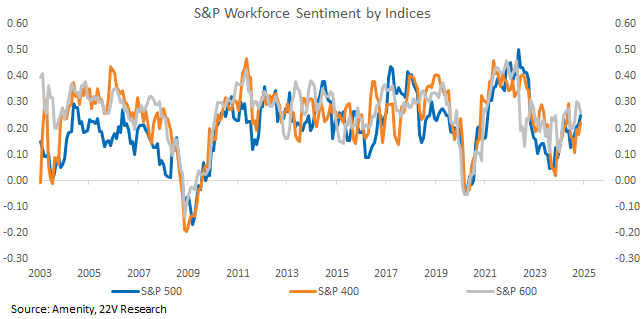
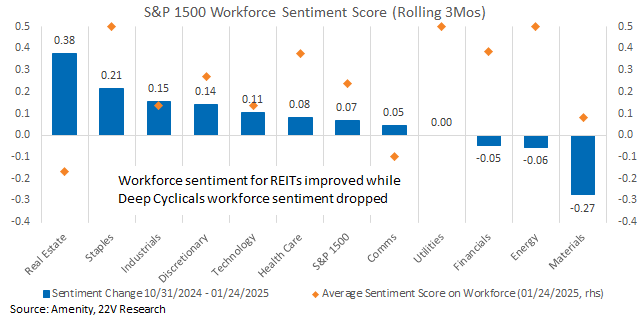
Small caps have seen a deterioration in workforce sentiment, consistent with their weaker earnings over the past year. We expect some reversal of small cap fundamentals this year as earnings expectation have improved and employment sentiment is likely to rebound some as well. Materials names have the worst workforce sentiment, following their weak earnings.
This week 104 S&P 500 names are expected to report, including mega caps like META, MSFT, TSLA, and AAPL. At the end of this report, we list the names releasing next week that have high Earnings Quality and positive earnings sentiment. These names tend to beat estimates more than the index. The counterpart of names with higher risk of missing estimates are also listed in the report.
Sentiment Suggests Improved Earnings and Employment: 4Q earnings remain strong as revisions improved and beat rates remained high. S&P 1500 index level rolling management sentiment toward current financial conditions and forward earnings outlook both climbed. That is consistent with the improvement in NTM EPS and PMI readings. Macro conditions and sentiment trends point to another strong earnings season.
At the sector level, large cap Early Cyclicals have seen the greatest improvement in forward looking earnings sentiment, led by Technology. Tech is the only sector seeing improved earnings sentiment across all market cap segments over the past 3 months. The flip side oof that trend is Materials, where sentiment has been weak broadly.
Financial sentiment, which reflects current fundamental conditions, have improved further to start 4Q reporting. Most of the improvement comes from Cyclicals along with Health Care, while Defensives remain weak, especially within large and mid-cap universes. That helps explain their underperformance over the past quarter as well.
Recent internal rotations and sensitivities to unemployment data suggest employment readings are a major macro influence over the market today (HERE). After a short period of volatility last year, workforce sentiment has rebounded and improved since 3Q reporting. Workforce sentiment continues to rise, suggesting a reduced risk of a deterioration in employment. We expect the improvement to continue as growth remains strong.
Looking by market cap, large and midcaps have seen improved employment sentiment, while managers of small caps have grown more pessimistic toward hiring relative to a few months ago. Weak earnings of small caps in 2H24 is consistent with the ongoing deterioration of workforce sentiment among small companies. Some earnings improvement within small caps should be expected and help alleviate weak employment sentiment.
At the sector level, looking within the broad index, workforce sentiment improved for most sectors, especially REITs and Staples. Materials workforce sentiment dropped the most. Energy and Financials have also seen falling workforce sentiment, but that deterioration is from a VERY high absolute level.
With ~1/5 of S&P names reporting this week, including some megas (META, MSFT, and TSLA on Wed. and AAPL on Thu.), below we list the names that have higher beat potential, which are the names of high Earnings Quality and positive earnings sentiment.
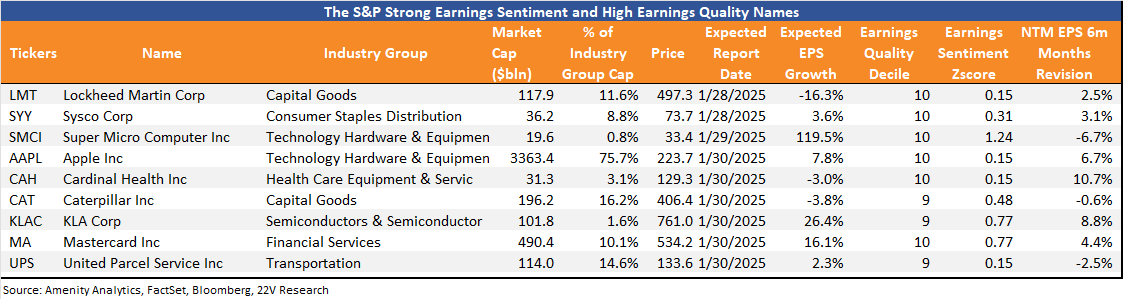
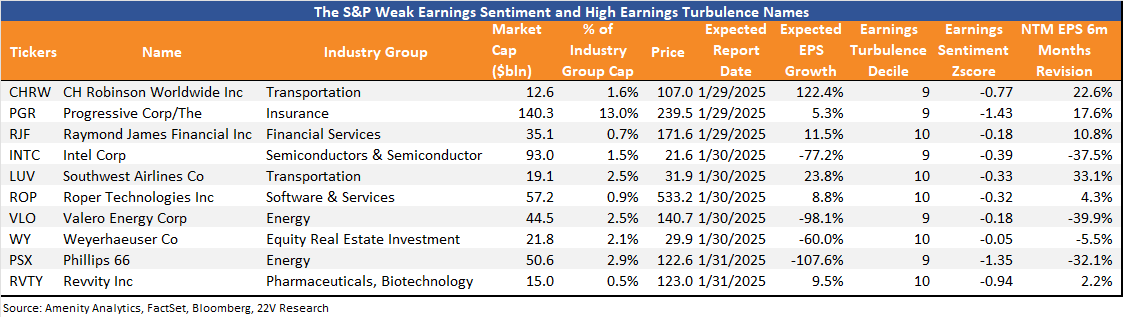
The counterpart are names with higher EPS miss risk, which are listed below. These names have high Earnings Turbulence and negative management sentiment coming out of 3Q reporting.