Back Quantitative

Quant Market in Numbers: Internal Rotation on Unemployment & Inflation Moves

Published on January 22, 2025

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Sophia Wang

Kevin Brocks

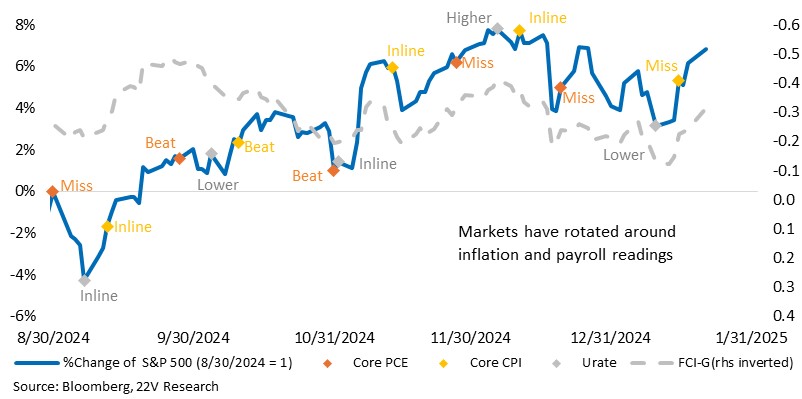
The S&P has rebounded 4.6% from its post-payroll low, and smaller caps are up even more (the equally weighted S&P is +5.1%). Risk assets tailwinds improved further after weaker than feared inflation readings increased the chance of a goldilocks scenario of strong growth and contained inflation.

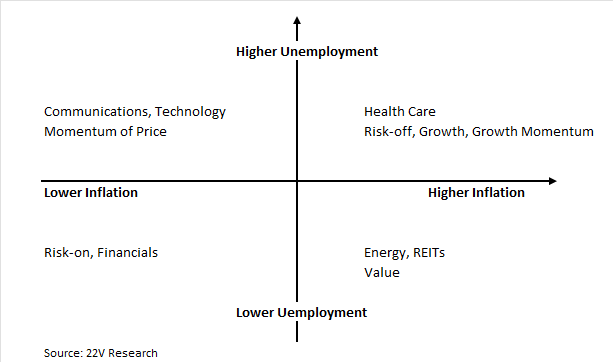
Lower unemployment readings favor more Risk-on and Value-driven internals. That has been the case for most of the past few years, though that relationship is at risk IF stronger employment readings become associated with firmer inflation expectations. So far, inflation expectations have been largely unresponsive to minor changes in payrolls. A binary impact matrix from unemployment and inflation readings tendencies based on factor and sector sensitivities is outlined below. This is meant as a quick cheat sheet.

A diagram of a company's workflow

Description automatically generated

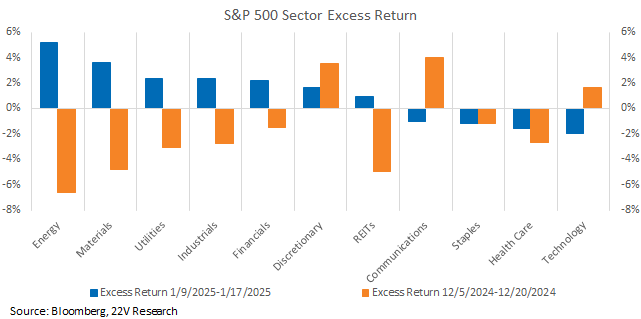
Combining sensitivities to unemployment and inflation, a lower unemployment rate together with stable inflation favors Energy, REITs, and Financials while Communications, Tech and Health Care underperform. Higher unemployment and in line inflation led those sector performances to reverse.

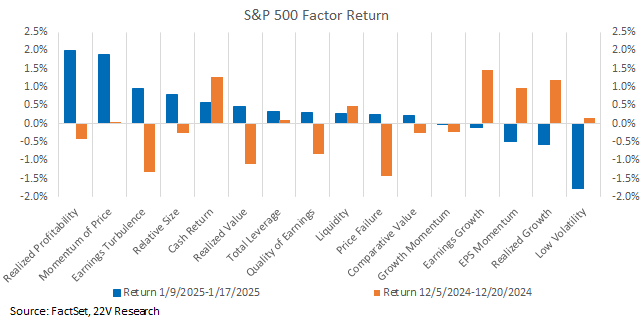
Rotations within factors have been less dramatic than within sectors this month. Market internals did rotate, favoring Risk-on and Value factors at the expense of Growth leadership. A continued goldilocks backdrop should favor a further Value and Risk-on rotation. Inflation and tariff risks will add volatility to those trends though.

Internal Rotation on Unemployment & Inflation Moves: The S&P has rebounded 4.6% from its post-payroll low, and smaller caps are up even more (the equally weighted S&P is +5.1%). Risk assets tailwinds improved further after weaker than feared inflation readings increased the chance of a goldilocks scenario of strong growth and contained inflation. Inflation and payroll readings will remain important factor influencing headline markets and internal rotations until uncertainty related to tariffs and the Fed’s reaction function eases.
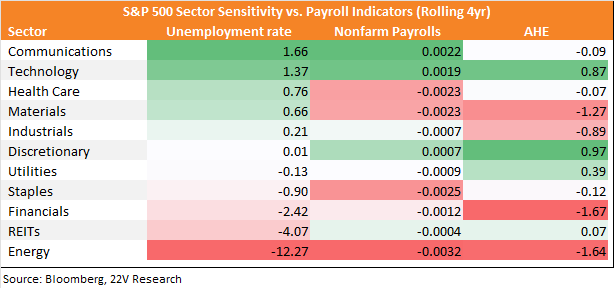
Sectors that benefit most from weaker employment are Early Cyclicals, especially Communications and Technology, which are more Growth exposed sectors. Energy, REITs, and Financials are more likely to benefit from stronger employment and general growth trends.
A table with numbers and text

Description automatically generated

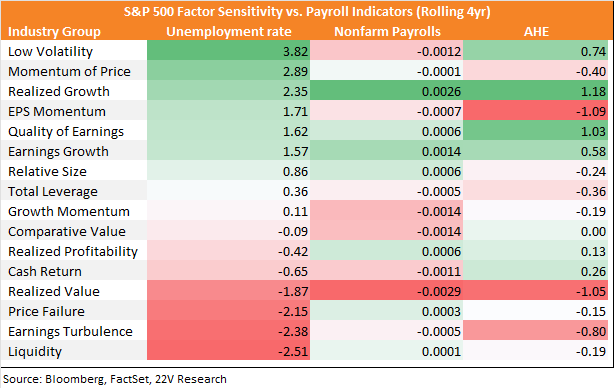
At the factor level, Low Volatility, Momentum, and Growth have the strongest sensitivity to weaker employment data. Lower unemployment readings favor more Risk-on and Value-driven internals. That has been the case for most of the past few years, though that relationship is at risk IF stronger employment readings become associated with firmer inflation expectations. So far, inflation expectations have been largely unresponsive to minor changes in payrolls.
A table of numbers with text

Description automatically generated with medium confidence

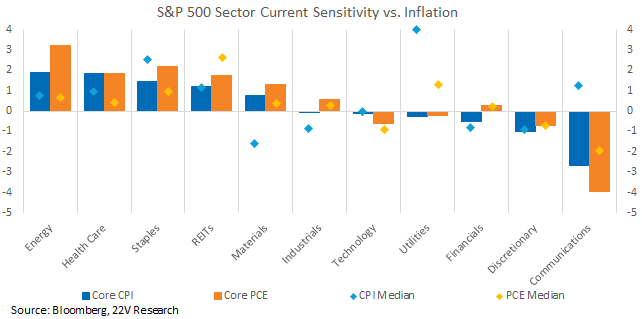
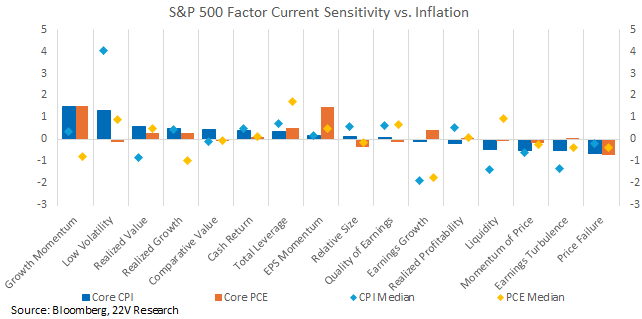
Sensitivities to inflation readings are largely reversed. Deep Cyclicals and Defensives benefit from higher inflation, while Early Cyclicals, especially Communications and Discretionary, do better when inflation trends lower. In most periods over the past few years, high inflation has led to concerns that financial conditions need to tighten. That has left higher inflation associated with more Defensive/risk-averse market internals. We see little reason to expect that relationship to change near-term.
A graph of different colored squares and a line

Description automatically generated

That has led to a more mixed factor sensitivity to inflation. Risk factors have lower betas with inflation readings, and their sensitivities to core CPI and PCE readings have diverged. Fundamental factors, including Growth Momentum, Value, and Growth, have more consistent positive sensitivities to inflation, reflecting long-term support from an expansionary macro backdrop.
A graph of different colored squares and numbers

Description automatically generated

Combining sensitivities to unemployment and inflation, a lower unemployment rate together with stable inflation favors Energy, REITs, and Financials while Communications, Tech and Health Care underperform. Higher unemployment and in-line inflation led those sector performances to reverse.
A graph of a graph with text

Description automatically generated with medium confidence

Rotations within factors have been less dramatic this month. Market internals did rotate, favoring Risk-on and Value factors at the expense of Growth leadership. A continued goldilocks backdrop should favor a further Value and Risk-on rotation. Inflation and tariff risks will add volatility to those trends though.
A graph of a number of numbers

Description automatically generated with medium confidence

A binary impact matrix from unemployment and inflation readings tendencies based on factor and sector sensitivities are listed below.
A diagram of a company's workflow

Description automatically generated

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.