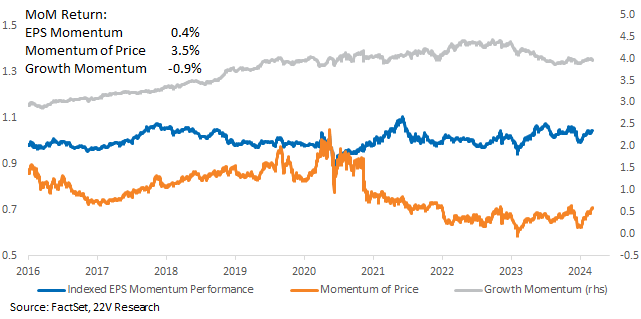
Momentum factors surged this year, up +11.7% YTD for large caps, +12.7% for mid, and +9.5% for small. Mo has gained across most sectors as well, led by Industrials, Tech, and Communications. The outperformance of Price Mo continued over the past month, but fundamental based Momentum returns have been turned lackluster. That could be an early sign of potential Mo weakness.
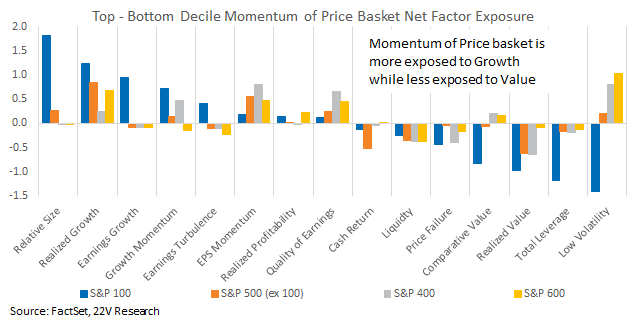
Currently Price Mo is tied to Growth and Quality exposures, while negatively exposed to Value and risk-on factors. That suggests the gain from Momentum factors earlier this year reflects investors’ concern about the macro backdrop and Fed policy. Recent macro readings, including today’s Payroll and AHE report, should help alleviate those concerns, and will likely then be a headwind to high Mo names.

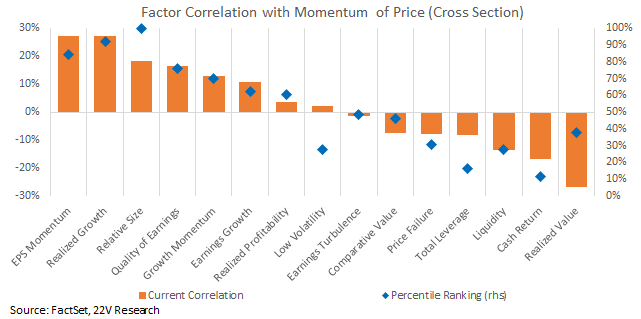
Another risk is that the rank correlation between Price Mo and Relative Size is unusually high right now, suggesting a small cap rebound would also be a headwind to Momentum of Price.
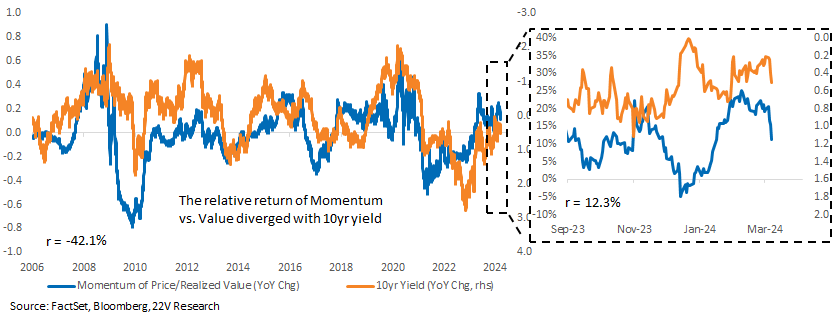
Yield sensitivity has become particularly important in the current macro backdrop (HERE). Mo vs Value returns had diverged from their historical correlations with the 10yr yield but have recently started to converge again. That may lead to a reversal between Momentum and Value as Value catches up to the 10yr yield rising.
POTENTIAL MOMENTUM REVERSAL: Momentum has been the best performing S&P factor this year. Price Momentum in particular. Price Mo has gained +11.7% YTD. Mo has worked across market caps: +11.7% YTD for large caps, +12.7% for mid, and +9.5% for small. Other fundamental based Momentum factors also gained this year across indices but have faded in the last month. That could be a sign of weakness ahead.
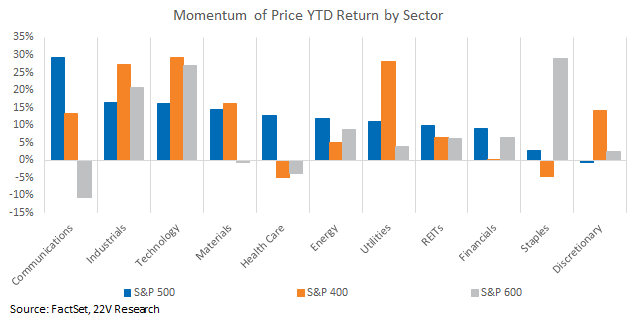
Momentum of Price outperformance was not mostly driven by Tech names. Mo has worked across sectors. Discretionary is the only sector within the S&P it hasn’t worked.
Momentum is positively exposed to Growth and Quality, while negatively exposed to Value and risk-on factors. In other words, the outperformance of Momentum reflects investors’ concerns over the current macro backdrop and uncertainty about Fed policy. Recent macro readings indicate slower, but not too slow, economic growth. That should help alleviate macro uncertainty, which would be a headwind to Momentum.
Rank correlation has similar results to factor exposures. Mo is most correlated to Growth, Size and Quality, at the expense of Value. The current percentile of Size correlation has been around its historical high, suggesting small cap reversal is also likely to be a headwind to Momentum of Price.
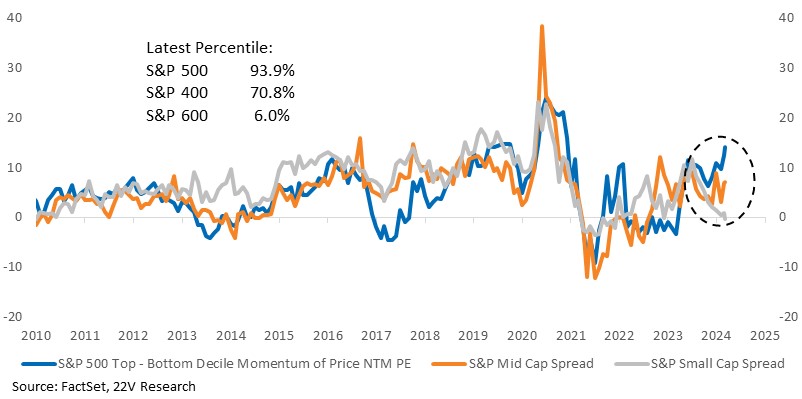
Interestingly, the NTM PE spread between high and low Price Momentum names has also diverged within market caps. High Mo PEs are stretched relative to low for large caps, but low Mo have stretched PEs relative to high for small caps.
Yield sensitivity has become particularly important in the current macro backdrop (HERE). Mo vs Value returns had diverged from their historical correlation with the 10yr yield but have recently started to converge again. That may lead to a reversal between Momentum and Value as Value catches up to the 10yr yield rising.