A big disconnect has opened up between yields/yield curves (moving higher) and factors returns. Historically, rising Value and Risk-on factors have the highest betas to changes in yields. Risk-off tends to lag as yields backup.
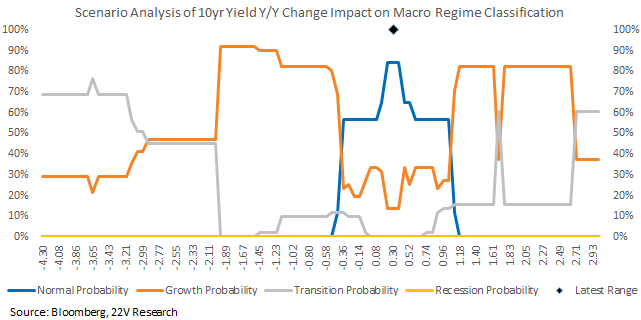
Yields continue to be an unusually strong contributor to market and factor vol. While the outlook for near-term policy rates remains a hot topic, the influence of yield fluctuations will remain high (HERE). Changes in yields can alter the macro regime, but with economic growth strong, 10yr yield and the inverted yield curve are biased higher.

Momentum betas to yields have been trending higher, helping explain the factor’s surge this year. Value factors on the other hand have 1) strong betas to 10yr yields, 2) significant Value underperformance relative to macro fundamentals, and 3) has been among the worst performer YTD. Strong growth readings and a curve that is biased higher (some rate cuts + stable to higher 10yr yields) make positioning for a Value rebound increasingly interesting.
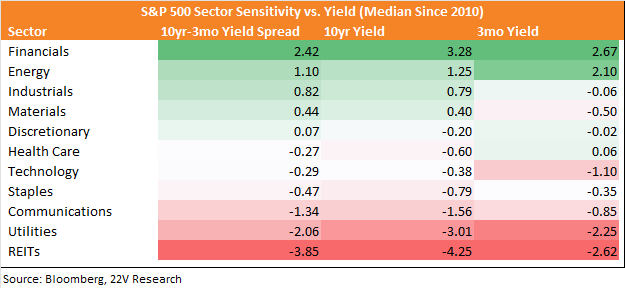
Sectors that most benefit from rising yields and the yield curve are Financials and Energy while REITs and Utilities have the most negative yield betas. We discussed in Strategy report (HERE) about potential Energy catchup on oil prices improvement. As a sector with higher beta to yield changes, expected rising yield and yield curve re-steepening should also bring some tailwind to the sector.
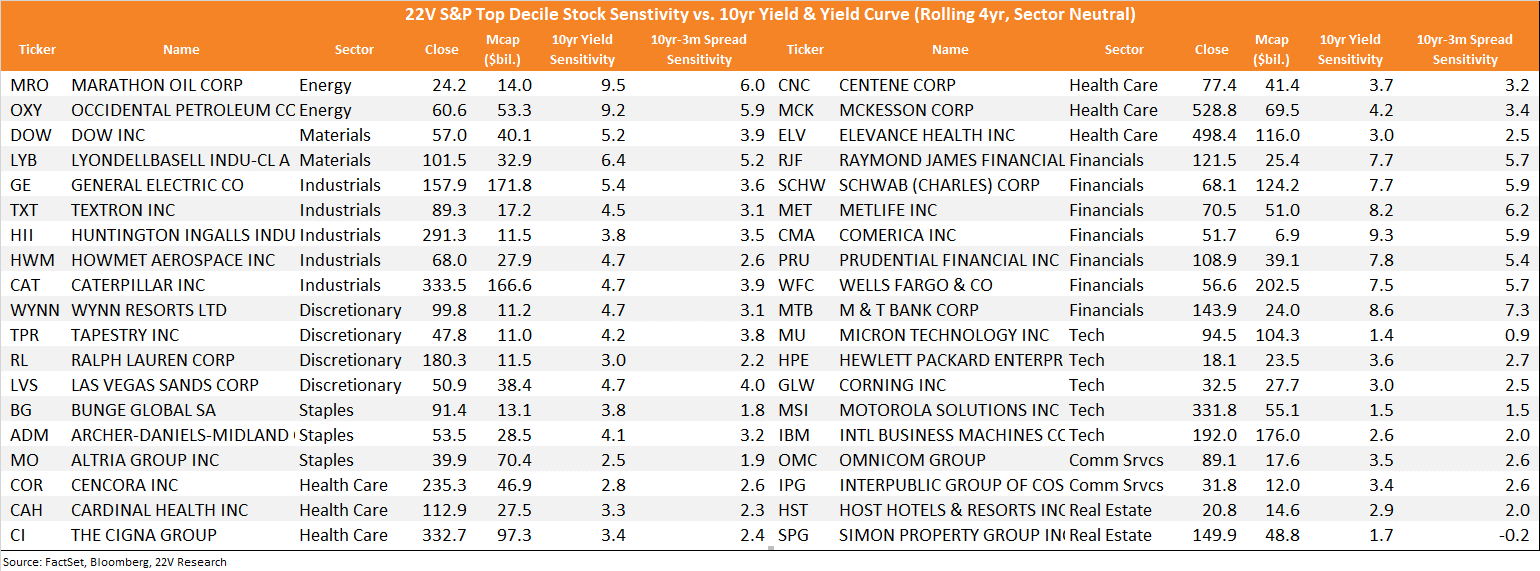
At the end of this report we list a sector neutral group of stocks with the highest betas to yields and the yield curve.
Yield Trends Suggest a Value and Risk-on Catchup Trade: Yields continue to be an unusually strong contributor to market and factor vol. While the outlook for near-term policy rates remains a hot topic, the influence of yield fluctuations will remain high (HERE). Changes in yields can alter the macro regime, but with economic growth strong, 10yr yield and the inverted yield curve are biased higher.
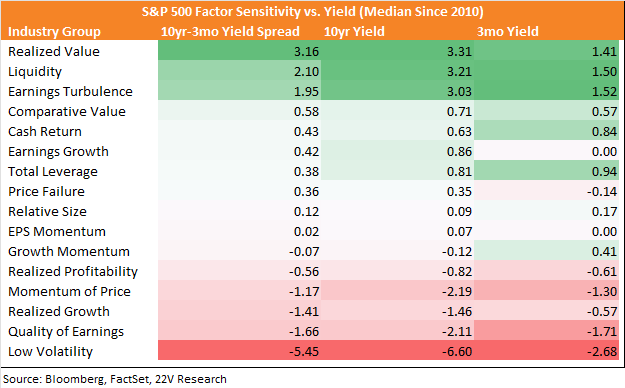
Historical factor betas to changes in the 10yr, 3mo and yield curve tend to be directionally similar, but longer-dated yields and the curve have a greater influence. Value and risk-on factors, including Liquidity and Earnings Turbulence are most positively sensitive to yields. In other words, they tend to benefit in a rising yield backdrop, which more than half of investors surveyed are expecting near term (HERE). Low Volatility tends to face the greatest headwind from rising yields.
Shorter-term (past 4 years), Value remains to be the most yield sensitive factor across all yields, and Size and Momentum betas have increased. That is aligned with the outperformance of mega 7 Tech names which are highly exposed to Size and Momentum. Momentum of Price has been the best performing factor this year, far exceeding all other factors, and the improved sensitivity with yield also supported to some extent. The biggest laggards relative to the backup in yields and steepening of the curve have been 1) Value and 2) Risk-On factors.
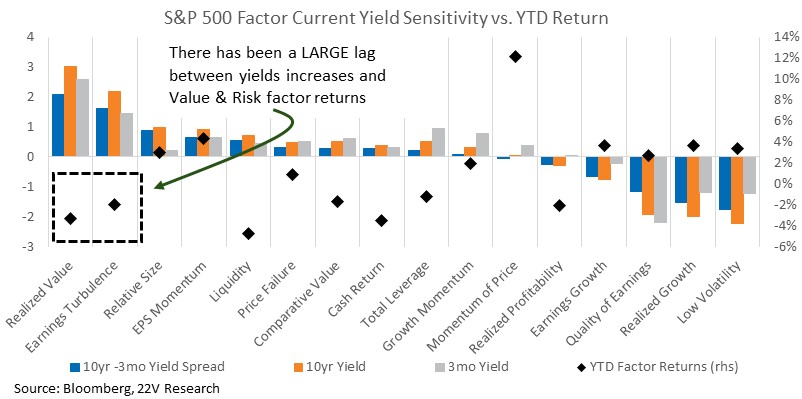
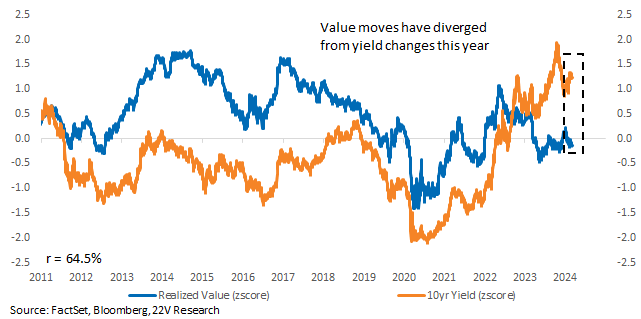
The return divergence between Value and yield this year continues to widen out. And Value has lagged the improvement in macro forces in general (PMI for instance, HERE). Economic growth trends remain strong, much stronger than investors expected, and that should be a tailwind for Value factors especially after they have lagged the macros so far this year.
Sector Focus: Sectors that benefit most from rising yield and yield curve are Financials and Energy while REITs and Utilities have seen the most negative beta with yields considering their median beta post-GFC. That is consistent with factors as Financials and Energy are usually more Value exposed.
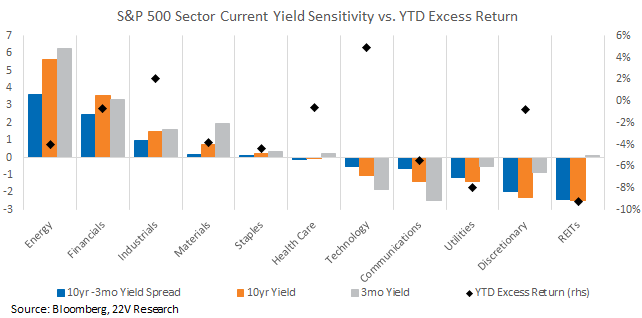
Yield sensitivity today at sector level is roughly aligned with historical pattern with the exception from Staples and Discretionary. Staples is having slightly positive beta to yields while Discretionary beta is unusually negative today. As we discussed in Strategy report (HERE), Deep Cyclicals, especially Energy and Materials are having relative weak fundamentals but the oil rebound and lagging returns of Energy leaves room a catchup trade. The yield beta to the sector and expected move also help that catchup.
Stock List: Below we list the stocks with the greatest sensitivity to 10yr yields and the yield curve. This is a group of names that should track changes in yields over the course of the year.