Back Portfolio Strategy

Higher for Longer Rates Leaves S&P Fair Value Range Bound, While Better Earnings Mean Correlations are Still Biased Lower

Published on April 19, 2023

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

SUMMARY: Citizens Financial missed on deposits this morning. While bank earnings so far have not indicated trouble with deposits or a significant pullback in lending, most of the institutions that have reported were large and well diversified. There are lots of regionals left to report and still a lot of uncertainty around their numbers. We don’t have an edge on loan growth, but there will be winners and losers, which will create more dispersion and opportunity for stock picking.

Yesterday, we talked about how economic data and declining systemic risk from banks bias US rates higher (HERE), and Gerard had a report out explaining how the neutral rate (the policy rate that is neither stimulative nor restrictive) has likely risen (HERE). Eurozone core inflation was flat at a high-level m/m and ECB chief economist Lane, formerly a dove, is calling for a period of below-trend growth to combat inflation. Global rates will probably be higher for longer, barring a collapse of economic data. Per the latest BofA survey, investors are record long bonds relative to stocks. The pain trade is bond yields and stocks moving higher.

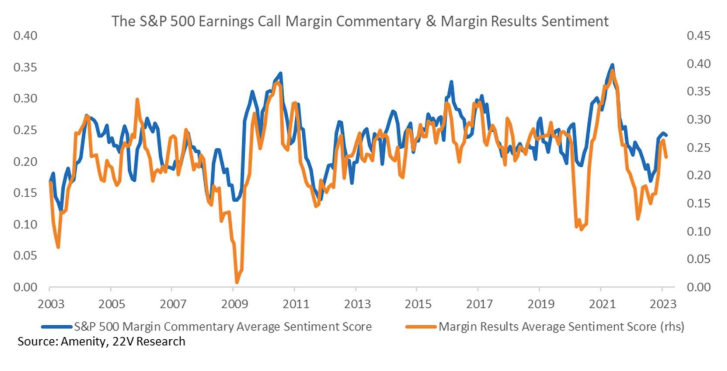
Higher rates are a headwind to S&P fair value estimates, but that is offset by better earnings. Strong nominal growth is typically accompanied by strong earnings, as long as margins are stable. Margins are set to come down, but management sentiment, measured with the Amenity natural language processing tool, does not suggest a collapse. Again, we don’t think a deep recession is a given this year. We put +6mo recession odds at about 50/50.

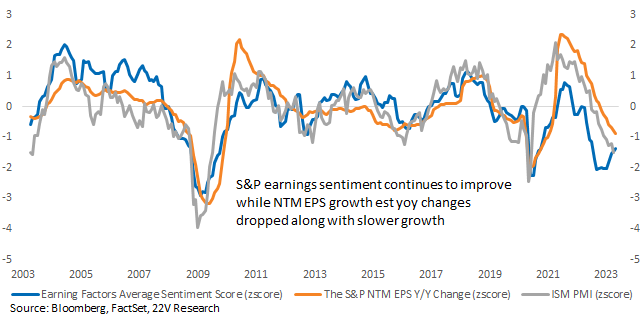
And investors still expect poor earnings growth this year, with a median estimate of $207. However, management sentiment towards earnings has hooked up. There have been sentiment head fakes in the past, but generally sentiment firms ahead of a bottom in revisions. Continued improvement in management sentiment towards earnings would suggest earnings will beat investor expectations (though bbg consensus numbers still look too high).

Chart

Description automatically generated

We estimate 2023 earnings at $214, which puts fair value right around current levels, and at about 130 points higher than fair value with EPS at $207.

Fair value is still range-bound at approximately 3,800-4,200. There should be more dispersion in internals than gains at the index level. Intra-portfolio correlations are falling rapidly and should continue to do so during earnings season. Stock picking remains a better path to outperformance than market timing.

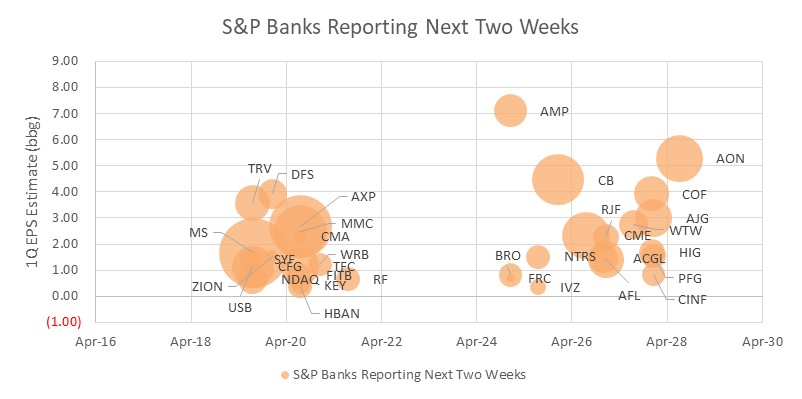
MARKET VIEWS: Citizens financial missed on deposits this morning ($172B vs $181B est). Over the next two weeks, another $1.2tril of banks and other financials will report earnings, including many regionals. Data so far hasn’t indicated trouble with deposits or a big pullback in lending, but most of the institutions that have reported were large and well diversified. A lot of uncertainty about the impact of bank failures/slowing growth remains. We don’t have an edge on the state of lending; our higher conviction take is we’ll end up with winners and losers, creating more dispersion and opportunity for stock picking.
Chart, scatter chart, bubble chart

Description automatically generated
Source: Bloomberg, 22V Research

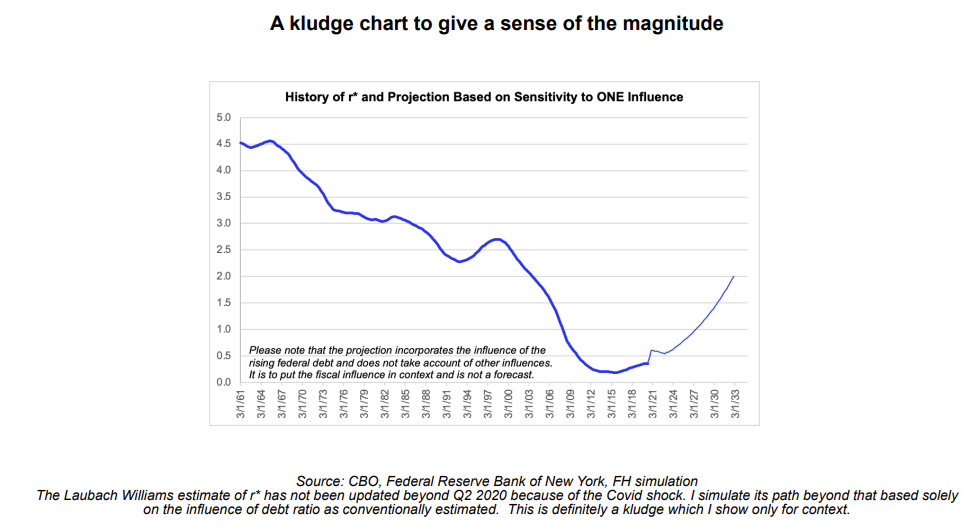
Yields are higher globally this morning. UK core inflation was higher than expected. Eurozone core inflation was flat at a high level m/m. ECB chief economist Lane, formerly a dove, is calling for a period of below trend growth to combat inflation. Yesterday, we talked about how economic data and declining systemic risk from banks biases US rates higher (HERE), and Gerard had a report out explaining how the neutral rate (the policy rate that is neither stimulative nor restrictive) has risen (HERE). That means rates will probably be higher for longer, barring a collapse of economic data. Per the latest BofA survey, investors are record long bonds relative to stocks. That requires deep recession risk to be elevated short-term. The pain trade is bond yields and stocks higher.
Chart, line chart

Description automatically generated

Higher rates reduce S&P fair value estimates, but that is offset by better earnings. Strong nominal growth is typically accompanied by strong earnings, as long as margins are stable. Like we covered in a quick 1Q earnings webinar yesterday (replay HERE), margins are set to come down but management sentiment, measured with the Amenity natural language processing tool, does not suggest margins will collapse. Again, we don’t think a deep recession is a given this year. We’ve got recession odds at ~50/50.
Chart, line chart

Description automatically generated

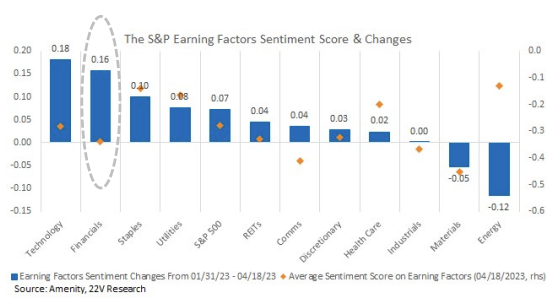
Investors expect poor earnings growth this year (median estimate at $207, HERE). Meanwhile, management sentiment towards earnings has hooked up. There have been sentiment head fakes in the past (sentiment improves but estimates remain in a downtrend), but generally sentiment firms AHEAD of a bottom in revisions (more details HERE).
Chart

Description automatically generated

While still negative, the improvement in earnings sentiment is broad across sectors. Tech, Financials (yes, Financials), Staples, and Utilities have had the largest improvement (more HERE). Deep Cyclicals have fared the worst. Continued improvement in management sentiment towards earnings would suggest that investors’ poor expectations are unlikely to materialize.
Chart, waterfall chart

Description automatically generated

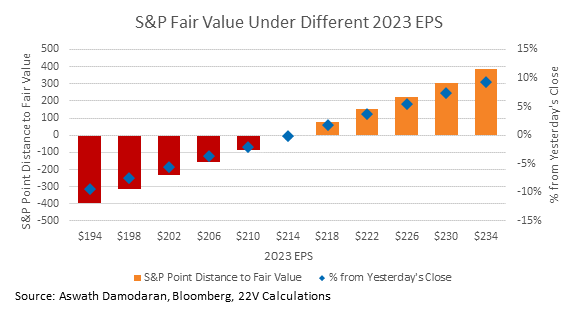
We estimate 2023 earnings at $214, which puts fair value right around current levels, ~130 points higher than fair value with eps at $207.
Chart, waterfall chart

Description automatically generated

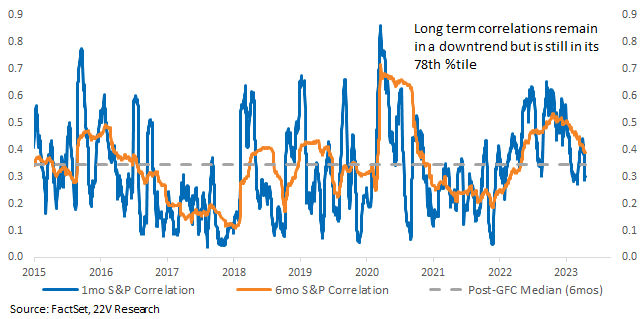
The offsets of rates and earnings imply fair value is still rangebound from ~3800-4200. Going forward, there should be more dispersion in internals than movements at the index level. Intra-portfolio correlations are falling rapidly and should continue to do so during earnings season.
Chart

Description automatically generated

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.