Back Washington Policy

Speaker McCarthy and President Biden Are Near the Same Page on Debt Limit

Published on April 18, 2023

∙ Download the PDF Report

By

Kim Wallace

Sandra Namoos

SUMMARY

The President and the Speaker of the House agree cuts to Social Security and Medicare shouldn’t be part of a FY24 agreement. Both men also insist the US won’t default, although semantics might obscure that point. The Speaker yesterday invoked Reagan’s aura if not mantra in assuring no new taxes should be expected from fiscal discussions this year. Senator McConnell’s return to the Capitol after recovering from his fall is another reassuring fiscal policy development, as he too is on record against default. Public commitments of all four congressional leaders and the President mitigate concerns that process or narrow political preferences are roadblocks to FY24 negotiations failing to accommodate US debt payments.

OUTLOOK

The result is an improbable default or stimulus, and unambitious fiscal policy this year – despite an expected very loud process. This is a clear near-term positive that is nonetheless an intermediate-term disappointment that only feeds fiscal imbalances largely driven by demography. House Majority Leader Scalise yesterday said Republicans would release a blueprint today as an alternative to Biden’s March FY24 budget which serves as Democrats’ opening ante. That hasn’t happened as of 45 minutes before the market close; we’ll update our fiscal outlook once a plan is introduced.

McCarthy’s NYSE comments yesterday were also notable for his multiple assurances of no pre-conditions, despite specific ideas such as a return to discretionary spending caps. ‘Nothing is done until everything is done’ is a well-worn, if grammatically lacking, DC trope. It’s too early to know the timing and content of a deal. As we wrote in our fiscal note last week, credibly assessing tangible risk is impossible before the start of spring and summer months of negotiations. The X-date spread is mid-June to mid-August. Timing certainly will be an element of early talks. Some GOP lawmakers want to align the X-date with the October 1 start of FY24. Recent discussions reportedly indicate there might be more support for a late December suspension. Momentum suggests single or multiple 4Q23 X-dates triggered by specified suspension dates rather than debt ceiling dollar adjustment(s).

In our client survey last week less than 8% of respondents thought the US would default this year. Investors and other Americans are more focused on rates, inflation, war, and social issues. As such, they likely have little tolerance for contrived risks precisely because they’re occupied with these real daily challenges. This is one of the stronger factors meaningfully constricting odds of default. The data in the following table highlights the US debt problem, especially in a rising rates environment. It also shows the relative puniness of discretionary spending which includes most Pentagon and many domestic programs popular among voters. CBO interactive infographics offers cool visuals of major spending and tax categories. For reference, the 2022 US deficit is more than 5.5% of GDP.

The last serious fiscal rebalancing proposal of which we are aware was an 11-year fiscal rebalancing plan formulated and shopped in early 2011 to Capitol Hill leaders. The legislative core was a bundle of slow but steady restraints on entitlement spending and a gentle slope upwards of revenue from policy tweaks and anticipated growth.

That plan was designed to slow demography’s persistent fiscal balance pressure. Two important ‘money committee’ chairs of the then-newly elected House Republican embraced the plan, but an important one did not because it contained tax increases. Meetings with Senate money committee Democrats weren’t scheduled because an important House Democrat promised a very caustic fight if the plan was publicly released. Naming individuals isn’t important to the punchline as it wouldn’t change the outcome: the legislative proposal never moved beyond the draft phase.

The following chart shows the last five months of FY23 revenues slowing compared to the recovery year of FY22.
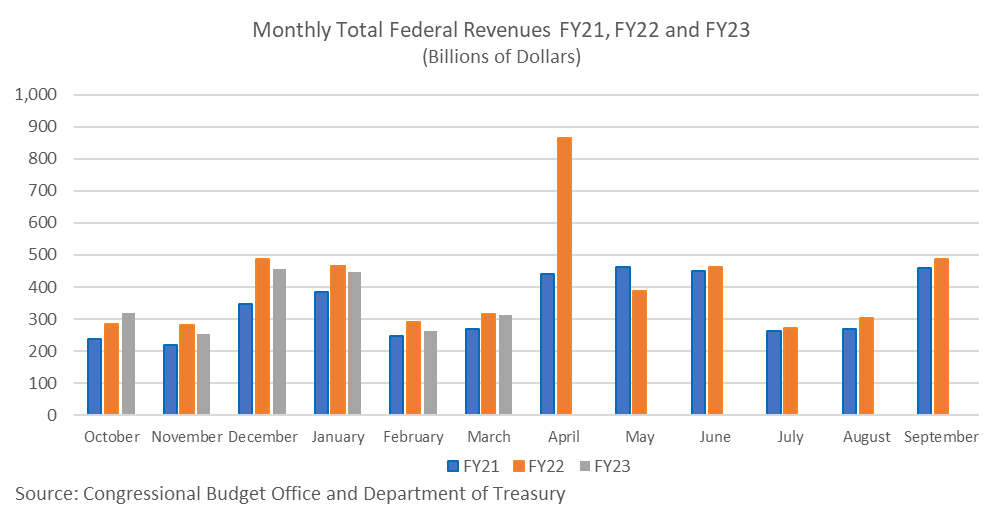
Revenues measured against a backward-looking 30- or 50-year average miss the point about demography as our national costs haven’t ever been through this causal buildup of debt. Discretionary spending need not escape restructuring contribution, but the next fiscal rebalancing will necessarily recognize that mandatory spending on entitlements and net interest payments are the target. Adopting tough choices will benefit growth, generate more revenues, and enhance US international standing as the reserve currency country. But, as we’ve consistently stated, fiscal rebalancing is unlikely before the 2024 elections because of these tough choices.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.