Back Portfolio Strategy

The Selloff in AI Stocks and 10yr Yields is Tied to the Importance of AI ARR Reaching $400-600bn Exiting 2027

Published on October 9, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Kevin Brocks

Sophia Wang

DAILY STRATEGY: Earlier this week, we shared investor sentiment from a dinner we hosted (HERE). Yesterday, we hosted a larger investor breakfast, and the message from both events was similar: investors are constructive on the AI buildout, but their confidence rests on AI lab revenues (Anthropic, OpenAI and the others) reaching the roughly $400bn-600bn ARR range exiting 2027. And getting SOLID information on AI Lab ARR trends is critical. Anthropic IPO should be helpful in this regard.

Some Background on Why This is So Important – At $400-600bn ARR, 2029/2030 AI related capex plans are likely to come to fruition. Currently, the stocks most levered to AI related capex are getting very little credit for 2029 and beyond AI capex according to 22V Data & Infrastructure analyst Dauvin Peterson. Hence the significant compression in PEs for many AI related buildout baskets. We have recommended being long a basket of Dauvin’s “coiled springs” AI buildout names based on the idea that the $400-600bn ARR will be achieved (see my conversation with Dauvin HERE). These names have witnessed PE compression at the same time EPS expectations have increased meaningfully. See more HERE.


All the above helps explain the severe sell-off in AI related stocks AND 10yr yields yesterday. It was reported that OpenAI 2026 ARR was tracking $50B ARR vs $70B previously signaled according to the FT. Two reactions fell from that headline, AI buildout baskets and Semis sold off as any downside in revenue from one of the labs puts the $400bn-600bn in ARR required to support AI capex at risk. Additionally, downside risk to capex expectations longer term = downside risk to longer term GDP growth and inflation expectations. All things equal.

Capex expectations need to hold up (chart below courtesy of Dauvin Peterson) for AI buildout baskets to move higher. Our call is capex expectations will hold through 2027. Also, it turns out, at least according to Bloomberg, the $50bn ARR from OpenAI may not be correct. From the Bloomberg article. “OpenAI is expecting to reach or exceed $70 billion in annualized revenue by the end of the year, driven largely by growth in its enterprise business… The company’s annualized revenue was roughly $50 billion at the end of September, which represents a projection of OpenAI’s yearly sales based on a shorter period.”
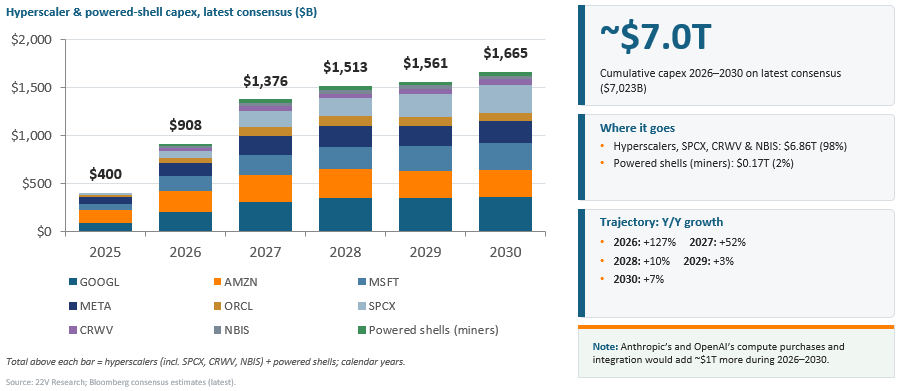
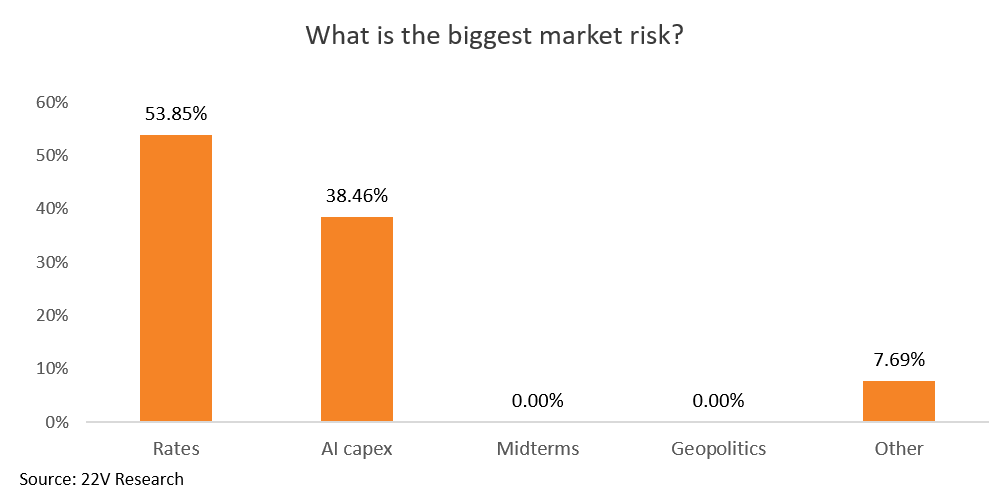
The noise level on the AI Lab ARR is likely to be at an 11 until we get some details from Anthropic with the IPO.

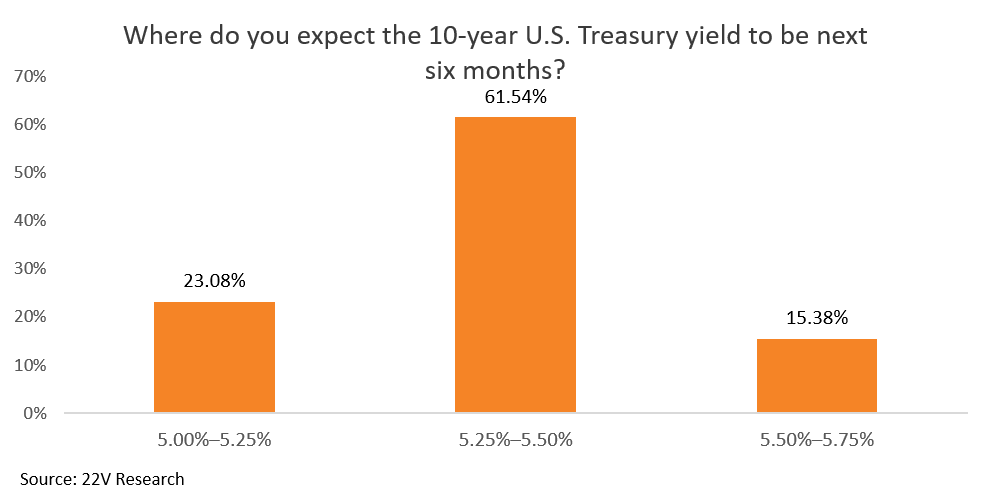
More Survey Results – Dinner attendees saw economic growth as sustainably strong despite 10yr yields being near 5.3%, and the breakfast survey is consistent with that: 62% see the 10yr at 5.25-5.50% over the next six months and another 15% at 5.50-5.75%. Only 23% expect yields below 5.25%. The S&P 500 view was more divided than usual: 46% expected the S&P to be up 5-10% and another 8% expected more than 10%, but 38% expected it down.

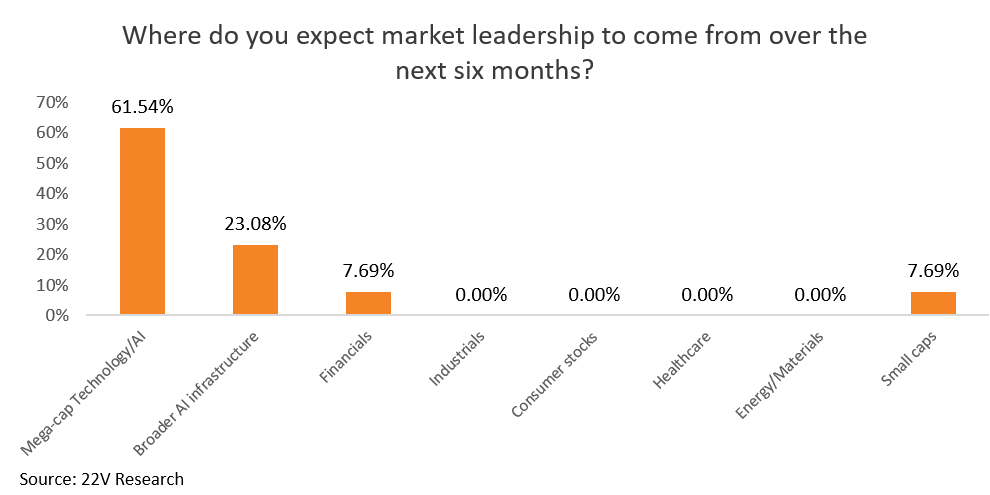
On AI, 62% see mega-cap tech/AI leading and 23% pick broader AI infrastructure, while industrials, consumer, healthcare and energy/materials drew zero. As discussed in the conversation with Dauvin, (HERE) no one expects compute oversupply in 2027, and 54% say later than 2030. That is more bullish than equities imply, since multiples across the group are compressing as if compute turns long by 2029. It also fits the dinner’s central point that the trade needs $400-600bn of ARR by end-2027 and a path to roughly $1tn in 2028-29 to earn a 15% ROIC on the $1.4tn 2028 capex year. Missing that ARR marker is the 2029 capex “cliff” risk that investors worry is may be holding down multiples.

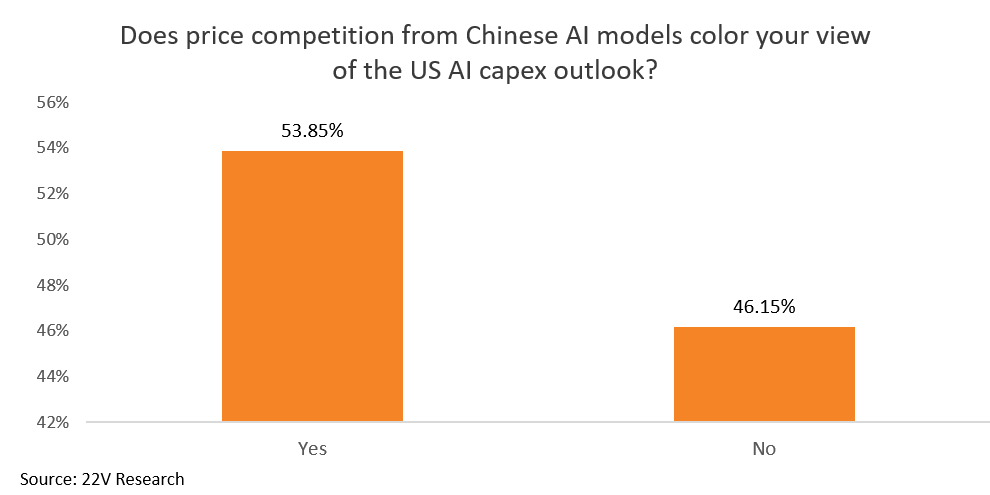
Risks – 54% said price competition from Chinese AI models colors their view of the US capex outlook, which feeds the worry that token prices fall faster than volume grows. If revenue falls short, financing $1-2tn of capex at sub-15% returns will get much harder with yields rising. Dauvin has moderate confidence in the revenue targets today, mostly because disclosure is limited, and expects that to improve once Anthropic’s S-1 shows realized pricing. Until then, the trade works as long as ARR tracks toward the marker and yields stay contained.

Charts…

~54% of investors expect the S&P 500 to move higher over the next 6 months. ~38% expect the S&P 500 to move lower. This is unusual dispersion from our surveys.
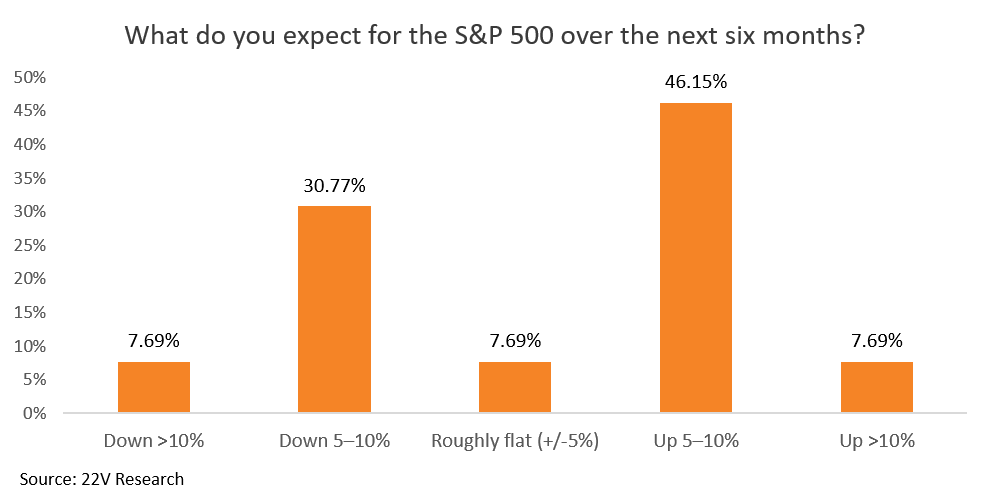
Investors expect the 10y to be in the 5.25%-5.5% range in the next 6 months.
Market leadership is skewed towards AI.
Investors do not see compute oversupplied until 2031 and later.
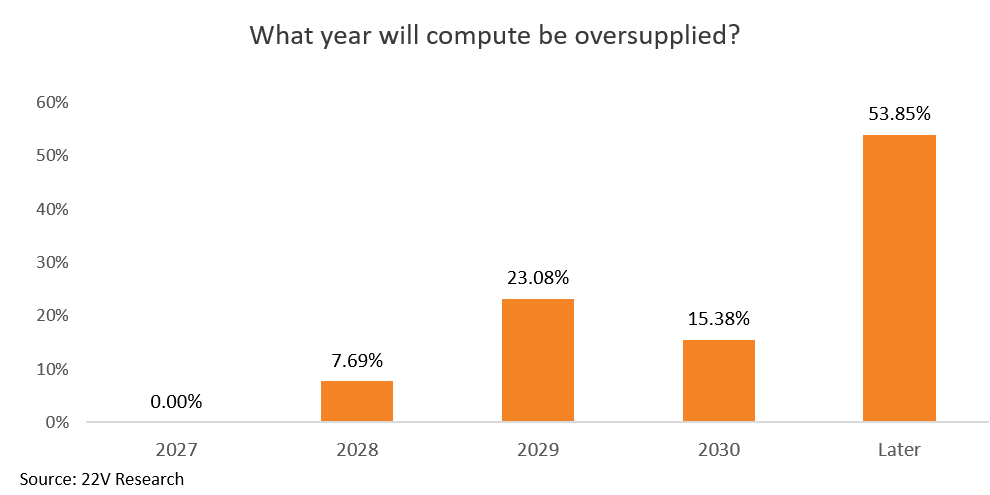
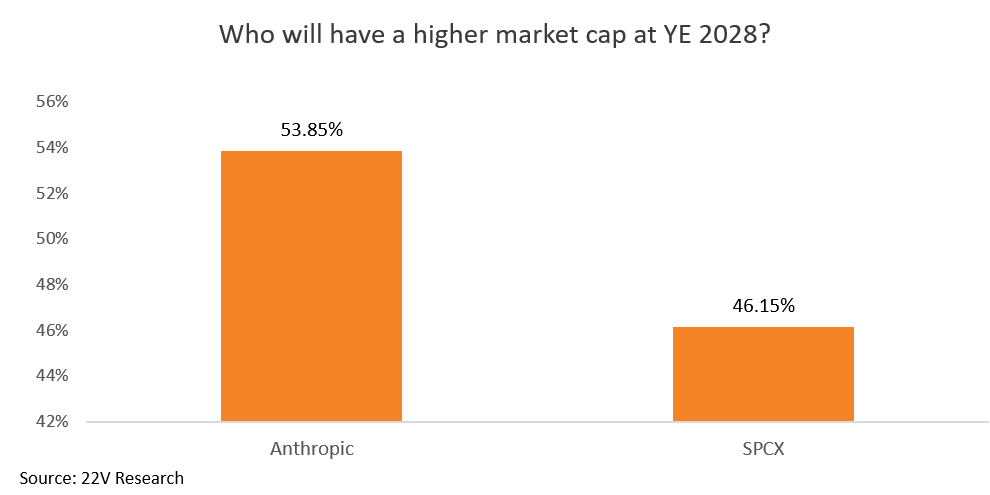
Investors believe Anthropic will have a higher market cap than SpaceX at the end of 2028.
Investors see price competition from Chinese AI models affected their view of the US AI capex outlook.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.