DAILY STRATEGY: We hosted an investor dinner last night in NYC. The focus was on requirements for the AI buildout baskets to continue working. Investors need confidence in that $400bn-600bn ARR by the end of 2027. Commentary from Anthropic, which would give confidence (or not) in $400bn-600bn number being achievable, is critical according to dinner attendees. Let us know if you are interested in joining in the future. The conversation was excellent.
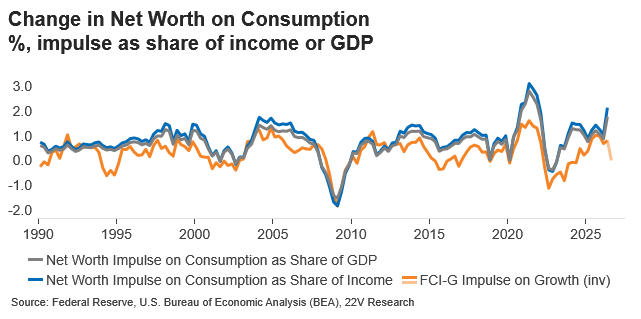
First on the macro portion of the dinner. Just about everyone agrees economic growth is sustainably strong despite 10yr yields at 5.3%. The reason being that the surge in consumer net worth (driven by AI’s influence on asset prices) continues to support above 2% consumer spending and AI Capex continues to accelerate. Our strong economic growth call is consensus. If anything, we are a bit out consensus in calling for growth to slow some over the next 6-8 months. Investors at dinner were more skeptical than we are that the recent tightening of financial conditions would slow growth. Investors had 10yr at 5.1% by year-end and the S&P 500 above 8000.
Investors are more skeptical of the below chart than we are.
Second on AI. And this dominated the conversation: Everyone agrees that about $400–600 billion of frontier-lab and closely related AI product ARR by the end of 2027 is the practical minimum to underwrite current capex plans through 2028/2029. A real return on the 2026–27 build (ROIC at 15% ish), plus room to keep spending in 2028, points to the top of that $600bn range and a path toward roughly $1 trillion annual AI revenue in 2028–29.
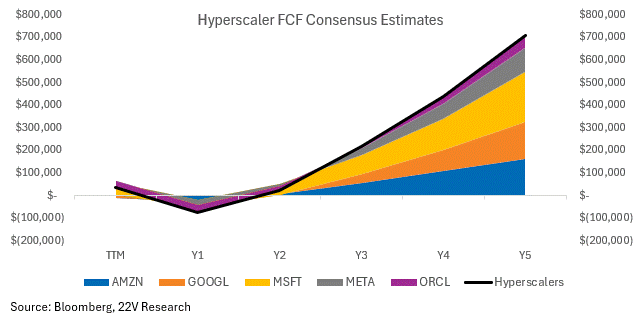
That visibility to something near $1 trillion annualized in 2028–29 is critical. If the $1.4 trillion 2028 capex year is going to earn its cost of capital (apparently GS thinks a 15% ROIC is the minimum) rather than “just get financed”. The more financing that is required, vs some cash flow generated from a 15%+ ROIC from capex + financing, the more skeptical investors were on the ability for the financing to happen. 1-2 trillion in financing on disappointing ROIC investments (below 15%) in a backdrop of increasing interest rates would be an issue. Capex plans would disappoint. FYI… if the below estimates are correct, the AI buildout trade would continue.
Grey Rhino Risk (high-impact threat that is very visible and backed by clear warning signs) was Abbott losing in Texas. Not a base case as he is at 70% odds, but those odds have declined some recently. That was cited as a MAJOR negative catalyst for the AI buildout names.
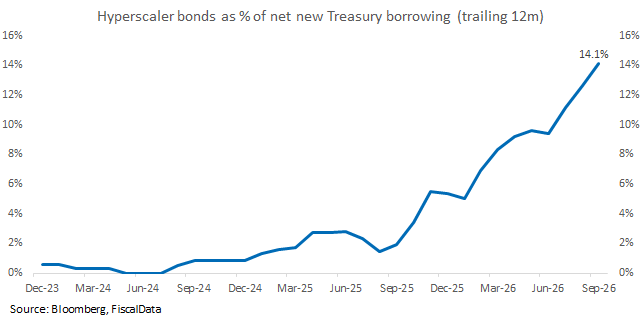
As noted in the Quant Report yesterday (HERE), Compared to new supply, which is what the market must absorb at the margin, hyperscaler bond issuance counts 14% of net new Treasury borrowing over the past year, a scale at which the two are competing for the same pool of capital. This will grow over time and helps explain why investors are worried about upside risk to UST yields.
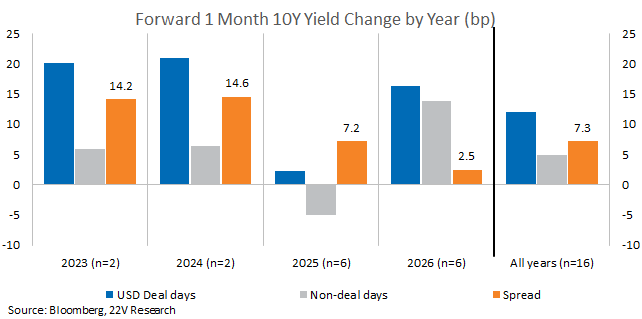
Since 2023 there have been 16 dates on which one or more hyperscalers priced a USD deal that included a 10yr and 30yr tranche. Comparing the yield changes forward 1 month post hyperscaler debt issuance with other 1 month yield changes without debt issuance in the corresponding year, deal days show a larger 10yr yield move across all years, which is partially pushed by higher hyperscalers debt supply.