

Bottom Line: 2H26 Call
Our call for 2H26 is that core inflation will slow some, leaving the Fed to hike MAYBE one time and 10yr yields ~4.5% range. With implied equity risk premiums relatively high and corporate earnings much better than expected, upside to equity markets has increased (8500 on S&P 500 is possible) if our inflation and 10yr call is correct and AI continues to support margins. Cyclicals and fundamental factors (EPS Momentum, Expected Growth, Value, GARP) have increased tailwinds. Non-AI Cyclicals (Retailers, Regional Banks, Transports) are particularly interesting now. We are long Risk-On vs Risk-Off Factors, which is a tradable basket through Morgan Stanley (MS22RISK Index on Bloomberg).
Relevant News: Payrolls
July’s employment report was unusually soft and noisy, with the employer survey weaker than other labor indicators suggest, but the broader picture remains one of gradual stabilization around a very weak labor-supply trend. Labor supply and demand are both soft, job churn remains sluggish, and slack is broadly stable to slowly improving, with immigration shifts further constraining supply in some sectors. With the labor market muddling through rather than clearly strengthening, inflation remains the key marginal input for the Fed: we still expect the next move to be a hike, though temporary post-World Cup distortions and possible post-MOU disinflation argue against rushing the timing. A further decline in unemployment or rebound in payrolls would add a hawkish impulse and lower the inflation threshold needed to justify tightening.
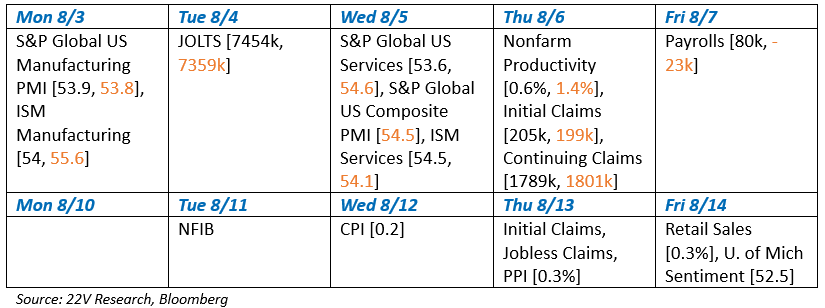
Things to Watch [Consensus, Results]:
Strategy:
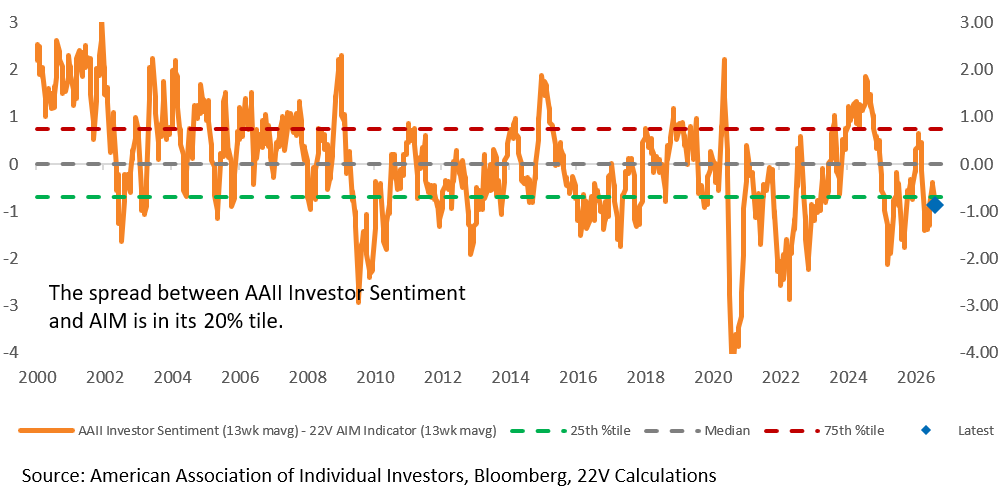
Two Way Urate Risk + Investor Sentiment Still Low RELATIVE to Economic Data– (HERE)
Investor sentiment is still low RELATIVE to the breadth of economic data. We look at investor sentiment, as measured by the AAII bull bear ration, relative to a diffusion index of US economic data. Not investors sentiment in isolation. The current reading of investor sentiment relative to the economic data suggests higher than normal returns. We mention this because we saw a few notes that investor sentiment is overly positive.
Europe:
Details on Any Iran Deal Remains Elusive, But Main Points Coming To Light Indicates a Return to the MoU – (HERE)
A U.S.-Iran negotiated outcome remains the strong base case (80%+), though an Oman-Iran deal on the Strait of Hormuz may take another 1–2 weeks. U.S. weapons shortages and Gulf opposition make renewed large-scale U.S. strikes unlikely, while Iran retains significant leverage over the Strait. The eventual deal will likely resemble an expanded June MoU—reopening the Strait in exchange for sanctions relief and renewed nuclear talks—leaving Iran in a stronger regional position and keeping oil risk premia contained.
Data Infrastructure / Commodities:
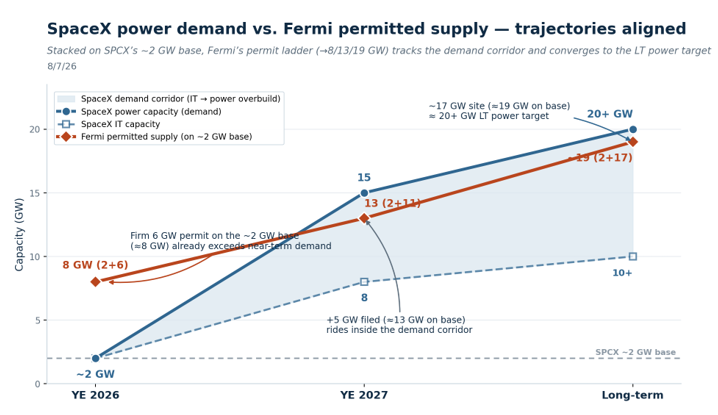
Compute Demand, Power Access: SPCX’s Options to Capitalize– (HERE)
The AI compute market remains increasingly tight, with open-source model proliferation and accelerating adoption supporting higher compute prices and hyperscaler investment. The key bottleneck is increasingly permitted, near-term power, leading us to add Fermi (FRMI) alongside SPCX, CRWV, NBIS, and ORCL as beneficiaries. FRMI’s 6GW of secured air permits, another 5GW in process, and ~1.7GW of generation capacity in various stages of delivery make it a scarce strategic asset as permitting becomes more difficult—potentially attracting SPCX or other AI builders seeking to rapidly scale capacity.
Source: 22V Research; SPCX Q2 Earnings; FRMI Q2 Presentation

