

In recent weeks, we have been vocal about the increasingly tight compute market and the view that the proliferation of open-sourced models will continue to underpin a rising price market for compute. Hyperscalers emphasized this theme on their earnings reports and indicated their willingness to invest now to capture the high rates of returns. A key constraint for a company like SPCX or other neoclouds to capitalize on this is access to power; specifically, permitted, at-scale power.
We have highlighted SPCX, CRWV, NBIS, and ORCL as beneficiaries of a tight compute market, open-source proliferation, and the upward trajectory of AI adoption. This list is concentrated with neo-cloud and data center players; re-examining several turnkey greenfield and powered-shell situations has changed my view on what belongs in this theme. The scarcity value of near-term permitted power warrants adding Fermi (FRMI) to this list as well as explained below.
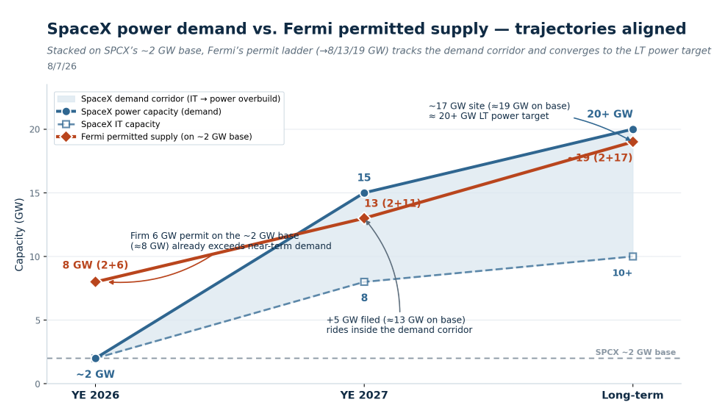
First, SpaceX. During its Q2 conference call they stated a goal to grow IT compute capacity ~4x by year-end 2027 and to have line of sight to over 15GW of power capacity in that same time frame. This translates to adding ~6GW of IT compute capacity and a path to adding ~12 GW of power by YE 2027 from YE 2026. Even for a company full of rocket scientists, as Elon Musk noted, this is a big task, and the permitting path is getting harder, not easier, as we head into the midterms.
The evolving regulatory and midterm charged political environment is only increasing the scarcity premium for permitted power access. Just this week, TX Governor Abbott’s letter directing the PUCT to audit all data-center power applications is the clearest signal of both increased regulatory review and political pressure to have a less cavalier approach to fast tracking permits and power applications. SPCX has been speculated in the press to be planning their next data center build in TX (as well as expanding some smaller sites around Colossus).
The similarities between what SPCX needs and what FRMI has today are notable. Below is a comparison based on public transcripts and presentations without regard for what appears to be significant internal management and board debate and activity around the strategic direction of the company. It also seems, per public press and filings, that there may be some type of process underway either for finding a large offtake agreement and other options around the asset.
Fermi’s air permits (6 GW secured + 5 GW in process) are the closest match to SPCX’s stated trajectory of adding ~12GW to its portfolio by year-end 2027. Below is a trajectory of SPCX’s power and capacity goals next to FRMI’s active and applied-for permits, as well as long-term site power goals. We would note that the initial air permit is sizable (6GW) and that the more recent one was applied for in March of 2026 and it appears the timeline continues to increase for receiving larger permits.
Source: 22V Research; SPCX Q2 Earnings; FRMI Q2 Presentation
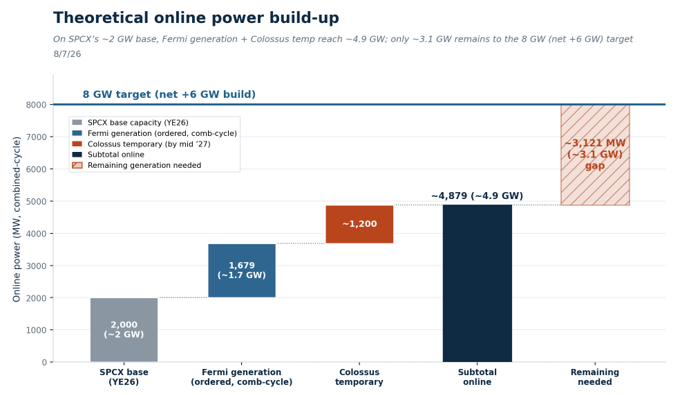
The following chart shows the power-generation equipment status for Fermi. Fermi has ~1.7 GW of generation capacity in various stages of delivery over the coming months. Combined with the ~1.2 GW that SPCX could transition off Colossus through mid-2027, that is ~2.9 GW towards the 6GW of active power needed by YE 2027 (on top of SPCX’s existing ~2 GW base), leaving roughly ~3 GW still to source. We would estimate that SPCX could find additional capacity, as many capital-equipment players have been adding capacity and new products (jet-engine-derived turbines) come onto the market.
Source: 22V; FRMI Q2 Presentation; SPCX Q2 Earnings
FRMI’s turnkey situation could be one of potentially other cases where “the shoe fits” and given SPCX’s desire to capitalize on a hot AI compute market in Texas it would not be surprising that Fermi could draw their attention. Additionally, there are likely many other AI builders that could view Fermi’s permit-and-power setup as an increasingly valuable, scarce strategic asset, and that scarcity value only rises as permitting timelines stretch. There are corporate complexities, and I will not extrapolate a sum-of-the-parts other than to believe we have seen clear indications that the market puts a significant premium on “now” as we have seen with high priced compute access deals at SPCX by Anthropic and Google.
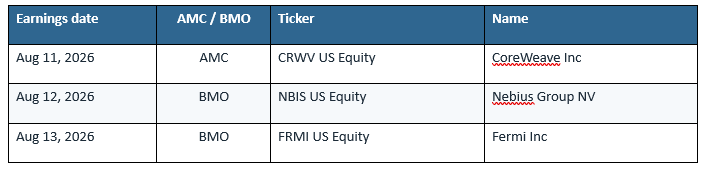
Earnings next week
Several names in the theme report next week and should sharpen the strategy and provide updates on the items above. We are not taking a specific view on the prints; we are noting the dates and the areas we will be covering across the group:
- Open-source debate.
- Competitive dynamics for the neo-clouds.
- Debt-market commentary for scaling.
- Build-out progress — GW added in the quarter.
Source: Bloomberg
Please reach out if you’d like to discuss this or other names in the theme.

