

Bottom Line: ROIC Risk and AI Capex
Earnings reports from GOOG, META, MSFT and AMZN have reduced some ROIC risk fears. The ROIC risk reduction is related to the strong compute demand comments (confirmed by H100 rental prices). The firm AI capex estimates support the AI buildout beneficiaries. The new information is some levered holders of AI Capex Beneficiaries being washed out and South Korean authorities signaling direct investments into SK AI stocks. The Momentum factor seems to have clearer short-term support. We are not saying chase today, just marking to market. We like the AI Build Beneficiaries and Momentum longer term. But volatility in the AI Capex Beneficiaries and Price Momentum factor needs to come down for investors to get more comfortable in Alpha generation. We think that will happen over time as the normal economic expansion continues
Relevant News: June PCE and Q2 GDP Point to Strong Underlying Economy
June’s core PCE numbers came in a few bps below informed consensus, largely due to softness in the non-market components of core services ex housing. The print was solid enough anyways but as a source of a beat this is the least cyclically informative. Q2 GDP came in slightly softer than expected but the underlying domestic demand signal was appreciably stronger with private final domestic demand growing 3.9%, its strongest pace since ‘23Q1 (also true for PFDD ex-software and IT goods investment). As we have noted at other times recently, nominal domestic demand growth simply seems too strong to be consistent with an imminent return of inflation to target. For the Fed this data will do little to shift views on net.
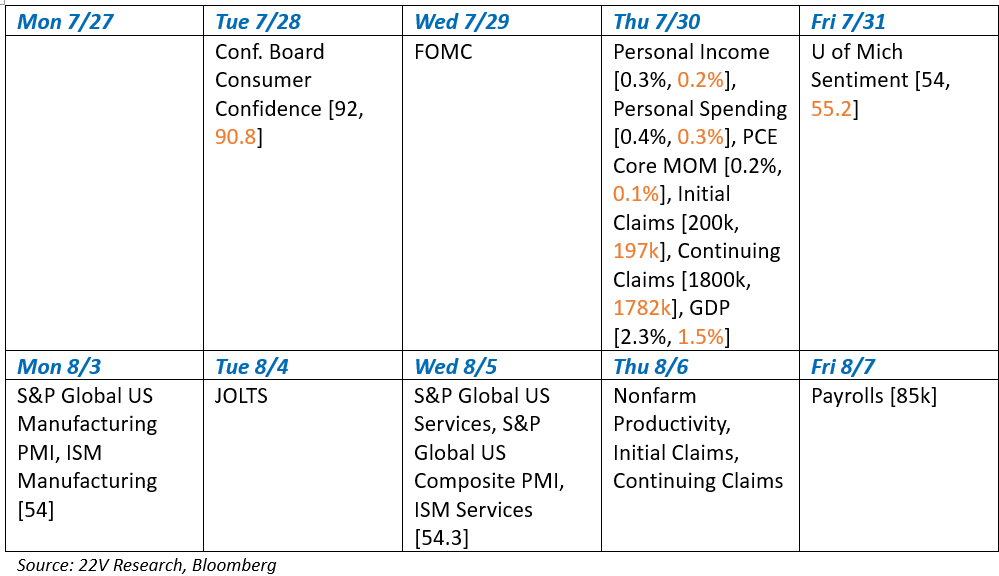
Things to Watch [Consensus, Results]:
Strategy:
Fundamentals are Supporting AI Buildout Names– (HERE)
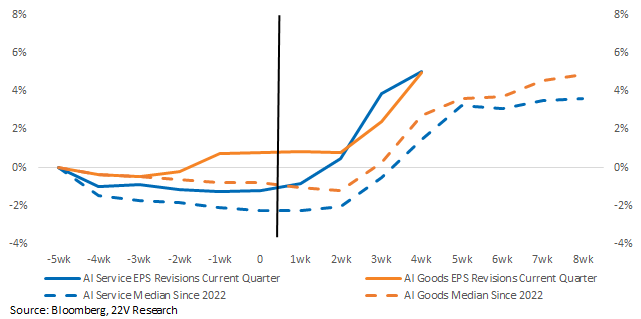
We are constructive on Service companies that use AI. Open source models are gaining popularity and are less of a threat to the application layer than frontier labs training on their data. Then using that data to put many service companies out of business. High AI usage services are beating EPS estimates at nearly the same rate as last quarter (85.5% vs. 84.9%). This quarter, though, beats are more concentrated in the 0–10% range, and all beat sizes have generated positive average relative performance. Further, margin sentiment for the AI service basket has accelerated. That is consistent with margin expansion across the index. AI service companies, with and without Software names included have unusually high margins.
China:
China: Politburo Signals Only Incremental Support in Q3– (HERE)
China’s Politburo meeting reinforced Beijing’s preference for incremental support over large-scale stimulus. Policymakers will rely on faster fiscal spending and existing investment programs to keep 2026 GDP growth on track for its 4.5–5% target, while maintaining a modest easing bias from the PBOC. However, the lack of meaningful new measures for consumption, property, or excess capacity suggests domestic demand will remain weak, leaving China’s structural imbalances largely unchanged and limiting the upside for growth beyond a temporary boost in Q3.

