Bottom Line: Impact of 1-2 Hikes
Assuming one or two hikes, which is the 22V call, the impact on financial conditions will be modest and Fundamental factors (Earnings Momentum, GARP, Value, Growth Momentum) and risk assets will face minimal headwinds. Consistent with normal economic expansion, correlations should come down. Lower correlations, or alpha generation within the Price Momentum factor is more interesting now. Two hikes over the next 6-8 months along with lower oil prices and 10yr yields in the 4.5% range would support Non-AI related Cyclicals (Banks, Retail, Transports and Homebuilders. Homebuilders are more of a trade).
Relevant News: FOMC This Week
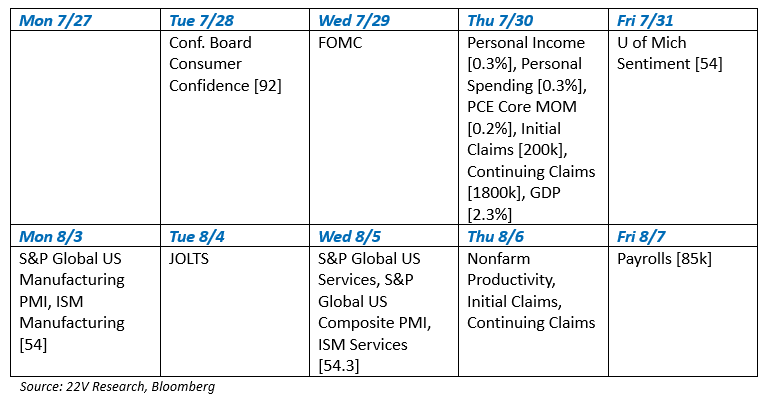
If we are to get a Fed rate hike this week, that would reflect the median FOMC participant sensing future rate hikes are inevitable and that there may be a benefit to hiking sooner rather than later. Warsh can seize the moment and establish his price stability bona fides early. July hike odds are still 38%.
Things to Watch [Consensus, Results]:
Strategy:
A Few Rate Hikes Doesn’t Put the Economic Expansion at Risk + Margin Sentiment in 2Q is Constructive for AI Capex – (HERE)
So far in earnings season S&P 1500 margins continue to grind higher. Margin sentiment for small, mid and large cap companies has increased. It can’t be proven definitively that AI tools are the reason margin expansion is happening, but AI usage is increasing across small, mid and large cap stocks. AI capex trends should be expected to persists if companies are increasingly using AI tools and margins are expanding. That is a support for the AI Capex Beneficiaries longer term. 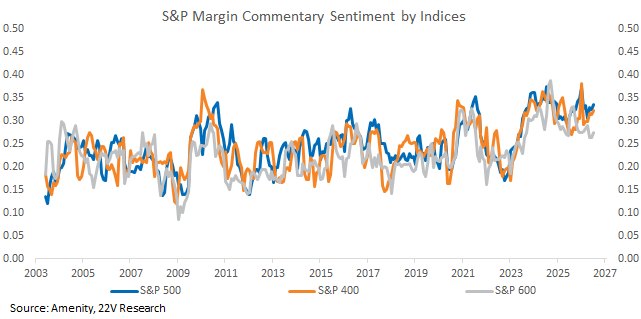
Quant:
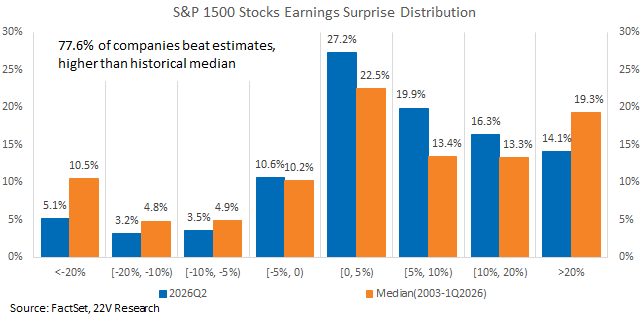
Strong Sales but Less Exciting EPS Trends Delivers Mixed Price Momentum Outlook – (HERE)
Earnings surprise for the S&P 1500 remains strong in 2Q. With 20% of companies reported, 77.6% beating estimates. The distribution is less polarized in 2Q than normal and relative to last quarter. Fewer names are posting extreme beats or misses (exceeding +/-20%) while the percentage posting 0-20% beats has increased. The net is that that breadth of earnings beats has improved even as index EPS growth has accelerated to ~27% y/y.
Derivatives:
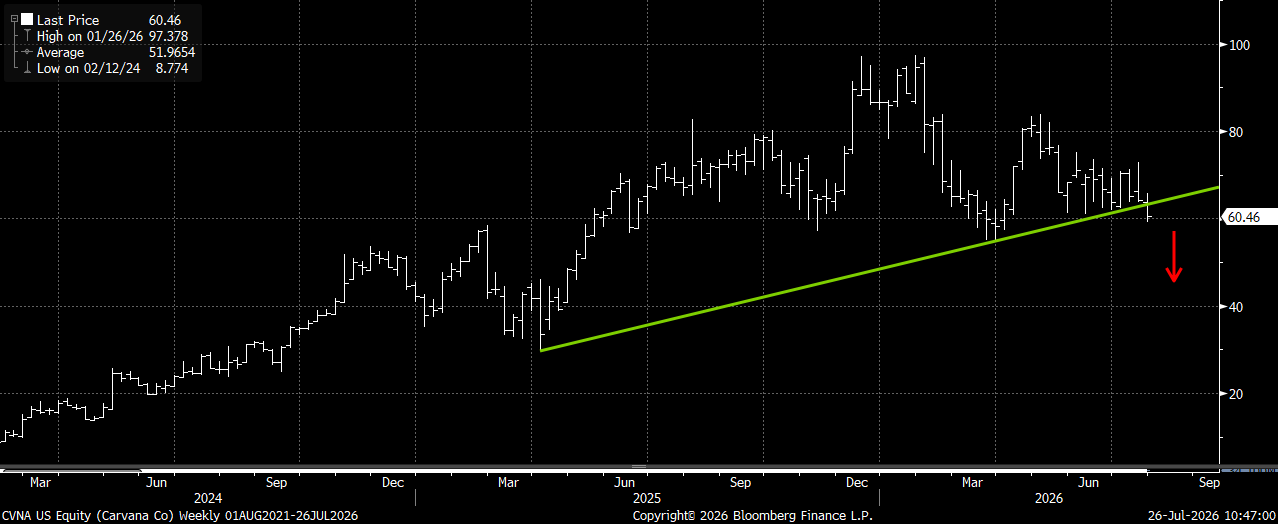
Buy Carvana (CVNA) Weekly Put Spreads Ahead of Earnings Later this Week– (HERE)
Carvana (CVNA) is highlighted by both our quant and technical teams as a potential downside earnings candidate. While options are pricing an implied move of roughly 11.7%, the stock has averaged more than a 17% move over the nine earnings reports prior to last quarter, suggesting room for a larger reaction if results disappoint. Given the deteriorating technical setup—similar to Tesla ahead of its recent post-earnings decline—we favor owning the July 31 $56/$46 put spread as a defined-risk way to position for potential downside while benefiting from a favorable risk/reward profile.